

CNA Financial Corporation CNA can potentially sustain growth even as insurance pricing softens, but the growth mix is likely to shift from rate-driven expansion toward new business, retention, specialization and disciplined underwriting.
In the second quarter of 2026, CNA’s P&C net written premiums increased 4% year over year, despite a renewal premium change of only 2% and flat renewal rate increases. Importantly, new business grew 11% to a record $718 million, while retention remained strong at 83%. This indicates that CNA is increasingly generating premium growth through customer acquisition and portfolio management rather than relying solely on higher renewal rates.
CNA’s Specialty and Commercial businesses provide additional avenues for growth. Specialty NWP increased 5% in the second quarter, while Commercial NWP also rose 5%. Management said it continues to identify opportunities to write accounts at appropriate prices, terms and conditions while pulling back from areas where risk-adjusted returns are less attractive. This selective approach could help CNA defend underwriting profitability as competition increases and pricing moderates.
However, investors will need to monitor whether CNA can maintain premium growth without sacrificing margins. CNA’s second-quarter P&C underlying combined ratio deteriorated to 94.2% from 91.7%, while the underlying loss ratio increased to 64.1%. The pressure was particularly evident in Commercial, where the underlying combined ratio rose to 92.8% from 90.6%.
CNA's growth story is becoming less dependent on pricing and more reliant on 11% new-business growth, strong retention, specialty-market opportunities and disciplined risk selection. Higher investment income also provides some earnings support, with second-quarter net investment income rising to $701 million.
What About Other Players?
The Travelers Companies, Inc. TRV faces the challenge of softer insurance pricing, particularly in its Business Insurance operations, where moderating renewal rates could reduce the contribution of pricing to premium growth. In the second quarter of 2026, Business Insurance net written premiums increased 5%, excluding the impact of the Canadian divestiture, while renewal premium change was 4.8%. This means Travelers increasingly needs to generate growth through new business, retention, and exposure growth rather than relying on higher renewal prices. At the same time, Travelers must maintain underwriting discipline, as slower pricing growth can make it harder to absorb claims inflation and other loss-cost pressures.
Chubb Limited CB is also facing softer insurance pricing, particularly in commercial property, but the impact is uneven across its portfolio. In the second quarter of 2026, Chubb said soft underwriting conditions persisted in large-account and E&S property, while softer conditions were also spreading to certain casualty and financial-lines businesses. This pressured North America Commercial P&C NWP, which declined 2.3% year over year, although NWP excluding large-account and E&S property increased 4.1%. Chubb is responding by maintaining underwriting discipline rather than pursuing volume at inadequate prices. Management noted that it would not knowingly underwrite business at a loss. Growth is increasingly coming from areas with better opportunities, including Middle Market and Small Commercial, which grew 8.9%, as well as international markets, where Overseas General NWP increased 10.2%.
CNA’s Price Performance
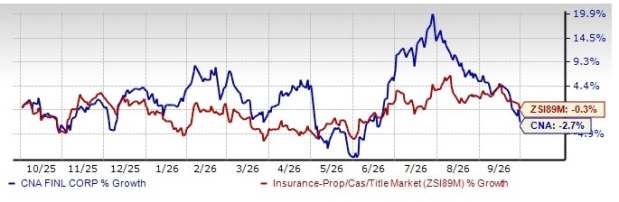
Shares of CNA have lost 2.7% in the past year compared with the industry.
Image Source: Zacks Investment Research
CNA’s Undervaluation
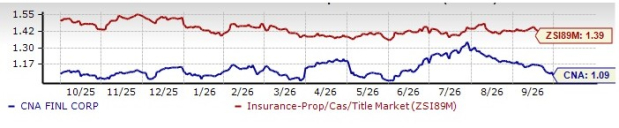
The stock is undervalued compared with its industry. It is currently trading at a price-to-book value multiple of 1.09, lower than the industry average of 1.39. It carries a Value Score of B.
Image Source: Zacks Investment Research
Estimate Movement for CNA
The Zacks Consensus Estimate for CNA’s third-quarter 2026 EPS moved down 1.6% in the past 60 days. The same for full-year 2026 EPS has moved up 2.4% in the past 60 days.
Image Source: Zacks Investment Research
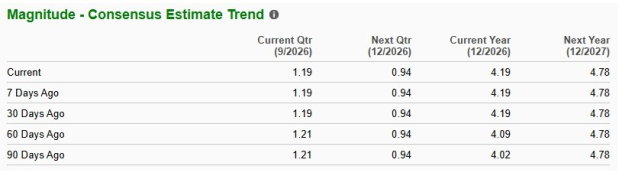
The consensus estimate for CNA’s 2026 revenues and 2027 EPS and revenues indicates a year-over-year increase.
CNA stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CNA Financial Corporation (CNA): Free Stock Analysis Report
The Travelers Companies, Inc. (TRV): Free Stock Analysis Report
Chubb Limited (CB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).