

BlackBerry Limited BB is showing a stronger earnings profile as QNX expands, profitability improves and cash generation accelerates. Fiscal second-quarter 2027 results reinforced that progress, while management raised its full-year revenue and adjusted EBITDA outlook.
The harder question is valuation. BlackBerry trades well above its own historical sales multiple, leaving investors to weigh a better operating trajectory against a higher execution bar.
BlackBerry’s QNX Growth Strengthens the Bull Case
QNX delivered record quarterly revenue of $80.3 million, up 27.3% year over year, while adjusted EBITDA rose 41.5% to $29 million. The segment posted a 36% adjusted EBITDA margin as higher-margin royalties benefited from earlier design wins entering production.
QNX also had an approximately $950 million royalty backlog at the end of fiscal 2026, while first-half fiscal 2027 design-win value exceeded any prior full year. NVIDIA Corporation NVDA is expanding its Hyperion autonomous-vehicle platform. Mobileye Global Inc. MBLY is also growing EyeQ6H-based advanced driver-assistance programs, underscoring the broader software-defined vehicle opportunity.
BB’s Cash Flow and Profitability Are Improving
BlackBerry generated $29.3 million of operating cash flow and $28.1 million of free cash flow in the second quarter. First-half operating cash flow improved to about $34 million from a $14 million use of cash a year earlier.
Image Source: Zacks Investment Research
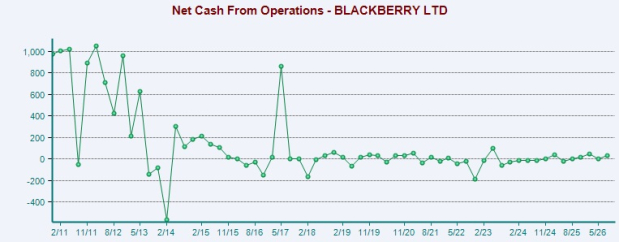
Management expects approximately $115 million of operating cash flow for fiscal 2027. That improvement gives BlackBerry more flexibility to fund QNX growth while evaluating selective acquisitions and opportunistic share repurchases.
BlackBerry’s Secure Communications Picture Is Mixed
Secure Communications generated $60.9 million in second-quarter revenues, up 2% year over year, and annual recurring revenue reached $221 million. The recurring base and government relationships provide stability despite uneven deal timing.
Still, dollar-based net retention slipped to 91%, while adjusted gross margin fell to 61% from 66% a year earlier. Segment adjusted EBITDA declined 18% to $8 million, showing that contract mix remains an important variable.
BB Trades at a Premium to Its Historical Median
BlackBerry’s trailing 12-month EV/Sales ratio is 7.96, compared with a five-year median of 3.84. The premium reflects substantially higher expectations than investors assigned during weaker periods.
Future returns therefore depend more heavily on sustained QNX growth, margin expansion and timely conversion of design wins into royalties. Better execution can support a higher valuation, but the current multiple leaves less room for operational setbacks.
BlackBerry’s Execution Risks Still Matter
QNX royalties remain exposed to vehicle-production schedules and software deployment timing. Large government contracts can shift between quarters, while lengthy procurement cycles can make Secure Communications results uneven.
Licensing adds another source of volatility. Second-quarter licensing revenues jumped to $22.1 million on a new arrangement, but management expects about $6 million in the third quarter. Research and development expense also rose to $33.2 million from $25.6 million a year earlier, underscoring the investment needed to stay competitive.
BB’s Style Scores Favor Growth Over Value
BlackBerry’s improving operations support the growth case, but valuation argues against treating the stock as an easy bargain. The stock currently carries a Zacks Rank #3 (Hold), favoring a measured stance rather than an aggressive buy signal.
The Growth Score of A and Momentum Score of A point to favorable growth and price-trend characteristics, while the Value Score of F highlights the valuation concern. The VGM Score of B is constructive, but QNX execution and cash-flow progress remain important to sustaining the premium. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BlackBerry Limited (BB): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Mobileye Global Inc. (MBLY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).