

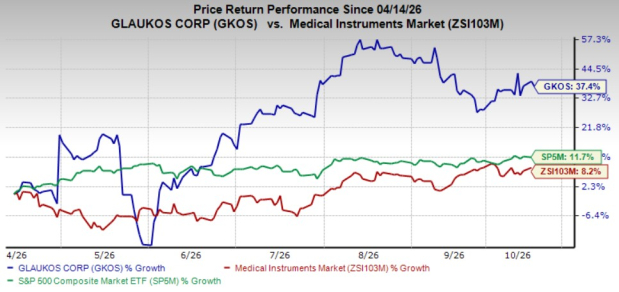
Glaukos Corporation GKOS shares have gained 36.8% over the past six months, outperforming its industry’s 8% growth. This reflects growing investor confidence in its ophthalmic treatment portfolio. The rally has been supported by the commercial expansion of iDose TR, progress in launching Epioxa for keratoconus, and clinical and pipeline developments that strengthen the company's long-term growth prospects.
Headquartered in Aliso Viejo, CA, Glaukos develops pharmaceutical and medical technology solutions for glaucoma, corneal disorders and retinal diseases. Its focus on interventional therapies, which seek to improve treatment outcomes while reducing reliance on conventional approaches, provides multiple growth opportunities. Recent commercial milestones, better-than-expected results and encouraging clinical developments have reinforced the investment case for GKOS.
Here, we examine the key factors that may have driven GKOS’ significant share price gains over the past six months.
Image Source: Zacks Investment Research
Commercial Progress With Epioxa
The first catalyst over the past six months was the receipt of a permanent Healthcare Common Procedure Coding System (HCPCS) J-code for Epioxa. Code J2789 became effective on July 1. The product-specific code should help streamline reporting and reimbursement by U.S. payers, supporting market access for the company's epithelium-on corneal cross-linking therapy. This milestone strengthened the commercial launch framework for Epioxa, which treats keratoconus, a progressive, sight-threatening corneal disease.
Earlier this month, Glaukos reported positive three-year results from a Phase 3 extension study of Epioxa. Treated eyes maintained a 1.9-diopter improvement in maximum corneal curvature from baseline, while 29% gained at least two lines of best-corrected visual acuity. The results supported the therapy's potential to deliver durable benefits following a single treatment. The benefits demonstrated in the clinical study may lead to higher adoption of the drug going forward.
Strong Q2 Results and Higher Guidance
Glaukos’ second-quarter results provided a strong fundamental basis for the rally. Consolidated net sales increased approximately 50% year over year to a record $185.6 million, prompting management to raise its 2026 revenue guidance to $680-$700 million from $620-$635 million. The company also recorded lower-than-expected loss during the quarter. Loss per share of 14 cents beat the Zacks Consensus Estimate by 50%.
The U.S. glaucoma franchise generated $118.5 million in sales, up 64% year over year, with iDose TR contributing approximately $74 million. International glaucoma sales increased 17% to $36.6 million, while Corneal Health revenues rose 48% to $30.4 million, including approximately $11 million from Epioxa.
Management also highlighted progress in Epioxa’s commercial rollout, with access pathways covering more than 125 million commercially insured U.S. lives and a treatment-center network spanning locations that serve roughly 85% of the U.S. population. These developments indicate that Glaukos is establishing the infrastructure needed to translate clinical interest into sustained commercial growth.
Positive Clinical Evidence and Pipeline Expansion
Glaukos’ uptrend has also been supported by continued progress with its pipeline development. Successful clinical trials can pave the way for further studies or regulatory approvals, ultimately enabling commercialization and improving sales prospects.
In June, Glaukos announced completion of patient enrollment in the Phase 2 study of GLK-321, an investigational treatment for Demodex blepharitis. The candidate uses the company's iLution platform, which is designed to deliver medication through the eyelid skin rather than conventional eye drops. The enrollment milestone advanced its ocular-surface disease pipeline and expanded the company's opportunities beyond its established glaucoma and corneal franchises.
The momentum continued in July as Glaukos completed patient enrollment in the U.S. pivotal study of PRESERFLO MicroShunt, a minimally invasive drainage device intended to lower intraocular pressure in patients with primary open-angle glaucoma who have not responded adequately to previous medical and surgical treatment. The milestone advanced the program toward a potential FDA marketing submission soon.
Last week, Glaukos announced an exclusive licensing agreement with RevOpsis Therapeutics for RO-104, an investigational tri-specific biologic targeting three angiogenic pathways implicated in retinal diseases. The agreement also provided rights to develop up to four additional retinal biologic candidates, broadening Glaukos' longer-term innovation opportunities.
During the same week, positive Phase 4 results for iDose TR used in conjunction with cataract surgery marked another encouraging clinical milestone. At three months, the combination achieved an 11.1-mmHg reduction in mean diurnal intraocular pressure, compared with 7.4 mmHg for cataract surgery alone. The statistically significant results strengthened the evidence supporting iDose TR across different treatment settings.
Concerns for GKOS
Glaukos faces reimbursement uncertainty for iDose TR, as proposed Medicare coverage policies could introduce treatment restrictions and affect adoption. Epioxa's commercialization also faces near-term volatility as providers transition to its permanent J-code, potentially delaying revenue realization.
International operations remain exposed to competitive pressures and reimbursement headwinds in Germany and Switzerland. Moreover, sustained investments in commercial infrastructure and clinical development could delay profitability, while the success of pipeline candidates remains subject to clinical and regulatory risks.
Conclusion
Glaukos’ six-month rally reflects a combination of robust revenue growth, raised guidance, improving commercialization prospects and positive clinical developments. Carrying a Zacks Rank #2 (Buy) at present, the company is likely to sustain its uptrend on the back of continued adoption of iDose TR and Epioxa, while its expanding pipeline offers additional long-term opportunities.
Glaukos Corporation Price
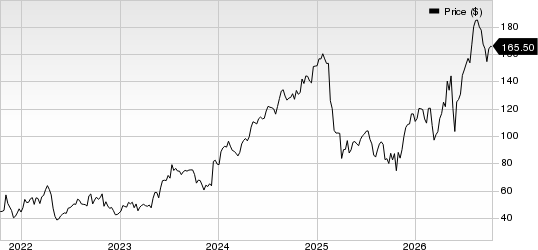
Glaukos Corporation price | Glaukos Corporation Quote
A Glance at GKOS’ Estimates
The Zacks Consensus Estimate for 2026 suggests a 64.4% narrower loss of 32 cents per share while the same for 2027 EPS is pinned at 55 cents per share. In the past 60 days, the Zacks Consensus Estimate for the company's 2026 loss per share has narrowed 8.6%.
Revenues for 2026 are projected to grow 36.2% to $691 million, followed by a 20.9% jump to $835.2 million in 2027.
Other Key Picks
Some other top-ranked stocks from the broader medical space are OPKO Health OPK, Globus Medical GMED and Merit Medical Systems MMSI.
OPKO Health, currently flaunting a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted loss of 1 cent per share, which surpassed the Zacks Consensus Estimate by 87.5%. Revenues of $163.6 million beat the Zacks Consensus Estimate by 24.7%. You can see the complete list of today’s Zacks #1 Rank stocks here.
OPK has an estimated earnings growth rate of 23.3% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 95.1%.
Globus Medical, currently carrying a Zacks Rank #2, reported a second-quarter 2026 adjusted EPS of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Merit Medical Systems, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $1.19, which beat the Zacks Consensus Estimate by 23.9%. Revenues of $418.8 million surpassed the Zacks Consensus Estimate by 3.5%.
MMSI has an estimated long-term earnings growth rate of 10.4%. MMSI’s earnings surpassed estimates in each of the trailing four quarters, with the average surprise being 14.1%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Glaukos Corporation (GKOS): Free Stock Analysis Report
Merit Medical Systems, Inc. (MMSI): Free Stock Analysis Report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).