

The consumer lending industry continues to evolve amid changing borrowing trends, credit conditions and the growing adoption of technology-driven lending solutions. OneMain Holdings OMF and Pagaya Technologies PGY are two companies positioned to capitalize on opportunities in this market. While OneMain focuses on providing personal loans and auto financing to non-prime consumers, Pagaya leverages artificial intelligence (AI) to enhance credit underwriting and expand lending opportunities through its financial institution partners.
OneMain’s diversified lending portfolio, established customer base and expanding auto finance operations support its growth prospects. Meanwhile, Pagaya’s AI-powered lending network, growing partnerships and expanding presence in personal and auto loans offer opportunities to increase network volume and strengthen its revenue base.
Although both companies have growth opportunities, differences in their operating models, credit risk exposure and funding strategies could influence their long-term performance. Against this backdrop, let us compare OMF and PGY’s fundamentals, growth prospects, earnings estimate revisions and valuations to determine which stock presents a more compelling investment opportunity.
The Case for PGY
Pagaya has been strengthening its position in AI-driven consumer lending through its expanding presence in personal loans, auto finance and point-of-sale (POS) financing. Its capital-efficient business model, growing lending partnerships and technology-driven underwriting capabilities support network expansion. In the first half of 2026, network volume reached $6.2 billion, driven largely by auto and POS lending growth. With access to more than 40% of the U.S. dealer market, Pagaya is well-positioned to capitalize on opportunities in auto financing.
Pagaya’s diversified funding ecosystem remains a key competitive advantage. In the second quarter of 2026, it raised $3.7 billion across six asset-backed securitization (ABS) transactions and expanded its institutional investor base to 174. The company also secured its first forward flow agreement with Neuberger Specialty Finance for up to $700 million in auto loans. Further strengthening its funding capabilities, Pagaya closed its 100th ABS transaction, a $650-million auto loan securitization, on Oct. 12, bringing lifetime ABS issuance above $44 billion and 2026 issuance above $10 billion.
PGY’s proprietary AI technology and multi-product expansion provide additional growth opportunities. Its pre-screening capabilities, Affiliate Optimizer engine and Experian Activate solution help lending partners expand credit access and improve customer engagement. In the second quarter, Affiliate Optimizer contributed more than $1 billion in network volume, while application volume increased 29% year over year. The company also onboarded seven new partners over six months across personal loans, auto and POS, supporting deeper market penetration and revenue diversification.
Improving operating leverage and disciplined expense management are supporting Pagaya’s profitability. In the first half of 2026, total revenues and other income increased to $705 million from $616.4 million a year earlier, while total costs and operating expenses rose modestly to $519.2 million from $512.2 million. Management expects 2026 GAAP net income of $155-$180 million and adjusted EBITDA of $460-$490 million, reflecting confidence in continued business scalability and margin expansion.
Pagaya expects 2026 network volume of $12.5-$13.25 billion, supported by higher penetration among existing partners, auto lending momentum and new product initiatives. However, dependence on institutional funding, lending partner activity and consumer credit conditions remains a risk. Sustained network growth, disciplined costs and continued funding access will be crucial to translating its expanding lending ecosystem into durable earnings growth.
The Case for OMF
OneMain provides secured and unsecured personal installment loans for debt consolidation, home improvements, medical expenses and other personal needs. With approximately 1,300 locations across 47 states, the company maintains an extensive distribution network. It also offers optional credit and non-credit insurance products, including life, disability and involuntary unemployment insurance, supporting revenue diversification.
Revenue growth remains a key strength for OneMain. The company saw a revenue compound annual growth rate (CAGR) of 4.9% between 2020 and 2025, with the momentum continuing in the first half of 2026, supported by higher interest income, improved loan yields and other revenue streams. Its focus on product innovation and expansion into auto finance and credit cards is expected to drive growth.
OneMain maintains a diversified funding structure, supported by secured revolving credit facilities, credit card funding lines and asset-backed securitizations. As of June 30, 2026, the company had $23.1 billion in total debt and $567 million in cash and cash equivalents. Its long-term corporate debt ratings of BB from S&P, Ba2 from Moody’s and BB+ from Kroll reflect its below-investment-grade credit profile. Nevertheless, access to multiple funding channels provides financial flexibility and supports lending operations.
Despite its exposure to subprime borrowers and economic uncertainties, OneMain emphasizes disciplined underwriting, centralized data analytics and proactive loan servicing to manage credit risks. Its Front Book and Back Book loan mix helps balance portfolio returns and credit performance across economic cycles. Continued investments in risk management, coupled with diversification into auto finance and credit cards, are expected to strengthen business resilience.
OneMain remains committed to enhancing shareholder value through dividends and share repurchases. Since initiating dividends in 2019, the company has increased its payout eight times, with the latest hike of approximately 1% announced in October 2025. Its board also authorized a $1-billion share repurchase program through Dec. 31, 2028, with $826.7 million remaining available as of June 30, 2026. Despite its substantial debt burden, steady revenue growth, diversified funding sources and disciplined capital management are expected to support shareholder distributions.
PGY & OMF: Price Performance, Valuation & Other Comparisons
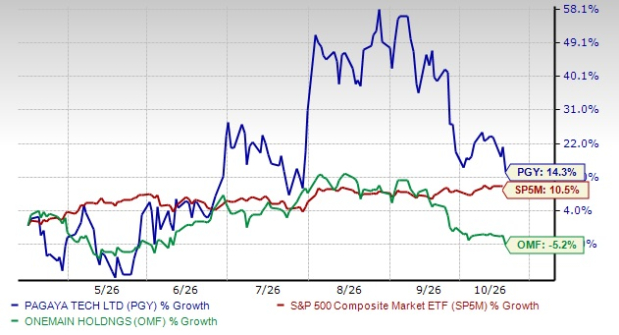
In the past six months, shares of Pagaya have gained 14.3%, outperforming the S&P 500 Index’s 10.5% growth. In the same time frame, the OMF stock has lost 5.2%.
Hence, in terms of investor sentiment, PGY has the edge.
6-Month Price Performance
Image Source: Zacks Investment Research
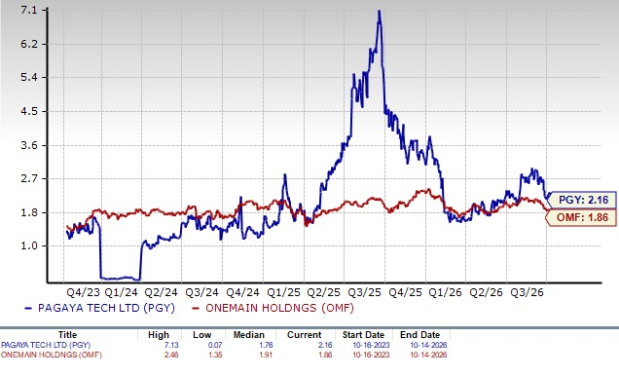
From a valuation perspective, Pagaya is currently trading at a trailing 12-month price-to-book (P/B) of 2.16X, while the OMF stock is trading at a trailing 12-month P/B of 1.86X. So, in terms of valuation, PGY is expensive compared with OneMain.
P/B TTM
Image Source: Zacks Investment Research
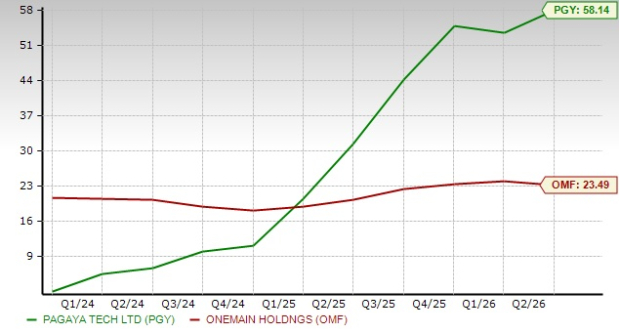
Pagaya’s return on equity (ROE) of 58.14% is above OneMain’s 23.49%. This reflects that PGY is more efficient in using shareholder funds to generate profits.
ROE
Image Source: Zacks Investment Research
Pagaya & OneMain’s Earnings & Sales Prospects
The Zacks Consensus Estimate for PGY’s 2026 and 2027 revenues indicates year-over-year growth of 11.8% and 14.2%, respectively.
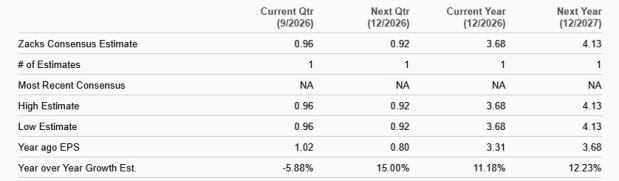
The consensus estimate for PGY’s earnings indicates 11.2% and 12.2% year-over-year growth for 2026 and 2027, respectively.
PGY’s Earnings Growth Estimate
Image Source: Zacks Investment Research
On the contrary, the Zacks Consensus Estimate for OMF’s 2026 and 2027 revenues implies year-over-year increases of 6% and 7.5%, respectively.
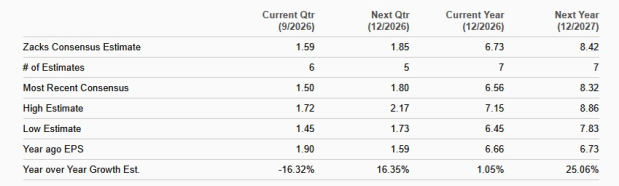
Also, the consensus estimate for OneMain’s earnings indicates 1.1% growth for 2026 and a 25.1% rise for 2027.
OMF’s Earnings Growth Estimate
Image Source: Zacks Investment Research
PGY or OMF: Which Stock Offers Better Upside Potential?
Pagaya’s AI-driven lending platform, expanding partner network and capital-efficient business model position it well for long-term growth. Its stronger revenue and earnings growth projections for 2026, superior ROE and favorable share price performance give it an edge over OneMain. However, its relatively expensive valuation, dependence on institutional funding and exposure to changing credit conditions remain concerning.
Meanwhile, OneMain benefits from its established lending operations, diversified funding sources and consistent shareholder returns. Its relatively attractive valuation and stronger earnings growth outlook for 2027 are encouraging, although elevated debt levels and exposure to non-prime borrowers pose risks.
Despite their growth opportunities, both PGY and OMF currently carry a Zacks Rank #4 (Sell), indicating a cautious near-term outlook. Hence, investors may prefer to stay on the sidelines for now and await more favorable earnings estimate revisions and an improvement in their Zacks Ranks before considering either stock.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
OneMain Holdings, Inc. (OMF): Free Stock Analysis Report
Pagaya Technologies Ltd. (PGY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).