

Kinder Morgan, Inc. KMI reported third-quarter 2026 adjusted earnings of 35 cents per share, beating the Zacks Consensus Estimate of 33 cents by 6.1%. Earnings increased 20.7% from 29 cents in the year-ago quarter.
Revenues increased 9.3% year over year to $4.53 billion from $4.15 billion. Revenues surpassed the consensus estimate of $4.38 billion by 3.4%.
Strong quarterly results benefited from higher natural gas transportation and gathering volumes, alongside improved contributions from the Terminals and CO2 businesses.
Natural gas transport volumes rose 3%, while gathering volumes increased 14%.
Kinder Morgan, Inc. Price, Consensus and EPS Surprise
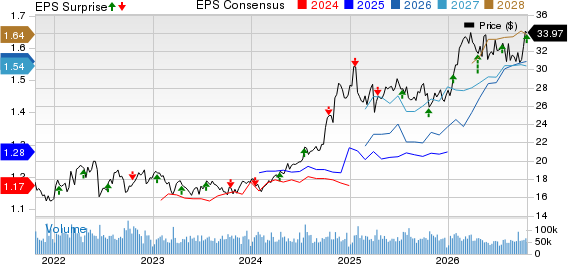
Kinder Morgan, Inc. price-consensus-eps-surprise-chart | Kinder Morgan, Inc. Quote
KMI's Natural Gas Business Drives Growth
Natural Gas Pipelines adjusted segment earnings before depreciation, depletion and amortization (EBDA) increased to $1.49 billion from $1.40 billion a year earlier. Higher contributions from the El Paso Natural Gas Pipeline, KinderHawk gathering system, Tennessee Gas Pipeline and Texas Intrastate system supported the improvement.
Transportation volumes averaged 49,273 billion British thermal units per day (BBtu/d), compared with 47,918 BBtu/d in the prior-year quarter. Growth primarily reflected higher liquefied natural gas deliveries on the Tennessee Gas Pipeline and increased demand for services on the Texas Intrastate system.
Gathering volumes advanced to 4,722 BBtu/d from 4,129 BBtu/d, primarily supported by stronger activity on the KinderHawk system.
Kinder Morgan's Other Segments Post Gains
Products Pipelines adjusted segment EBDA increased to $313 million from $288 million. Favorable commodity pricing supported performance, although legal, environmental and other expense accruals weighed on reported segment results.
Total refined products volumes declined 3% to approximately 1.60 million barrels per day from 1.65 million barrels per day, reflecting a higher commodity price environment. Crude and condensate volumes decreased 11% to 410,000 barrels per day, primarily due to lower Bakken gathering volumes and the conversion of the Double H pipeline to natural gas liquids service.
Terminals adjusted segment EBDA increased to $314 million from $274 million. Higher liquids contributions from expansion projects, stronger coal and petroleum coke handling activities and improved Jones Act tanker rates supported results. Liquids utilization declined to 92.6% from 94.6%.
CO2 adjusted segment EBDA rose to $184 million from $136 million. Total net oil production increased to 27,070 barrels per day from 25,040 barrels per day. The realized weighted average oil price increased to $68.65 per barrel from $67.74, while the realized NGL price rose to $34.48 from $31.09.
KMI's Operating Costs Rise Year Over Year
Total operating costs, expenses and other increased 9.3% year over year to $3.37 billion. Costs of sales rose to $1.57 billion from $1.40 billion, while operations and maintenance expenses increased to $949 million from $786 million.
Operating income increased 9.1% to $1.16 billion. The operating margin remained relatively stable at 25.6%, reflecting comparable growth in revenues and operating expenses.
Adjusted EBITDA reached a third-quarter record of $2.18 billion, up 9% year over year. Net income attributable to KMI increased 22% to $764 million, while reported earnings rose to 34 cents per share from 28 cents.
Kinder Morgan Expands Its Project Backlog
The expansion project backlog reached $14.4 billion at quarter-end, increasing $4.7 billion sequentially. The company added $5.4 billion in projects, partially offset by $700 million of projects placed into service. Natural gas projects accounted for $13.2 billion of the backlog.
Major additions included the Southeast Connector and Permian Link projects, designed to transport approximately 2.6 billion and 2.8 billion cubic feet per day of natural gas, respectively.
More than 75% of the total backlog supports power generation and local distribution demand, highlighting growing infrastructure requirements.
KMI's Cash Flow & Balance Sheet
Cash flow from operations increased to $1.59 billion from $1.41 billion in the year-ago quarter. Free cash flow declined to $545 million from $621 million, while free cash flow after dividends was negative $120 million.
As of Sept. 30, 2026, cash and cash equivalents totaled $918 million, compared with $63 million at 2025-end. Net debt stood at $32.23 billion. The net debt-to-adjusted EBITDA ratio improved to 3.5 from 3.8 at the end of 2025.
Kinder Morgan Raises Its 2026 Outlook
Kinder Morgan expects full-year adjusted EBITDA to exceed its original $8.6 billion budget by more than 6%. Adjusted earnings are projected to surpass the initial $1.36-per-share budget by more than 13%.
The company also expects its year-end net debt-to-adjusted EBITDA ratio to reach 3.6, compared with the original budget of 3.8.
The board declared a quarterly dividend of 29.75 cents per share, up 2% year over year. The dividend is payable Nov. 16, 2026, to shareholders of record as of Nov. 2, 2026.
KMI’s Zacks Rank & Other Stocks to Consider
Kinder Morgan currently carries a Zacks Rank #2 (Buy).
Other top-ranked stocks from the energy sector that are yet to release their third-quarter 2026 earnings are Baker Hughes Company BKR, ConocoPhillips COP) and Equinor ASA EQNR. BKR, COP, EQNR currently sport a Zacks Rank #1 (Strong Buy) each. You can see the complete list of today’s Zacks #1 Rank stocks here.
Baker Hughes is scheduled to release third-quarter 2026 earnings on Oct. 27. The Zacks Consensus Estimate for BKR’s earnings is pegged at 64 cents per share, suggesting a 5.9% decline from the prior-year reported figure.
ConocoPhillips is scheduled to release third-quarter 2026 earnings on Nov. 5. The Zacks Consensus Estimate for COP’s earnings is pegged at $2.86 per share, suggesting a 77.6% improvement from the prior-year reported figure.
Equinor is scheduled to release third-quarter 2026 earnings on Oct. 28. The Zacks Consensus Estimate for EQNR’s earnings is pegged at $1.38 per share, suggesting a 273% improvement from the prior-year reported figure.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Kinder Morgan, Inc. (KMI): Free Stock Analysis Report
ConocoPhillips (COP): Free Stock Analysis Report
Baker Hughes Company (BKR): Free Stock Analysis Report
Equinor ASA (EQNR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).