

Citigroup Inc. C continues to navigate credit-quality challenges amid an uncertain economic environment. According to its latest SEC filing, its subsidiary, Citibank N.A., reported higher credit card delinquencies and net principal losses in September 2026, while outstanding principal receivables declined during the month.
For the period ended Sept. 25, 2026, the Citibank Credit Card Master Trust I reported principal receivables of $18.7 billion, down from $19.1 billion at the beginning of the period. Receivables delinquent for 30 days or more increased to 1.35% in September from 1.29% in August, while those delinquent for 90 days or more rose to 0.65% from 0.63%. The Citibank Credit Card Issuance Trust’s annualized net principal loss rate climbed to 2.18% from 2.03% in August and 1.90% in July, signaling a pickup in credit losses.
The detailed filing also showed that 97.3% of receivables were current in September. However, balances delinquent for 31-60 days were $80.7 million, while those delinquent for 151-180 days totaled $37.4 million. The portfolio's annualized gross yield was 25.03%, while the principal payment rate was 41.45%. Although the high portfolio yield provides a revenue cushion against credit losses, the increase in delinquencies and net principal losses warrants monitoring. These figures relate to the securitized credit card portfolios and should not be interpreted as representing Citigroup's entire loan portfolio.
Citigroup’s broader asset-quality picture remains a concern. Although provisions for credit losses declined 2% year over year to $7.91 billion in the first nine months of 2026, the metric recorded a compound annual growth rate (CAGR) of 24.5% from 2022 to 2025. However, credit quality showed improvement in the third quarter, with the U.S. Cards net credit loss rate declining to 3.6% from 4.0% a year earlier. Management’s earlier 2026 guidance projected a U.S. card net credit loss rate of 4-4.5%, highlighting continued credit risks.
Citigroup's organizational overhaul, business simplification initiatives and focus on operational efficiency could support profitability over the longer term. However, persistent inflation, pressure on borrowers' repayment capacity and rising card losses could weigh on asset quality. Any sustained deterioration in credit trends may lead to higher provisions and constrain earnings growth, even as the company benefits from resilient net interest income and a stronger focus on core businesses.
How Citigroup Stacks Up Against Peers in Card Delinquency
U.S. credit card metrics were mixed in September 2026, with delinquency rates increasing at both Bank of America BAC and JPMorgan Chase JPM, although the latter's rate remained relatively low. Both issuers reported lower outstanding receivables, while net charge-off and loss rates improved compared with the previous month.
Bank of America reported that the BA Master Credit Card Trust II delinquency rate increased to 1.37% in September 2026 from 1.28% in August. However, its net charge-off rate declined to 2.09% from 2.15% in August, indicating some improvement in credit losses. Total receivables fell to $14.53 billion from $14.63 billion at the beginning of the month.
JPMorgan Chase reported a delinquency rate of 0.81% for the Chase Issuance Trust in September 2026, with $95.1 million in delinquent receivables against a pool balance of $11.81 billion. Its annualized net loss rate was 1.52%. Principal receivables declined to $11.65 billion from $11.84 billion at the beginning of the month.
Citigroup’s Price Performance & Zacks Rank
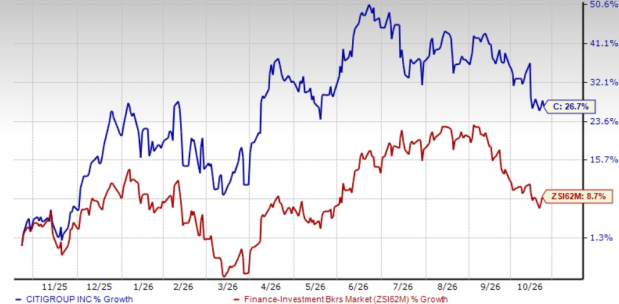
Shares of Citigroup have gained 26.7% over the past year compared with the industry’s growth of 8.7%.
One-Year Performance
Image Source: Zacks Investment Research
Currently, C carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Citigroup Inc. (C): Free Stock Analysis Report
Bank of America Corporation (BAC): Free Stock Analysis Report
JPMorgan Chase & Co. (JPM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).