

V.F. Corporation VFC is likely to register year-over-year top-line decline when it posts second-quarter fiscal 2027 earnings on Oct. 28, before the opening bell. The Zacks Consensus Estimate for quarterly revenues is pegged at $2.7 billion, indicating a 3.9% dip from the prior-year quarter’s figure.
The consensus estimate for earnings is pegged at 54 cents per share, which indicates a rise of 3.9% from the year-ago quarter’s figure. However, the metric has been stable in the past 30 days.
V.F. Corp. delivered a negative earnings surprise of 22.7% in the last reported quarter. In the trailing four quarters, the company’s earnings beat the Zacks Consensus Estimate by 34%.
V.F. Corporation Price and EPS Surprise
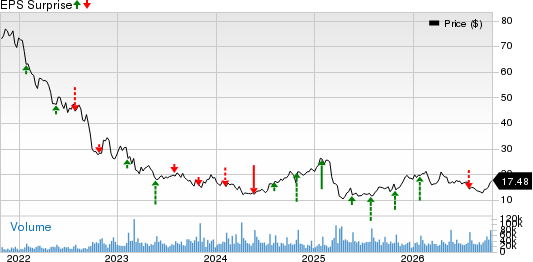
V.F. Corporation price-eps-surprise | V.F. Corporation Quote
Key Factors to Influence VFC’s Q2 Results
V.F. Corp.’s second-quarter fiscal 2027 results are likely to reflect strength in its outdoor segment and gains from The North Face, Timberland and Altra brands. The North Face has been benefiting from transitional outerwear, shells, equipment and the Altamesa V2 launch, while Timberland continued to build around the six-inch boot and boat shoe. Management expects these brands to benefit from sustained investments in product innovation, marketing and direct-to-consumer (DTC) initiatives. Altra is also likely to remain a growth driver, supported by product launches and increasing brand awareness.
In its last earnings call, management expected The North Face to deliver flat to slightly higher revenues in the fiscal second quarter. Our model expects Outdoor revenues to rise 2.6% year over year, and revenues at The North Face to grow 3.7% and Timberland to increase 7.5% in the fiscal second quarter.
The company continues to redirect resources toward DTC, marketing, technology and supply-chain capabilities. Such initiatives are likely to have boosted consumer engagement and strengthened brand relevance. The combination of direct-channel investment, inventory discipline and a diversified sourcing base offers VFC additional operating levers. VFC’s lower cost base remains a source of reinvestment and margin support. Management had also anticipated gross margin to increase year over year in the quarter under review.
However, the fiscal second quarter is expected to remain pressured by continued softness at Vans. Management projects second-quarter revenues at Vans to decline approximately 9% year over year. Weakness in Vans wholesale, foreign-exchange headwinds and muted demand in Asia-Pacific remain key risks. Macroeconomic challenges are also expected to have remained a headwind during the quarter.
The ongoing geopolitical disruptions in the Middle East, softer demand in Europe and uncertainty surrounding tariffs are likely to have pressured the revenue trends. Such limitations are likely to have pressured the top-line performance in the fiscal second quarter. VFC has implemented sourcing diversification, pricing actions and supply-chain mitigation initiatives to lessen the tariff impact. We had anticipated Vans constant-currency revenues to drop 8.9% year over year for the quarter under review.
What the Zacks Model Unveils for VFC
Our proven model conclusively predicts an earnings beat for V.F. Corp. this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chance of an earnings beat. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
V.F. Corp. currently has an Earnings ESP of +0.80% and a Zacks Rank of 3.
Valuation Picture of VFC Stock
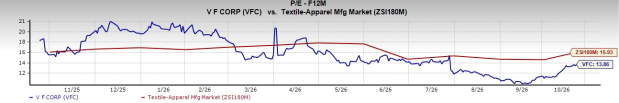
Going by the price/earnings ratio, VFC stock is currently trading at 13.86 on a forward 12-month basis, lower than 15.93 of the Textile - Apparel industry. Also, it is trading lower than its median of 15.43.
Image Source: Zacks Investment Research
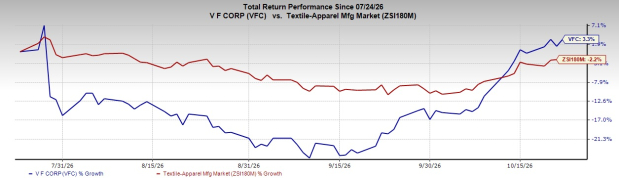
The recent market movements show that VFC’s shares have gained 3.3% in the past three months against the industry's 2.2% drop.
Image Source: Zacks Investment Research
More Stocks Poised to Beat Earnings Estimates
Here are some more companies, which according to our model, also have the right combination of elements to post an earnings beat:
Ralph Lauren Corporation RL currently has an Earnings ESP of +0.56% and a Zacks Rank of 2. RL is likely to register top and bottom-line growth when it reports second-quarter fiscal 2027 results. The Zacks Consensus Estimate for its quarterly revenues is pegged at $2.1 billion, indicating 6.1% growth from the figure reported in the year-ago quarter. You can see the complete list of today’s Zacks #1 Rank stocks here.
The consensus estimate for Ralph Lauren’s fiscal second-quarter earnings is pegged at $4.22 a share, implying 11.4% growth from the year-earlier quarter. The consensus mark has moved up a penny in the past seven days. RL has a trailing four-quarter earnings surprise of 8.7%, on average.
Carnival Corp. CCL currently has an Earnings ESP of +1.05% and a Zacks Rank of 3. CCL is likely to register top-line growth when it reports fourth-quarter fiscal 2026 results.
The Zacks Consensus Estimate for its quarterly revenues is pegged at $6.5 billion, indicating a 1.9% increase from the figure reported in the year-ago quarter. The consensus estimate for CCL’s fiscal fourth-quarter earnings is pegged at 22 cents per share, implying a 35.3% plunge from the year-ago quarter’s actual. The consensus mark has dropped a couple of cents in the past 30 days. CCL has a trailing four-quarter earnings surprise of 17.4%, on average.
Mohawk Industries, Inc. MHK currently has an Earnings ESP of +0.04% and a Zacks Rank of 3. MHK is likely to register top-line growth when it reports third-quarter 2026 results. The Zacks Consensus Estimate for its quarterly revenues is pegged at $2.9 billion, indicating 3.4% growth from the figure reported in the year-ago quarter.
The consensus estimate for MHK’s earnings has increased a penny to $2.57 per share in the past 30 days. The consensus estimate indicates a decline of 3.8% from the year-ago quarter’s actual. MHK has a trailing four-quarter earnings surprise of 12.3%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
V.F. Corporation (VFC): Free Stock Analysis Report
Carnival Corporation (CCL): Free Stock Analysis Report
Ralph Lauren Corporation (RL): Free Stock Analysis Report
Mohawk Industries, Inc. (MHK): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).