

Corning Incorporated GLW highlighted accelerating AI infrastructure demand, strong revenue growth and improving profitability during its third-quarter 2026 earnings call. Management emphasized expanding optical connectivity opportunities and customer-backed investments supporting its long-term growth strategy.
The company exceeded earnings and revenue expectations while reinforcing its Springboard targets. Executives also discussed optical capacity constraints, solar profitability, pricing actions and fourth-quarter guidance.
Corning Reports Higher Earnings and Revenues
Corning reported third-quarter 2026 core earnings of 91 cents per share, up 36% from 67 cents a year ago. Earnings surpassed the Zacks Consensus Estimate of 89 cents by 2.30%.
Corning Incorporated Price, Consensus and EPS Surprise
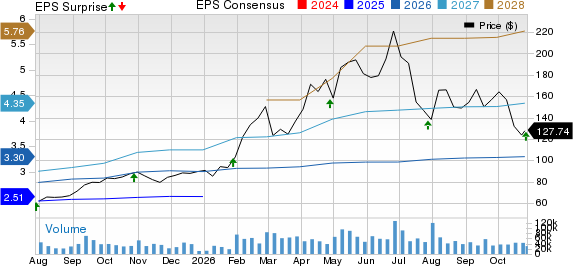
Corning Incorporated price-consensus-eps-surprise-chart | Corning Incorporated Quote
Core revenues increased 19% year over year to $5.081 billion, exceeding the Zacks Consensus Estimate of $5.028 billion by 1%. Revenues also increased 7% sequentially from $4.738 billion.
Core gross margin expanded 150 basis points year over year to 40.5%, while core operating margin improved 310 basis points to 22.7%. Core operating income increased to $1.152 billion from $838 million. GAAP earnings were 78 cents per share on reported revenues of $4.855 billion.
GLW Advances Its Springboard Growth Targets
Chairman and CEO Wendell Weeks reiterated Corning's Springboard plan to achieve annualized sales run rates of $30 billion by 2028 and $40 billion by 2030.
Weeks highlighted that third-quarter revenues represented an annualized run rate of $20.3 billion, already exceeding the company's $20 billion year-end 2026 milestone.
Management expects compound annual sales growth of 19% from 2027 through 2030, up from 15% during Springboard's first three years. Earnings are expected to grow significantly faster than revenues.
Corning Sees Expanding AI Connectivity Opportunities
Executive vice president and CFO Ed Schlesinger identified Optical Communications as the primary growth driver. Segment revenues increased 44% year over year to $2.379 billion, while net income surged 80% to $532 million.
Enterprise network revenues climbed 84%, supported by generative AI product sales growth exceeding 100%. Carrier revenues rose 4%, driven by demand for data center interconnects.
During the Q&A, a Citi analyst questioned the timing of optical adoption in scale-up networks. Weeks reaffirmed expectations for acceleration beginning in 2028, explaining that optical scale-up architectures could substantially increase fiber requirements per GPU.
GLW Addresses Capacity Constraints and Carrier Demand
A Morgan Stanley analyst questioned how Corning prioritizes capacity between enterprise and carrier customers amid rising demand for high-density optical products.
Weeks acknowledged supply tightness, particularly for newer products offering greater fiber density. He explained that long-standing customer relationships and commitments to finance capacity additions influence allocation decisions.
Schlesinger highlighted agreements with Zayo, Verizon and AT&T supporting network expansion. Management expects data center interconnect opportunities to exceed its previously communicated $1 billion target in both timing and magnitude.
Corning Balances Solar Growth With Glass Market Pressures
Solar revenues increased 37% year over year to $436 million, although the segment recorded a $7 million net loss as manufacturing facilities continued ramping production.
Schlesinger acknowledged slower-than-anticipated production improvements and expects profitability to improve gradually through 2027. Management maintained its ambition to build a solar business generating more than $3 billion in revenues.
Glass Innovations revenues declined 3% to $1.506 billion, while net income fell 10% to $328 million. Schlesinger explained that display glass price increases should primarily benefit 2027 and subsequent periods rather than materially affect the fourth quarter.
GLW Prioritizes Cash Flow and Capacity Investments
Weeks emphasized that long-term customer agreements increasingly provide upfront funding for manufacturing capacity, reducing investment exposure while securing committed purchases.
Schlesinger disclosed $639 million in net customer deposits during the first nine months of 2026. Adjusted free cash flow reached $2.272 billion despite $1.299 billion in capital expenditures.
Responding to a Bank of America analyst, Schlesinger clarified that most growth-related capital spending is supported by customer agreements. Management expects these arrangements to moderate cash flow volatility while supporting expansion.
Corning Maintains Its Near-Term Growth Outlook
Management expects fourth-quarter core revenues between $5.2 billion and $5.3 billion, representing approximately 19% year-over-year growth.
Core earnings are projected between 96 cents and $1 per share, implying approximately 36% growth. Full-year capital expenditures are expected to total approximately $2 billion.
Management maintained its focus on optical capacity expansion, improving manufacturing productivity and generating additional free cash flow while pursuing its longer-term growth targets.
GLW's Zacks Rank and Style Scores Signal Potential
GLW currently carries a Zacks Rank #2 (Buy), indicating favorable earnings estimate revision trends. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its Growth and Momentum Scores of A reflect strong growth characteristics and favorable price momentum, while its Value Score of D indicates comparatively weaker valuation attractiveness.
The stock's VGM Score of B combines its value, growth and momentum characteristics into a favorable overall assessment. This complements its Zacks Rank #2 (Buy), although the rank can change as analysts revise earnings estimates following the latest quarterly results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Corning Incorporated (GLW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).