

Continued improved pricing, exposure growth, portfolio streamlining, solid retention, renewals, reinsurance agreements and accelerated digitalization are expected to have enhanced insurance stocks’ October-quarter performance. Insurers yet to report their third-quarter results on Oct. 29 are Ryan Specialty Holdings Inc. RYAN, Arthur J. Gallagher & Co. AJG and Willis Towers Watson Public Limited Company WTW.
The insurance space is housed within the broader Finance sector (one of the 16 broad Zacks sectors within the Zacks Industry classification). Per the latest Earnings Preview, the total earnings of finance companies for the third quarter are anticipated to rise 20.6% from the prior-year quarter’s figure. These companies’ revenues are anticipated to improve 7.8%.
Factors Likely to Shape Insurers’ Performance in Q3
Better pricing, solid retention and exposure growth across business lines are likely to have driven premiums. Per the latest Marsh Global Insurance Market Index, in the third quarter of 2026, Global insurance rates continued to decline, down 5%, marking the ninth consecutive quarter of reductions amid ample capacity across nearly all regions and lines of coverage. Property rates eased for the ninth consecutive quarter, declining 10%, while casualty rates increased 1%.
The U.S. Federal Reserve raised the federal funds target range by 25 basis points to 3.75-4%, its first rate hike since July 2023, citing still-elevated inflation. The Federal Reserve is expected to leave interest rates unchanged at the conclusion of its meeting on Oct. 28, but may hike rates again before the end of the year.
A larger investment asset base, strong cash flow from operating activities, higher bond yields and an increase in interest income from fixed-maturity securities are expected to have aided net investment income.
The insurance industry’s increased use of technology like blockchain, artificial intelligence, advanced analytics, telematics, cloud computing and robotic process automation expedites business operations. Insurers continue to invest heavily in technology to improve basis points, scale and efficiencies. These investments are likely to have curbed costs and aided the margins of insurers in the third quarter.
A solid capital position is likely to have aided insurers in strategic mergers and acquisitions to sharpen their competitive edge, expand geographically and diversify their portfolio. Sustained wealth distribution to shareholders via dividend hikes, special dividends and share repurchases instills confidence in the insurers.
Let’s find out how the following insurers are positioned before their third-quarter 2026 results on Oct. 29.
Find the latest EPS estimates and surprises on Zacks Earnings Calendar.
Per our proprietary model, the combination of two key ingredients — a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) — increases the odds of an earnings beat. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Ryan Specialty Holdings: RYAN’s third-quarter 2026 results are likely to benefit from robust specialty insurance demand, strong client retention and new business wins.
Growth in casualty, professional liability, reinsurance and underwriting management operations are likely to have supported commission and fee revenues. However, softer property pricing, increased competition in casualty and binding authority markets, and tough year-ago comparisons might have constrained organic growth. Higher compensation costs, talent and technology investments and lower fiduciary investment income are likely to have pressured margins, partly offset by Empower Program efficiencies.
The Zacks Consensus Estimate for RYAN’s third-quarter earnings per share of 49 cents indicates a 4.3% increase from the year-ago quarter’s reported figure. The company has an Earnings ESP of +5.46% and a Zacks Rank #3 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
RYAN’s earnings beat estimates in two of the last four reported quarters, missed in one and matched in one, the average surprise being 5.15%. This is depicted in the chart below:
Ryan Specialty Holdings Inc. Price and EPS Surprise
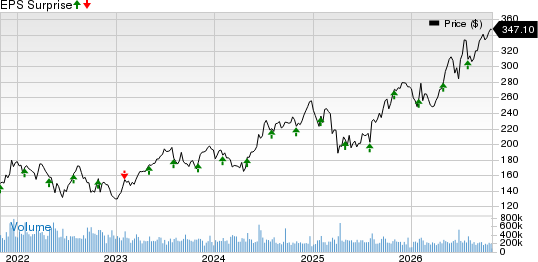
Ryan Specialty Holdings Inc. price-eps-surprise | Ryan Specialty Holdings Inc. Quote
Arthur J. Gallagher: Improved performance across the Brokerage and Risk Management segments is expected to support Arthur J. Gallagher’s third-quarter results. Strong new business generation, healthy client retention, higher renewal premiums and continued organic growth across its operations are likely to have benefited the third-quarter performance. The Brokerage segment is expected to have benefited from acquisition contributions, particularly AssuredPartners, along with higher commissions and fees. However, softer insurance pricing in certain property and casualty markets could have limited organic growth.
The Risk Management segment is likely to have benefited from demand for claims management and related services, supporting fee revenues. Continued client retention and new business generation could have further aided the segment’s performance. (Read more: Arthur J. Gallagher to Report Q3 Earnings Soon: What to Expect?)
The Zacks Consensus Estimate for the bottom line is pegged at $3.01, indicating a 29.7% increase from the year-ago quarter’s reported figure. The consensus mark for revenues is pegged at $3.97 billion, implying 19.1% growth from the year-ago quarter’s figure. The company has an Earnings ESP of -1.11% and a Zacks Rank #4 (Sell) at present.
AJG’s earnings beat estimates in three of the last four reported quarters and missed in one. The same is depicted in the chart below:
Arthur J. Gallagher & Co. Price and EPS Surprise
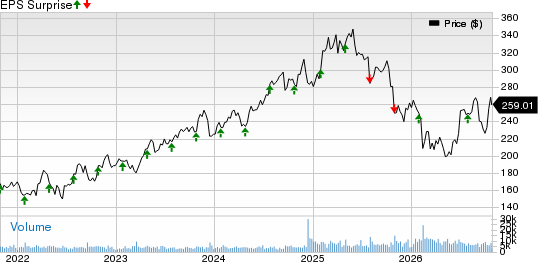
Arthur J. Gallagher & Co. price-eps-surprise | Arthur J. Gallagher & Co. Quote
Willis Tower: Revenues in the third quarter are likely to have benefited from strong performances across the segments.
Growth across all regions, with International leading the overall performance, is likely to have aided organic revenue growth in Health in the to-be-reported quarter. Wealth business revenues are likely to have benefited from higher levels of retirement work across all regions. Career revenues are likely to have been affected by increased levels of communications project work and broad-based pay work, which were likely to be offset by constrained revenues in the Middle East due to the ongoing conflict.
The Benefits Delivery & Outsourcing segment’s performance is expected to have benefited from expanded project work, new client wins and regulatory-driven work in Outsourcing. The upside is likely to be partially offset by lower commissions in Individual Marketplace. Corporate Risk & Broking is expected to have benefited from new business activity and strong client retention globally. (Read more: What's in the Cards for Willis Towers This Earnings Season?)
The Zacks Consensus Estimate for WTW’s third-quarter earnings per share of $3.60 indicates a 17.3% increase from the year-ago quarter’s reported figure. The company has an Earnings ESP of +2.33% and a Zacks Rank #4 at present.
WTW’s earnings outpaced estimates in each of the trailing four quarters, the average surprise being 3.88%. This is depicted in the chart below:
Willis Towers Watson Public Limited Company Price and EPS Surprise
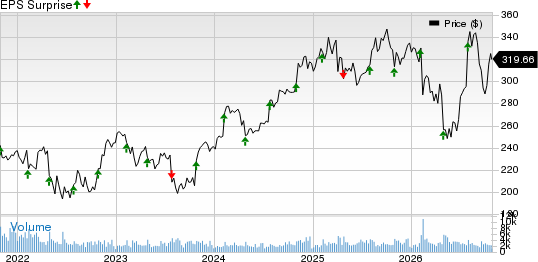
Willis Towers Watson Public Limited Company price-eps-surprise | Willis Towers Watson Public Limited Company Quote
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Arthur J. Gallagher & Co. (AJG): Free Stock Analysis Report
Willis Towers Watson Public Limited Company (WTW): Free Stock Analysis Report
Ryan Specialty Holdings Inc. (RYAN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).