

VICI Properties Inc. VICI used its third-quarter 2026 earnings call to address shareholder concerns about its stock performance, capital allocation flexibility and uncertainty surrounding its Caesars Regional lease.
Management emphasized disciplined investment decisions, a newly authorized share repurchase program and continued portfolio diversification while raising its full-year earnings outlook. However, tenant credit concerns and refinancing costs remain important considerations.
VICI Weighs $2 Billion Share Buyback Program
Chief executive officer Edward Pitoniak acknowledged investor dissatisfaction with the company's stock performance, identifying interest-rate pressures, constrained growth economics and Caesars lease uncertainty as principal concerns.
The company's new $2 billion share repurchase authorization provides another capital allocation option, although Pitoniak emphasized that repurchases would compete with investments offering attractive long-term returns.
During questioning from JPMorgan, chief financial officer David Kieske clarified that most retained cash flow is currently committed to existing loan investments. Potential buyback funding could instead come from future loan repayments, uncommitted cash flow or asset sales.
Caesars Lease Uncertainty Draws Greater Scrutiny
Pitoniak said management is evaluating alternative structures for the Caesars Regional lease to determine which approach maximizes shareholder value.
Responding to Truist Securities, he outlined options involving lease modifications, retaining existing properties or selling portions of the portfolio. Management did not establish a transaction timeline.
The issue also affected reported earnings. VICI recorded a $458 million noncash credit-loss allowance adjustment, including approximately $313 million attributable to Caesars. Kieske linked the accounting impact to Caesars' credit-rating downgrade and lease-duration assumptions.
VICI Raises 2026 AFFO Outlook
VICI increased its full-year 2026 adjusted funds from operations (AFFO) guidance to $2.695-$2.705 billion, compared with the previous $2.675-$2.695 billion range.
AFFO per share is now projected at $2.47-$2.48, up from $2.45-$2.47. Kieske expects approximately 4% annual AFFO-per-share growth at the updated midpoint.
Responding to Baird, Kieske attributed the revision to improved visibility into inflation-linked lease increases, loan funding commitments, variable interest rates and accelerated capital deployment.
Quarterly AFFO per share increased 4.3% to $0.62, matching the Zacks Consensus Estimate. Revenues reached $1.06 billion, in line with the Zacks Consensus Estimate and increasing 5.8% year over year.
VICI Properties Inc. Price, Consensus and EPS Surprise
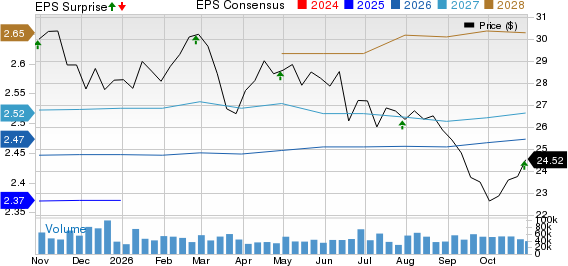
VICI Properties Inc. price-consensus-eps-surprise-chart | VICI Properties Inc. Quote
Portfolio Diversification Remains a Priority for VICI
President and chief operating officer John Payne highlighted VICI's agreement to add Highfield Investment Group as a tenant through Canadian gaming properties.
The transaction carries initial annual rent of C$10.7 million, offset by an equivalent reduction under the existing Century lease. Consequently, aggregate rental income remains unchanged.
Payne noted that the anticipated Highfield addition would bring four new tenants during 2026, alongside Clairvest, Golden Entertainment and Club Med.
Management also continues evaluating hospitality, sports, entertainment and wellness investments. However, Payne emphasized selective underwriting rather than pursuing acquisitions irrespective of financing conditions.
VICI Addresses Debt and Loan Portfolio Risks
Kieske highlighted the refinancing of $1.75 billion in 2026 maturities through unsecured notes carrying an adjusted weighted-average interest rate of 5.42%.
Quarter-end liquidity totaled approximately $2.5 billion, while net debt to annualized quarterly adjusted EBITDA stood near 4.8 times.
During questioning from Mizuho, Kieske acknowledged potential AFFO pressure from refinancing $1.5 billion of debt maturing in February 2027.
Separately, management discussed credit concerns within its loan portfolio. Gabe Wasserman, managing director of business development and VICI Experiential Credit Solutions, said the company continues to work with sponsors to address challenged investments, including a loan that was placed on nonaccrual status in late 2025.
VICI Maintains a Disciplined Capital Allocation Approach
Management's overarching message emphasized protecting financial flexibility while assessing opportunities across existing properties, new partnerships and potential capital recycling.
Pitoniak reiterated the company's preference for maintaining an AFFO payout ratio near 75%, preserving retained cash flow for investment and other corporate priorities.
The company's direction remains centered on portfolio quality, tenant diversification and measured capital deployment, with Caesars-related decisions and future financing conditions continuing to command attention.
Zacks Rank and Style Scores Signal Mixed Prospects
VICI currently carries a Zacks Rank #2 (Buy), indicating favorable near-term earnings estimate revision characteristics. Its Value Score of B highlights relatively attractive valuation characteristics under the Zacks Style Scores framework. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here .
However, Growth, Momentum and VGM Score of F indicate unfavorable characteristics across those categories. These weaker scores temper the favorable Rank and Value signals, particularly for investors emphasizing growth or price momentum.
The Zacks Rank can change as analysts revise their earnings estimates following the recently reported results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
VICI Properties Inc. (VICI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).