

Alphabet GOOGL shares plunged 12.64% on Thursday, following the release of third-quarter 2026 results, wiping out $482 billion in market capitalization. The selloff reflected concerns over slowing Google Search advertising growth, weaker monetization of AI-powered searches, mounting AI infrastructure expenditures, negative free cash flow and disappointing earnings. Although Alphabet delivered 25% year-over-year revenue growth and Google Cloud revenues more than doubled, investors questioned whether the company’s massive AI investments would generate sufficient returns to offset pressure on its core advertising business. Let’s dig deep to find out.
GOOGL Stock Suffers From Multiple Challenges
Google Search and other advertising revenues increased 12% year over year to $63.35 billion in the third quarter, decelerating from approximately 17% growth in the second quarter. The revenue figure also missed the Zacks Consensus Estimate by 2.53%. This slowdown was particularly concerning because Search remains Alphabet’s largest revenue contributor and provides significant cash flows to fund AI investments. GOOGL acknowledged that growing AI Mode usage contributed to Search revenue deceleration because AI Mode queries currently generate lower monetization than traditional searches.
Alphabet’s capital expenditures surged 114% year over year to $51.36 billion in the third quarter of 2026, exceeding operating cash flow of $42.29 billion. Consequently, free cash flow deteriorated to negative $9.07 billion from positive $24.46 billion a year earlier. Trailing 12-month free cash flow declined 73% year over year to $19.75 billion. Alphabet maintained its 2026 capital expenditure guidance of $195-$205 billion and expects spending to increase significantly in 2027.
Meanwhile, the company’s aggressive AI expansion is increasing its financial obligations. At the end of September 2026, GOOGL reported approximately $924 billion in future purchase commitments and $152 billion in pre-commencement leases and other obligations, representing more than $1 trillion in maximum contractual commitments. Alphabet cautioned that flexible pricing and volume terms could reduce actual spending. Long-term debt increased to $125.1 billion from $46.5 billion at the end of 2025. Alphabet also raised approximately $12.4 billion through common stock issuance during the third quarter and $28.7 billion through senior unsecured notes.
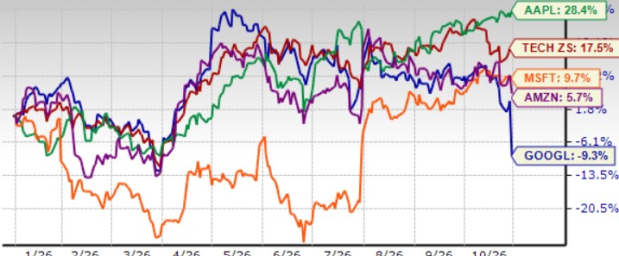
Apart from risks associated with the huge AI-related capital expenditure, Alphabet’s prospects suffer from intensifying competition from the likes of Microsoft MSFT, Amazon AMZN, OpenAI, Anthropic, Apple AAPL and Meta across its operational footprint. Year to date (YTD), Alphabet shares have dropped 9.3%, underperforming Apple’s 28.4%, Microsoft’s 9.7% and Amazon’s 5.7% returns.
GOOGL Stock’s Price Performance
Image Source: Zacks Investment Research
Alphabet is facing stiff competition in the cloud computing space from Microsoft and Amazon. Despite Google Cloud revenues increasing 103% year over year to $30.71 billion, investors remain concerned about the sustainability and profitability of this growth. TPU system sales contributed meaningfully to Cloud revenues. Alphabet also expects near-term Google Cloud margin headwinds as it expands the use of third-party compute capacity to address infrastructure constraints. Higher depreciation, energy expenses and data center operating costs are expected to weigh on profitability.
GOOGL Shares Are Overvalued
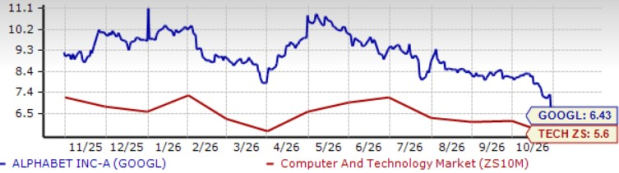
Alphabet shares are overvalued, as suggested by a Value Score of C.
GOOGL stock is trading at a forward 12-month price/sales (P/E) of 6.43X, a premium compared with the broader sector’s 5.60X and Amazon’s 2.82X.
However, Alphabet shares are trading at a discount compared with Microsoft and Apple, shares of which are trading at a P/S multiple of 9.50 and 9.69, respectively.
GOOGL Stock’s Valuation
Image Source: Zacks Investment Research
GOOGL’s Prospects Ride on Cloud & AI Initiatives
Alphabet’s Google Cloud business remains a significant long-term growth driver, supported by accelerating enterprise investments in AI infrastructure, cloud modernization and agentic AI applications. Google Cloud’s backlog reached $561 billion, with Alphabet expecting to recognize slightly more than 55% of the backlog as revenue over the next 24 months. Strong enterprise demand for AI infrastructure, core GCP services, Gemini Enterprise, BigQuery and cybersecurity solutions strengthens Alphabet’s long-term revenue visibility.
Alphabet’s expanding Gemini ecosystem is a key long-term growth catalyst. The Gemini app surpassed one billion users, while first-party model APIs processed nearly 32 billion tokens per minute, up 40% sequentially and more than fourfold year over year. The introduction of Gemini 4 Argon and Carbon strengthens Alphabet’s positioning in advanced reasoning, coding, cybersecurity and enterprise automation. The integration of Gemini across Search, Chrome, Android, Workspace and Google Cloud provides multiple opportunities to monetize AI through advertising, subscriptions, enterprise software and developer services.
Despite near-term monetization challenges, Alphabet’s growing AI Search engagement presents a significant long-term opportunity. The company reported its fastest year-over-year Search query growth in five years, while AI Mode queries averaged three times the length of traditional searches. Alphabet is expanding advertising within AI Overviews and AI Mode, including international availability and multiturn ads. AI Max and Performance Max are also strengthening advertiser capabilities through improved targeting, automated campaign optimization and AI-generated creative assets.
However, the transition from traditional search results to AI-generated responses presents a structural challenge to Alphabet’s largest revenue-generating business. Competition from OpenAI’s ChatGPT, Anthropic’s Claude and other AI-powered discovery platforms could further disrupt traditional search behavior. This doesn’t bode well for GOOGL’s prospects.
2026 Earnings Estimate Revisions Positive for GOOGL Stock
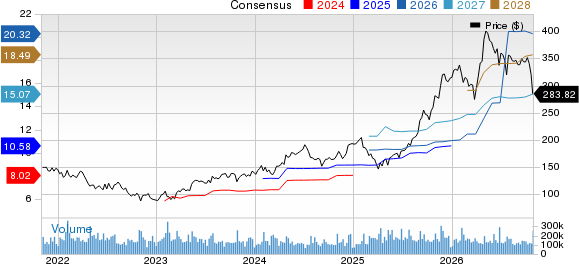
The Zacks Consensus Estimate for 2026 earnings is pegged at $20.60 per share, up by a nickel over the past 30 days, indicating 90.6% growth from the figure reported in 2025.
Alphabet Inc. Price and Consensus
Alphabet Inc. price-consensus-chart | Alphabet Inc. Quote
The consensus mark for fourth-quarter 2026 earnings is pegged at $3.25 per share, up by a penny over the past 30 days, suggesting 15.3% year-over-year growth.
Conclusion
Alphabet’s sharp post-earnings decline reflects growing concerns over slowing Search advertising growth, lower monetization of AI-powered queries and mounting infrastructure investments that are pressuring free cash flow. Although robust Google Cloud growth, expanding TPU adoption, Gemini innovation and a substantial backlog support long-term growth prospects, GOOGL’s aggressive capital spending, rising financing requirements and uncertain AI monetization economics warrant caution. Investors should closely monitor improvements in Search monetization, Cloud profitability and free cash flow before becoming more constructive on GOOGL stock.
Alphabet currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Alphabet Inc. (GOOGL): Free Stock Analysis Report
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
Apple Inc. (AAPL): Free Stock Analysis Report
Microsoft Corporation (MSFT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).