

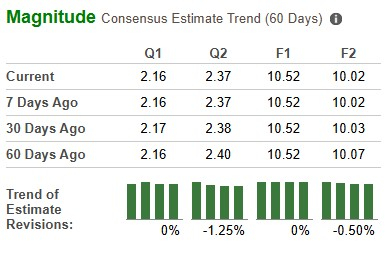
Qualcomm Incorporated QCOM is scheduled to report fourth-quarter fiscal 2026 earnings after the closing bell on Nov. 4. The Zacks Consensus Estimate for sales and earnings is pegged at $10.15 billion and $2.16 per share, respectively. Earnings estimates for QCOM for fiscal 2026 have remained unchanged over the past 60 days, and those for fiscal 2027 have decreased 0.5% to $10.02.
QCOM Estimate Trend
Image Source: Zacks Investment Research
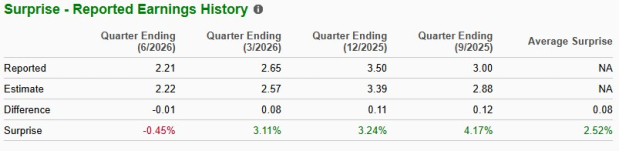
Earnings Surprise History
The chip manufacturer delivered a trailing four-quarter earnings surprise of 2.5%, on average, beating estimates on three occasion. In the last reported quarter, the company delivered a negative earnings surprise of 0.45%.
Image Source: Zacks Investment Research
Earnings Whispers
Our proven model does not conclusively predict an earnings beat for Qualcomm for the fiscal third quarter. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. That is not the case here. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Qualcomm currently has an ESP of -0.51% and a Zacks Rank #4 (Sell). You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Shaping Upcoming Results
During the quarter, Qualcomm completed the acquisition of Modular, adding an AI-native software platform designed to optimize and deploy generative and agentic AI workloads across CPUs, GPUs, NPUs and custom silicon. The transaction expands Qualcomm’s software capabilities across devices, edge infrastructure and data centers.
The company introduced the Dragonwing Q-2390 and IQ-2390 processors to broaden access to edge AI across consumer, commercial and industrial devices. The platforms integrate AI, vision, connectivity and real-time processing, with customer engagement underway and evaluation kits expected in early 2027. It has also announced a multi-generational collaboration with Amazon to develop customized silicon for AI inference and advanced optical connectivity for AWS data centers. Despite these positive developments, Qualcomm’s prospects are impacted by several factors.
Memory pricing, supply constraints and OEM builds continue to weigh on the smartphone business. The semiconductor supply chain is operating near full utilization, with shortages and cost increases across wafers, assembly, test, advanced packaging, memory and other materials. Qualcomm is responding with broad price increases that management described as double-digit, but contract terms and product cycles mean the benefit will phase in over the next couple of quarters.
Price Performance
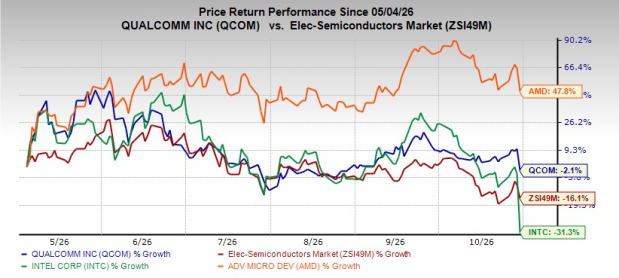
Over the past year, Qualcomm has declined 2.1% compared with the industry’s decline of 16.1%, outperforming competitors like Intel Corporation INTC but underperforming Advanced Micro Devices AMD. While AMD has gained 47.8%, Intel has declined 31.3% over the said time frame.
Image Source: Zacks Investment Research
Key Valuation Metric
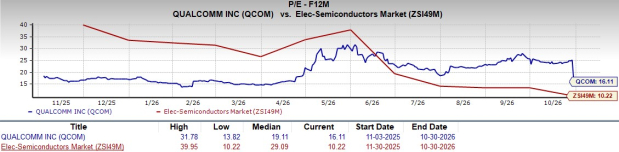
From a valuation standpoint, Qualcomm appears to be relatively premium compared to the industry and below its mean. Going by the price/earnings ratio, the company’s shares currently trade at 16.11 forward earnings, higher than 10.22 for the industry but lower than the stock’s mean of 19.11.
Image Source: Zacks Investment Research
Investment Consideration
Qualcomm's increasing exposure to automotive, IoT and data center markets offers opportunities to diversify its revenue base. These initiatives may not be enough to offset the challenges facing its core handset business in the near term. Persistent weakness in the Android smartphone market, rising memory costs and lower expected contributions from Apple could continue to weigh on QCT revenues. Moreover, the company's dependence on a limited number of major customers exposes it to demand fluctuations and potential revenue losses as manufacturers increasingly explore in-house chip development.
Profitability also remains a concern. Higher costs across wafer fabrication, assembly, testing and advanced packaging have already weakened QCT margins, while the benefits of product price increases are likely to take time to materialize.
Moreover, Qualcomm's expansion into data center infrastructure involves considerable execution risks. Its ambitious revenue targets will require successful product development, timely commercialization and sustained customer adoption.
End Note
Qualcomm's efforts to establish a stronger presence in automotive, IoT and AI computing markets have expanded its long-term growth opportunities. However, the company's dependence on the smartphone market, declining Apple-related revenues and industry-wide supply constraints continue to create significant challenges. The pressure on QCT margins, combined with higher operating expenses and the uncertain profitability of its emerging data center business, raises concerns about the sustainability of earnings growth. The company carries a Zacks Rank #4. Investors should avoid investing in this stock at present.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
QUALCOMM Incorporated (QCOM): Free Stock Analysis Report
Intel Corporation (INTC): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).