

ACM Research ACMR is scheduled to report third-quarter 2026 results on Nov. 5, before the market opens.
The Zacks Consensus Estimate for ACM Research’s third-quarter 2026 earnings is pegged at 51 cents per share, implying a year-over-year increase of 41.7%. The consensus mark for earnings has remained unchanged over the past 60 days.
ACM Research’s earnings surpassed the Zacks Consensus Estimate in two of the trailing four quarters while missing twice, the average surprise being 39.1%.
Let’s see how things are shaping up for the upcoming announcement.
ACM Research, Inc. Price and EPS Surprise
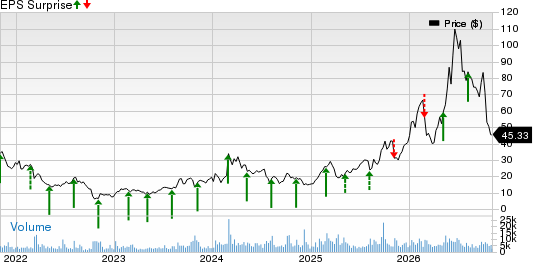
ACM Research, Inc. price-eps-surprise | ACM Research, Inc. Quote
Factors Likely to Have Influenced ACMR’s Q3 Results
ACM Research's third-quarter performance is expected to have benefited from strong demand for its electrochemical plating (ECP) products. Demand for these tools is being driven by investments in high-bandwidth memory, advanced packaging and 2.5D chip packaging. In the second quarter of 2026, revenues from ECP, furnace and other technologies increased 168% year over year to $128.5 million. Continued demand for copper plating tools is likely to have supported third-quarter growth.
Strong demand for advanced packaging equipment is also likely to aid third-quarter results. Second-quarter revenues from advanced packaging, excluding ECP, increased 153% year over year. ACM Research is seeing demand for coaters, developers, wet etchers, strippers and cleaning tools used in advanced packaging. The company is gaining traction with its panel-level horizontal plating platform and expects customer evaluations to support future production orders.
However, higher operating expenses are likely to have limited earnings growth. ACM Research expects research & development (R&D) expenses to account for 16-18% of revenues in 2026 compared with 14.4% in the second quarter, as the company continues to invest in new products. In the second quarter of 2026, operating expenses increased 16.6%, reflecting continued investments in R&D, sales and global expansion.
Gross margin declined year over year to 46% from 48.7% in the year-ago quarter. Management specifically noted that product mix can cause quarterly fluctuations, meaning rapid growth in newer product categories may not translate directly into stable margin expansion. These factors could have hurt the company’s prospects in the to-be-reported quarter.
Q3 Earnings Whispers for ACM Research
Our proven model does not conclusively predict an earnings beat for ACMR this season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat, which is not the case here.
Though ACM Research currently carries a Zacks Rank #3, it has an Earnings ESP of 0.00%. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Stocks to Consider
Here are a few companies worth considering in the broader Zacks Computer and Technology sector, as our model indicates that these possess the right combination of factors to exceed earnings expectations in their upcoming releases.
Microchip Technology Incorporated MCHP has an Earnings ESP of +3.31% and currently carries a Zacks Rank #2. Microchip is set to report second-quarter fiscal 2027 results on Nov. 5. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Microchip’s second-quarter earnings is pegged at 94 cents per share, up by a penny over the past 30 days. The consensus mark for earnings indicates a year-over-year increase of 168.6%.
NVIDIA Corporation NVDA has an Earnings ESP of +3.46% and a Zacks Rank #2 at present. NVIDIA is slated to report third-quarter fiscal 2027 results on Nov. 17.
The Zacks Consensus Estimate for NVIDIA’s third-quarter earnings is pegged at $2.49 per share, up by a penny over the past 30 days. The consensus mark for earnings calls for a year-over-year jump of 91.5%.
Hewlett Packard Enterprise Company HPE has an Earnings ESP of +2.64% and a Zacks Rank #2 at present. Hewlett Packard Enterprise is slated to report fourth-quarter fiscal 2026 results on Nov. 23.
The Zacks Consensus Estimate for Hewlett Packard Enterprise’s fourth-quarter earnings is pegged at $1.28 per share, revised upward by a penny over the past seven days. The consensus mark for earnings suggests a year-over-year surge of 106.5.% from the year-ago quarter’s reported figure.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ACM Research, Inc. (ACMR): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Microchip Technology Incorporated (MCHP): Free Stock Analysis Report
Hewlett Packard Enterprise Company (HPE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).