

Innodata Inc. INOD reported strong third-quarter 2026 results with adjusted earnings per share (EPS) and revenues topping the Zacks Consensus Estimate and growing year over year.
The quarterly performance was mainly driven by higher volumes from existing AI data engineering programs. Five new programs with a major hyperscaler were added to INOD’s AI customer pipeline.
INOD stock surged 8.8% during yesterday’s after-market trading session.
In September 2026, Innodata launched a motion capture lab for humanoid robot and world-model training. The company is running pilots with frontier AI and robotics laboratories. Management estimates that one successful pilot could yield approximately $7 million in revenues in 2027.
INOD’s Q3 Highlights
Innodata reported quarterly adjusted earnings of 29 cents per share, which topped the Zacks Consensus Estimate of 21 cents by 38.1% and increased 20.8% from 24 cents a year earlier.
Revenues climbed 53% year over year to $95.6 million, exceeding the consensus mark of $85 million by 12.9%. This marked the company's 13th consecutive quarter of year-over-year revenue growth.
Innodata Inc Price, Consensus and EPS Surprise
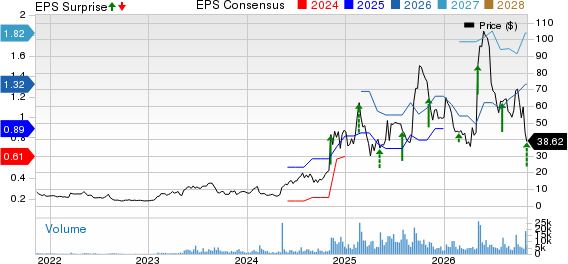
Innodata Inc price-consensus-eps-surprise-chart | Innodata Inc Quote
Sales to U.S. customers rose to $85.1 million from $52.8 million in the year-ago quarter, accounting for approximately 89% of total revenues.
Innodata's Costs Outpace Top-Line Expansion
Direct operating costs increased 62.2% to $60.1 million from $37 million a year earlier. Higher content acquisition expenses for AI-enabled projects accounted for about $21 million of the increase. Cloud services and AI-related subscription costs added approximately $1.5 million.
Gross profit rose to $35.5 million from $25.5 million, but gross margin contracted to 37% from 41%. Adjusted gross profit increased 38.5% to $38.3 million, while adjusted gross margin narrowed to 40% from 44%. Adjusted EBITDA rose 9.3% to $17.7 million from $16.2 million, although its margin fell year over year to 18.5% from 25.9%.
Selling and administrative expenses surged 95.6% to $26.9 million amid spending on personnel, software and customer acquisition. Operating income consequently declined to $8.7 million from $11.8 million.
INOD Lands New AI Programs and Clients
The company signed an additional fourth-quarter program valued at approximately $18 million with its largest customer. Separately, Innodata forecasts more than $20 million in 2027 revenues from a hyperscaler account that generated about $3.1 million over the trailing 12 months.
It also added five new customer logos in the third quarter, including AI model builders and an enterprise data platform. New enterprise AI relationships include a global technology hardware company and a major financial services firm.
In its federal business, Innodata secured a verbal win for a proposed five-year contract worth $5 million annually. Management expects to sign the agreement before the fourth quarter ends.
Innodata's Cash Generation Strengthens
Cash and equivalents reached $164 million as of Sept. 30, 2026, up from $82.2 million at 2025-end. Excluding customer prepayments related to pass-through costs, cash was approximately $153.7 million. Working capital increased to $151.1 million from $84.9 million.
Net cash from operating activities for the first nine months of 2026 rose to $80.5 million from $33.7 million a year earlier. Capital expenditures declined to $7.7 million from $8.3 million, while long-term obligations, excluding the current portion, were $8.9 million compared with $7.6 million at 2025-end.
INOD Raises 2026 Revenue Growth Outlook
Innodata raised its full-year 2026 revenue growth forecast to at least 42% from its previous projection of at least 40%. The higher outlook follows the expansion of its AI program pipeline and new customer relationships.
The revised forecast incorporates the wind-down of a program at a large customer. Management expects new programs to replace that work in the first quarter of 2027. CEO Rahul Singhal highlighted AI agents, reinforcement learning and embodied intelligence as areas of future opportunity.
INOD’s Zacks Rank & Recent Construction Releases
Innodata currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Martin Marietta Materials, Inc. MLM reported better-than-expected third-quarter 2026 results, with adjusted earnings (from continuing operations) and revenues topping the Zacks Consensus Estimate. Year over year, the bottom line declined while the top line increased. Recent acquisitions fueled record volumes, with aggregates shipments up 15.9% to 67.1 million tons. Strong Specialties contributions helped offset softer organic aggregates demand, acquisition-related pricing mix and rising energy costs.
Martin Marietta updated its full-year 2026 revenue guidance to $7.75-$7.85 billion, with adjusted EBITDA from continuing operations projected at $2.45-$2.5 billion. Management forecasts 12.5-13.5% aggregates volume growth for 2026, alongside a 2-3% decline in average selling prices. For 2027, it anticipates mid- to high-single-digit gains in mix-adjusted aggregates pricing, supported by planned Jan. 1 pricing actions.
CRH plc CRH reported lower-than-expected third-quarter 2026 results, with adjusted earnings and total revenues missing the Zacks Consensus Estimate. Year over year, the bottom line declined while the top line grew. Positive pricing and acquisitions supported sales despite the softer housing market and rising input costs. CRH completed nine acquisitions for $500 million during the third quarter.
CRH cut its full-year net income forecast to $3.1-$3.3 billion from $3.9-$4.1 billion and adjusted EBITDA guidance to $7.8-$8.0 billion from $8.1-$8.5 billion. Management introduced adjusted earnings guidance of $5.37-$5.59 per share and reduced its capital expenditure forecast to $2.6-$2.8 billion from $2.7-$2.9 billion. Looking to 2027, CRH expects infrastructure and reindustrialization activity to support demand despite continued near-term residential weakness.
MasTec, Inc. MTZ reported strong third-quarter 2026 results, with adjusted earnings and revenues surpassing the Zacks Consensus Estimate and increasing on a year-over-year basis. Its quarterly performance benefited from robust Power Delivery growth, supported by strong execution across legacy operations and contributions from the Superior Group acquisition.
Record backlog highlighted strong project opportunities and provided improved revenue visibility heading into 2027. However, MasTec faced operational challenges, including pipeline project delays that affected crew and equipment utilization. For 2026, MasTec now anticipates revenues of $18.3 billion, up from its previous expectation of approximately $18.2 billion, with adjusted earnings now expected to be $8.92-$9.30 per share, compared with the previous projection of $9.30 per share.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Innodata Inc (INOD): Free Stock Analysis Report
Martin Marietta Materials, Inc. (MLM): Free Stock Analysis Report
MasTec, Inc. (MTZ): Free Stock Analysis Report
CRH PLC (CRH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).