

Flowers Foods, Inc. FLO is likely to witness a top- and bottom-line decline when it reports third-quarter fiscal 2026 earnings on Nov. 12. The Zacks Consensus Estimate for revenues is pegged at $1.2 billion, indicating a fall of 3.1% from the year-ago reported figure.
The consensus mark for earnings has remained unchanged over the past 30 days at 15 cents a share, suggesting a decrease of 34.8% from the year-ago period’s figure. FLO has a trailing four-quarter surprise of 8.1%, on average.
Flowers Foods, Inc. Price, Consensus and EPS Surprise
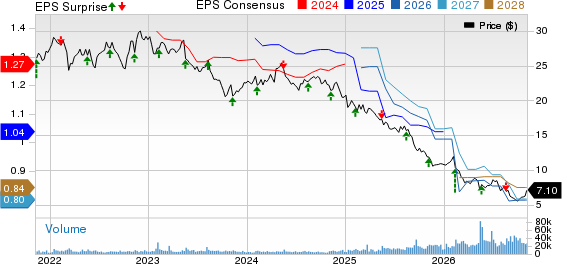
Flowers Foods, Inc. price-consensus-eps-surprise-chart | Flowers Foods, Inc. Quote
Factors Likely to Influence FLO’s Upcoming Results
Flowers Foods’ third-quarter results are likely to be pressured by persistent weakness in the fresh packaged bread category. Strained household budgets, increased price sensitivity and consumer trade-down toward lower-priced alternatives may have weighed on demand. Management expects year-over-year sales declines in the quarter, reflecting pricing and volume pressures.
Heightened competition and promotional activity could have further affected branded retail performance. Shifting consumer preferences toward smaller loaves, sourdough and functional bread varieties, where Flowers Foods remains underpenetrated, may have constrained volumes. Continued weakness in traditional loaf and competitive pressures on Dave’s Killer Bread could have compounded these challenges.
Lower production volumes are likely to have restricted operating leverage, while elevated labor, freight and marketing expenses could have pressured margins. Continued brand investments and promotional intensity may have limited profitability, although productivity improvements and cost-saving initiatives are likely to have provided some relief.
On the positive side, Flowers Foods may have benefited from new business wins across retail and away-from-home channels, with some contributions expected in the third quarter. The Nature’s Own relaunch, innovation and expanded distribution are likely to have supported performance, although benefits remain in the early stages. Continued momentum at Simple Mills and strength in select specialty bakery categories may have partly offset broader weakness.
Earnings Whispers for FLO
Our proven model doesn’t conclusively predict an earnings beat for Flowers Foods this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
Flowers Foods currently carries a Zacks Rank #5 (Strong Sell) and has an Earnings ESP of 0.00%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks With the Favorable Combination
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
Dollar General Corporation DG currently has an Earnings ESP of +8.66% and a Zacks Rank of 2. The consensus estimate for quarterly revenues stands at $11.1 billion, which suggests 4.5% growth from the figure reported in the prior-year quarter. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Dollar General’s upcoming quarter’s EPS is pegged at $1.40, which calls for a 9.4% increase from the year-ago period’s figure. DG delivered a trailing four-quarter earnings surprise of 19.1%, on average.
Ulta Beauty, Inc. ULTA currently has an Earnings ESP of +1.84% and a Zacks Rank #2. The consensus estimate for quarterly revenues is pegged at nearly $3 billion, which indicates 4.5% growth from the figure reported in the prior-year quarter.
The Zacks Consensus Estimate for Ulta Beauty’s upcoming quarter’s EPS is pegged at $5.60, which calls for almost 9% growth from the figure reported in the prior-year quarter. ULTA delivered a trailing four-quarter earnings surprise of 7.6%, on average.
The Kroger Co. KR currently has an Earnings ESP of +3.43% and a Zacks Rank of 3. The Zacks Consensus Estimate for KR’s upcoming quarter’s revenues is pegged at $34.6 billion, suggesting a 2.1% jump from the figure reported in the prior-year quarter.
The consensus estimate for Kroger’s upcoming quarter’s EPS is pegged at $1.16 per share, implying 10.5% growth from the year-ago quarter’s earnings of 36 cents. KR delivered a trailing four-quarter earnings surprise of 2.7%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Flowers Foods, Inc. (FLO): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
The Kroger Co. (KR): Free Stock Analysis Report
Ulta Beauty Inc. (ULTA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).