

SoundHound AI, Inc. SOUN is delivering rapid revenue growth as enterprise adoption expands across voice and agentic AI. Third-quarter revenues rose 48.5% year over year to $62.4 million, extending the company’s push into larger enterprise deployments.
The investment question is whether that scale can translate into durable profitability soon enough. Persistent operating losses, negative cash flow and a valuation above broader market benchmarks leave investors weighing execution against a sizable growth opportunity.
SOUN's Revenue Growth Supports the Bull Case
SoundHound generated $168.9 million in 2025 revenues, up 99% from 2024. Management now expects $250 million-$260 million in 2026 revenues and $350 million-$400 million in 2027, reflecting continued enterprise demand and contributions from the expanded business.
OASYS is broadening the company’s addressable use cases across customer service, health care, restaurants, automotive and connected devices. Cerence Inc. CRNC, which develops conversational AI for automotive and other intelligent systems, underscores the competitive intensity around voice-based AI as SoundHound tries to convert technical differentiation into recurring enterprise growth.
SoundHound AI, Inc. Price and EPS Surprise
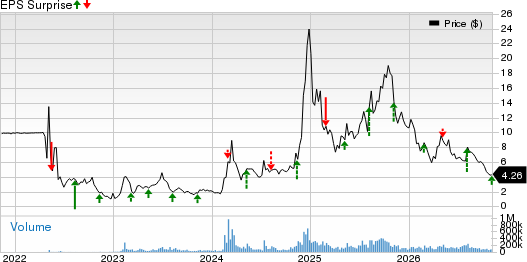
SoundHound AI, Inc. price-eps-surprise | SoundHound AI, Inc. Quote
SoundHound's Valuation Demands More Proof
SOUN trades at 5.1X forward 12-month sales, below the industry’s 11.7X multiple. That discount may look attractive at first glance, but it does not make the shares inexpensive on an absolute basis.
The stock still trades above the sector’s 4.8X and the S&P 500’s 4.3X sales multiples. With earnings and operating cash flow still negative, investors are paying for future scale and margin improvement rather than established profitability, leaving little room for execution setbacks.
SOUN's Cash Burn Clouds the Profitability Path
Operating losses widened to $112.5 million during the first nine months of 2026 from $65.8 million a year earlier. Net cash used in operating activities also increased to roughly $96 million from $76.3 million.
SoundHound had $207.6 million in cash and cash equivalents at Sept. 30, 2026, providing liquidity to fund its transition. Still, continued cash consumption raises financing and dilution risks if cost reductions, margin improvement or customer conversions take longer than expected.
LivePerson Could Expand SoundHound's Upside
The LivePerson acquisition adds digital messaging, enterprise relationships and integrations to SoundHound’s voice and agentic AI platform. Management has engaged LivePerson’s top 90 enterprise accounts, representing more than $100 million in annual recurring revenue, while nearly 20 OASYS enterprise implementations are underway.
SoundHound has identified at least $120 million in annualized cost reductions, with the full run rate expected during 2027. Five9, Inc. FIVN, whose customer-experience platform combines AI, voice and digital channels, highlights the competitive field SoundHound faces as it pursues cross-selling and operating leverage from the combined platform.
Why SOUN's Mixed Signals Favor Patience
SoundHound’s growth outlook is attractive, but the stock still requires evidence that expanding revenues can produce sustainable earnings and cash generation. Management targets sustained positive adjusted EBITDA in the second half of 2027, even at the low end of its revenue guidance, making execution over the next several quarters critical.
SOUN currently carries a Zacks Rank #3 (Hold). Its Momentum Score of B is favorable, but the Value Score of F, Growth Score of F and VGM Score of F are weak. That combination supports a wait-and-see stance until profitability, cash conversion and valuation offer a more convincing risk-reward balance. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
SoundHound AI, Inc. (SOUN): Free Stock Analysis Report
Five9, Inc. (FIVN): Free Stock Analysis Report
Cerence Inc. (CRNC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).