

Onto Innovation Inc. ONTO is delivering faster earnings growth, broader AI-related demand and improving profitability. The question is whether those gains are sufficient to offset a valuation that remains above its own historical norm.
Backlog, estimate growth and margin expansion support the bull case. Still, capital returns have softened, acquired businesses add execution demands and the stock’s valuation leaves less room for disappointment.
ONTO’s Earnings Growth Has Accelerated Sharply
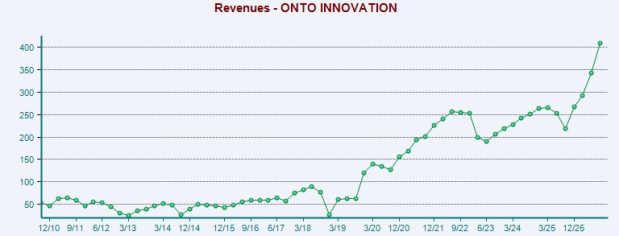
Third-quarter revenues rose 87.8% year over year to a record $409.7 million. Non-GAAP operating income increased 189.8% to $133.5 million, while non-GAAP earnings reached $2.44 per share, up 165.2%.
Image Source: Zacks Investment Research
The earnings outlook remains constructive. The Zacks Consensus Estimate calls for 2026 earnings of $8.25 per share and 2027 earnings of $12.44, implying a 50.8% increase next year. The estimate for 2026 earnings has also moved 2.7% higher over the past four weeks.
Onto’s AI Exposure Is Broadening Across Products
Dragonfly G5 adoption has expanded to more than 10 customers across high-bandwidth memory and 2.5D packaging. Purchase orders already received for 2027 represent twice the platform’s expected 2026 revenues, while Atlas G6 is gaining traction across logic and memory applications.
Advanced-packaging revenues are expected to rise more than 80% in 2026, with management anticipating growth of more than 35% in 2027. Camtek Ltd. CAMT, another inspection and metrology supplier, reported record third-quarter 2026 revenues of $161.3 million and expects 2027 revenues to exceed $800 million, reflecting continued demand in advanced semiconductor packaging.
ONTO’s Margin Expansion Strengthens the Bull Case
Non-GAAP gross margin improved to 57.6% in the third quarter from 54% a year earlier. Non-GAAP operating margin reached 32.6%, compared with 21.1% in the prior-year quarter.
Management expects fourth-quarter non-GAAP gross margin of 57.7%-58.3% and sees further improvement in 2027. The extended-factory model, regionalized supply chains and productivity measures support an expectation for roughly 50 basis points of gross-margin expansion per quarter over the next several quarters.
Onto’s Valuation and Capital Returns Temper the Upside
ONTO trades at 8.2X trailing 12-month enterprise value-to-sales, above its five-year median of 6.0X and the Zacks Computer and Technology sector’s 7.8X. That premium places more weight on continued revenue growth and margin execution.
Trailing 12-month return on invested capital is 9.7%, below the company’s 10-year median of 11.8%. The $720 million Rigaku investment expanded the capital base, while Semilab USA posted a $2.8 million operating loss in the third quarter. KLA Corporation KLAC, a larger process-control competitor, reported $4.14 billion in fiscal first-quarter 2027 revenues, underscoring the scale and competitive intensity of the market.
ONTO’s Ranking Mix Favors Selectivity Over Chasing
The setup favors selectivity rather than treating earnings momentum as an automatic buy signal. ONTO’s growth visibility and margin profile are improving, but the valuation premium and lower capital returns argue for discipline on entry price.
ONTO currently carries a Zacks Rank #2 (Buy). Its Momentum Score of B is supportive, while the Value Score of D, Growth Score of C and VGM Score of C show a less uniform style profile. The mix points to favorable near-term earnings-revision momentum, but investors focused on value or broader style strength may prefer to wait for a more balanced risk-reward setup. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Onto Innovation Inc. (ONTO): Free Stock Analysis Report
KLA Corporation (KLAC): Free Stock Analysis Report
Camtek Ltd. (CAMT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).