

Nvidia (NVDA) has been powering the ongoing artificial intelligence (AI) boom. Its graphics processing units (GPUs), central processing units (CPUs), networking products, and increasingly integrated AI systems continue to benefit from enormous investments in data center infrastructure. As a result, NVDA has continued to deliver impressive financial results.
Notably, concerns about a potential slowdown in AI development have weighed on semiconductor stocks, raising fears that the enormous spending on AI infrastructure could eventually moderate. However, demand for Nvidia’s products is unlikely to slow, and the company could continue delivering extraordinary growth.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
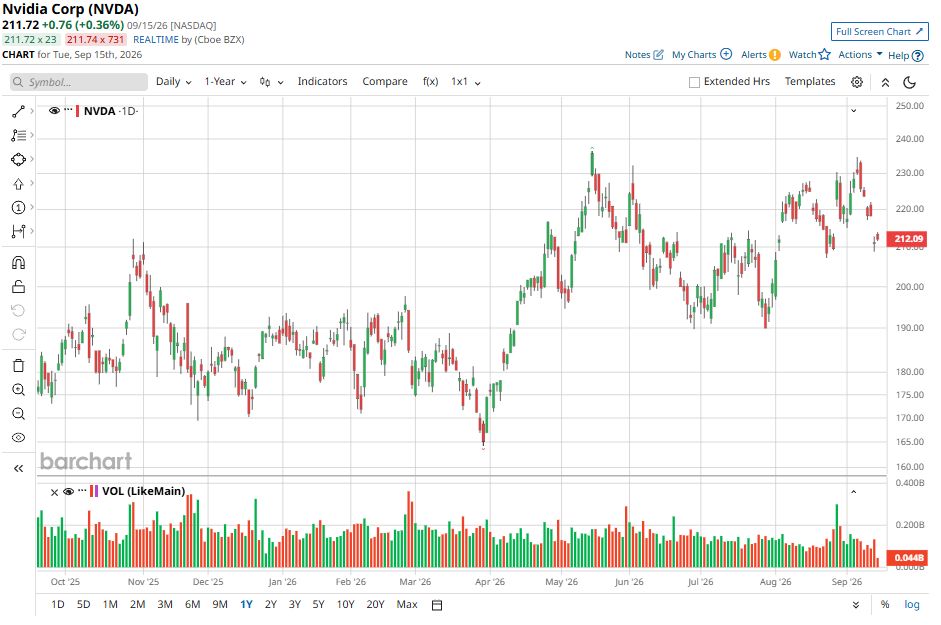
However, Nvidia’s operational strength hasn't fully trickled into its stock performance. NVDA stock has underperformed relative to rivals like AMD (AMD) and Intel (INTC). Its valuation also remains compelling relative to peers and its growth trajectory, supporting the bull case.
 www.barchart.com
Soaring Earnings
Nvidia’s growth trajectory remains compelling, with expectations for substantial increases in both revenue and earnings over the coming years. The continued expansion of AI infrastructure and its expanding portfolio of computing platforms gives it a solid base for future growth.
Nvidia’s top-line growth has been accelerating. In the first quarter of fiscal 2027, The company's revenue climbed 85% year-over-year (YoY). Further, in the second quarter, its top line hit $96.2 billion. That was a 106% increase YoY.
Nvidia expects third-quarter revenue to reach $108 billion. Even at that level, the company would grow revenue by more than 89% compared with the same period a year earlier. Given solid demand from diversified end markets, Nvidia could outperform its forecast, and its growth could accelerate again.
The demand is coming not only from major cloud providers but also from AI-focused companies, traditional enterprises, and governments investing in sovereign AI capabilities. Based on the company’s outlook, revenue could increase by 70% in fiscal 2028.
Nvidia’s data center operations are positioned to remain a major contributor, particularly as customers continue adopting the Blackwell architecture. At the same time, Nvidia’s full-stack approach to AI computing allows it to participate across the infrastructure ecosystem. Nvidia has also started shipping systems based on its next-generation Vera Rubin architecture, providing another potential source of growth.
Another solid opportunity is the CPU market, particularly as agentic AI applications require more computing resources. Nvidia’s Grace CPU business has already surpassed $5 billion in trailing twelve-month revenue, while Nvidia estimates that the total annual server CPU market is worth approximately $20 billion. The company expects its CPU revenue to more than double in fiscal 2028.
Nvidia’s rapid revenue expansion should translate into significant earnings growth. Current analyst estimates call for Nvidia’s earnings to double in fiscal 2027, followed by earnings growth exceeding 68% in fiscal 2028. With solid demand, Nvidia could also exceed analysts’ expectations.
Nvidia’s Valuation Indicates Further Upside
Nvidia’s business continues to show solid momentum, with both revenue and profits expected to grow strongly. Despite that, NVDA stock appears undervalued. Nvidia currently trades at about 23.9 times forward earnings, which is low given its strong earnings growth potential.
Nvidia’s valuation looks even more compelling when compared with peers. AMD, for example, trades at 80.3 times forward earnings, while Intel’s forward P/E ratio is around 99 times. That puts Nvidia at a significant discount to both companies, despite its leadership in the AI infrastructure space.
It’s Time to Load Up on NVDA Stock
Nvidia’s accelerating revenue, exceptional earnings growth potential, expanding AI infrastructure demand, and a growing presence across GPUs, CPUs, networking, and full-stack AI systems make it a compelling investment.
While concerns over an AI spending slowdown persist, Nvidia’s fundamentals still point to solid growth ahead. In addition, NVDA stock trades at a substantially lower forward earnings multiple than AMD and Intel, despite delivering stronger growth and maintaining a dominant position in AI computing.
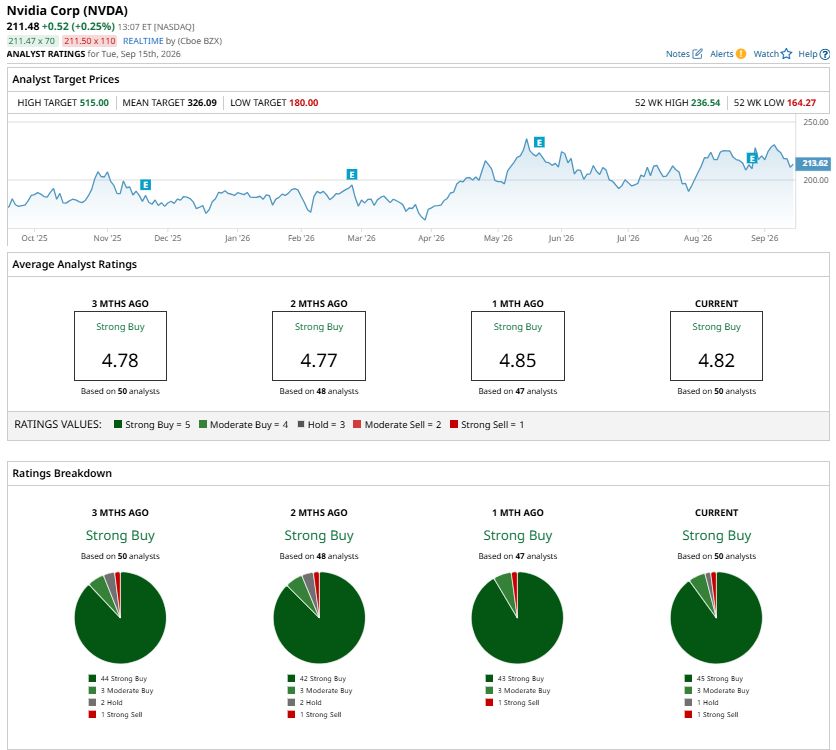
Wall Street remains optimistic as well. Analysts currently give NVDA stock a consensus rating of “Strong Buy.” With an average price target of $326.09, analysts project about 54% upside from the stock’s current price.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
A $10 Trillion Reason Why SpaceX Stock Is Up Today Why It’s Time to Load Up on Nvidia Stock This Dividend Stock Is Staging a Turnaround in 2026 and Pays More Than 2.4% Here Is How to Play Corning Stock After Its Dilution Scare