

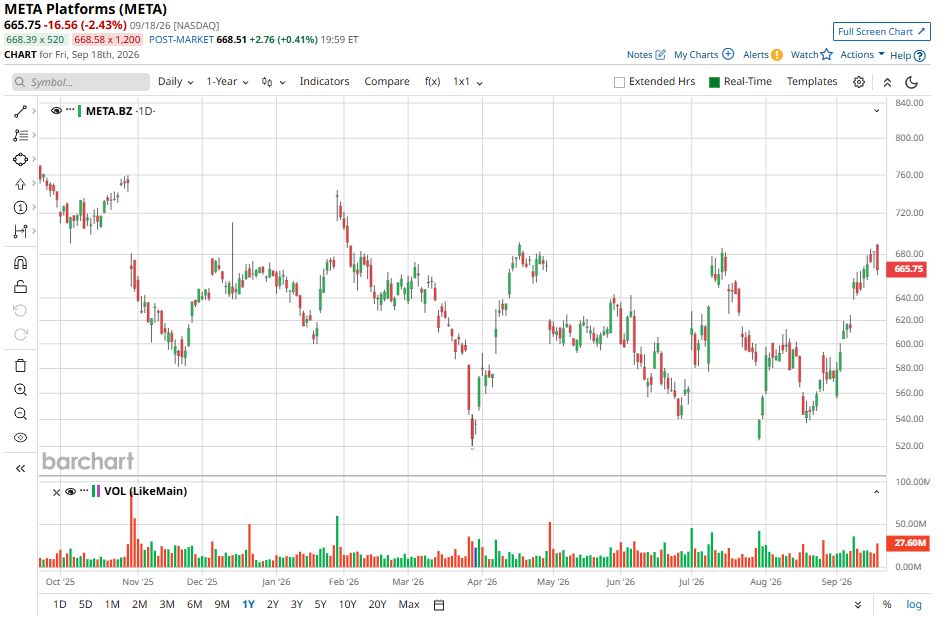
Meta Platforms (META) stock has underperformed the broader equity market so far in 2026. The stock’s underperformance reflects investor concern about the social media giant’s increasing capital expenditure on artificial intelligence (AI).
Meta’s substantial AI-related investments have pushed capital expenditures higher. In the second quarter, the company reported $31.1 billion in capital expenditures, including principal payments associated with finance leases. Much of this spending was directed toward servers, data centers, and network infrastructure needed to expand its AI capabilities. While these investments could strengthen Meta’s long-term competitive position, investors remain focused on how quickly they can generate meaningful financial returns.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The company’s third-quarter revenue guidance also contributed to the cautious sentiment. Although Meta posted strong revenue growth in the second quarter, its outlook for Q3 fell short of Wall Street expectations. The company projected revenue between $61 billion and $64 billion, implying a midpoint of $62.5 billion.
Still, Meta’s investment case remains solid. The company’s core advertising business remains resilient, generating the cash flow needed to finance its substantial investments in infrastructure and technology. Importantly, AI is also beginning to show benefits across Meta’s platforms, including higher user engagement and more effective ad targeting.
 www.barchart.com
Meta Positioned for Strong Growth Ahead
Meta is well positioned for solid growth ahead, with its investments in AI increasingly contributing to the performance of its core social media platforms. In the second quarter, time spent on Instagram rose at a double-digit year-over-year (YoY) rate, driven largely by improvements in Feed and Reels recommendations. Facebook also recorded stronger video engagement, with worldwide video watch time rising 9% and growing by more than 10% in the U.S. and Canada.
Higher engagement is particularly valuable for Meta because it supports the company’s advertising business. At the same time, AI-powered targeting is helping advertisers reach more relevant audiences, potentially improving conversion rates and increasing the value of individual ad impressions.
AI is also strengthening Meta’s advertising monetization strategy. The company’s Advantage+ suite of AI-based advertising products has surpassed a $75 billion annual revenue run rate, reflecting the increasing adoption of automated advertising tools. More businesses are using these technologies to streamline and improve their digital marketing activities.
Meta’s generative AI creative tools are also gaining traction, with more than 9 million small businesses using at least one such tool. Newer end-to-end creative features could further simplify creating, launching, and managing campaigns, reducing the manual work required from advertisers.
Greater automation could help Meta attract more advertisers to its ecosystem and drive higher spending from existing customers on its platform.
Meta’s overall advertising business remains strong. In the second quarter, the Family of Apps generated $59.4 billion in advertising revenue, representing a 27% year-over-year increase. Advertising impressions grew 14%, while the average price per advertisement also increased. These figures point to continued demand for Meta’s advertising inventory and suggest that advances in AI-driven recommendations and targeting are supporting monetization.
Meta’s large advertising operation also generates substantial cash flow, enabling the company to fund significant investments in AI infrastructure and technology. While these investments could weigh on margins in the short term, stronger engagement, improved advertising efficiency, and continued AI development position it well to deliver solid growth ahead.
It’s Time to Load Up on Meta Stock
Meta’s investment case is relatively straightforward. The company is investing aggressively to build a larger, more profitable business over the long term, making the stock attractive at current levels. Meta’s durable core business, strong cash-generation capabilities, and rapidly expanding AI opportunity point to strong growth.
As AI continues to enhance user engagement and monetization across Meta’s platforms, the company can translate its enormous user base and powerful advertising ecosystem into sustained growth in revenue and free cash flow.
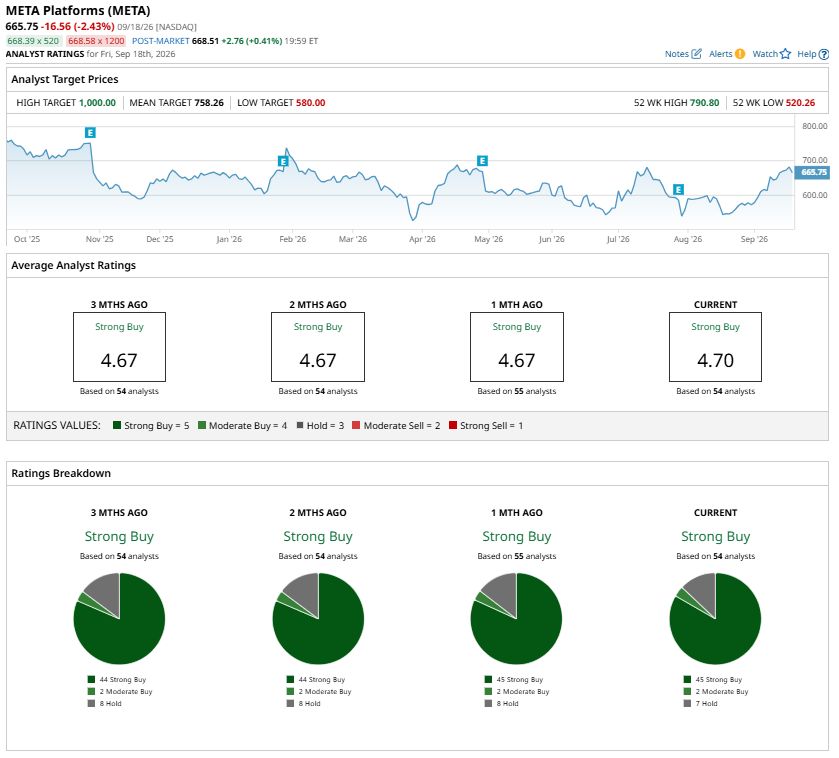
Despite the recent underperformance, Wall Street remains positive on Meta. Analysts currently maintain a “Strong Buy” consensus rating on META stock.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Substantially Higher Than a Car’: XPeng’s CEO on What Each Robot Could Earn. First It Has to Survive a Brutal Price War. Needham Just Upped Its Price Target on OKTA Stock. Here's Why. Why It’s Time to Load Up on Meta Stock As Snap Partners With Nvidia on Its Specs, Here’s How You Should Play SNAP Stock