

Micron (MU) will release its fiscal fourth-quarter earnings on Wednesday, Sept. 30. The semiconductor company is likely to deliver solid fourth-quarter growth, driven by strong demand and pricing for its memory and storage solutions supporting AI and compute-intensive applications.
In addition, Micron’s valuation looks compelling ahead of the Q4 earnings release, suggesting it’s time to load up on MU stock.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Micron’s Revenue and Earnings to Soar
Micron is positioned for another quarter of substantial growth, supported by robust demand for DRAM and NAND memory, and continued pricing strength. In the fiscal third quarter, Micron’s DRAM revenue reached $31.3 billion, up 343% year over year and accounting for about 76% of total revenue. Sequentially, DRAM revenue climbed 67%. Bit shipments rose in the low-single-digit percentage range, while average selling prices increased in the low-60% range, reflecting constrained industry supply and a favorable product mix.
NAND also delivered exceptional growth during the quarter. Revenue reached a record $9.9 billion, up 361% from the same period a year earlier and contributing about 24% of total revenue. Compared with the previous quarter, NAND revenue increased 99%. Bit shipments grew in the mid-single-digit percentage range, while pricing advanced in the mid-80% range. Tight market conditions and a favorable mix drove the sharp improvement in NAND pricing.
 www.barchart.com
The underlying market dynamics are expected to remain favorable in fiscal Q4. Memory demand continues to exceed available supply, and Micron management said industry demand for both DRAM and NAND remains well above production levels. Management also expects tight conditions across the memory market to persist beyond calendar 2027.
The favorable demand-supply environment is giving Micron significant pricing leverage. While rising production from Chinese manufacturers could eventually increase industry supply, the additional capacity is not expected to resolve broader supply constraints in the near term fully. Thus, Micron is expected to sustain its solid growth streak.
For the fiscal fourth quarter, Micron has guided revenue of approximately $50 billion, representing roughly 342% year-over-year growth. Profitability is expected to improve as well, with gross margin projected at 86%, compared with 84.9% in the preceding quarter and 45.7% a year earlier.
Earnings are expected to rise sharply, with EPS projected at approximately $31 per share, versus $3.03 in the year-ago quarter and $25.11 in fiscal Q3. Strong pricing, solid execution, and a favorable product mix are expected to support the company's bottom line. Wall Street analysts forecast EPS of $31.24, pointing to substantial year-over-year earnings growth.
Micron’s Long-Term Outlook Remains Solid
Micron’s long-term prospect is solid, supported by increasing revenue visibility and structural demand for memory products. Its strategic customer agreements (SCAs) provide a solid base for future growth, with 16 multi-year contracts currently covering about 20% of DRAM production and one-third of NAND output through 2030. These agreements are expected to expand and eventually contribute more than half of total revenue, while 14 contracts represent roughly $100 billion in minimum committed revenue.
Importantly, many SCAs use take-or-pay structures with pricing floors and ceilings. This framework can reduce earnings volatility by improving demand visibility and offering some protection against sharp memory-price declines. Beyond contractual support, Micron operates in expanding markets, as rising memory requirements in PCs, smartphones, automobiles, and robotics could sustain long-term demand and diversify its growth drivers.
Micron Stock Appears Undervalued
Micron’s earnings are expected to soar in the fiscal fourth quarter and beyond. Moreover, its stock looks compelling on valuation. MU currently trades at 6.4 times forward earnings, which is low given its solid earnings trajectory.
According to Wall Street estimates, Micron’s earnings could increase by more than 850% year over year in fiscal 2026, with earnings projected to rise another 117% in fiscal 2027. As MU stock is undervalued, it has room to run further.
Time to Load Up on Micron Stock
Micron’s revenue and earnings are expected to soar. Tight memory-market conditions and improving long-term revenue visibility provide a strong fundamental case for the stock. At roughly 6.4× forward earnings, the stock’s valuation also appears compelling. Taken together, strong fundamentals, favorable industry dynamics, and a low earnings multiple make Micron an attractive buy at current levels.
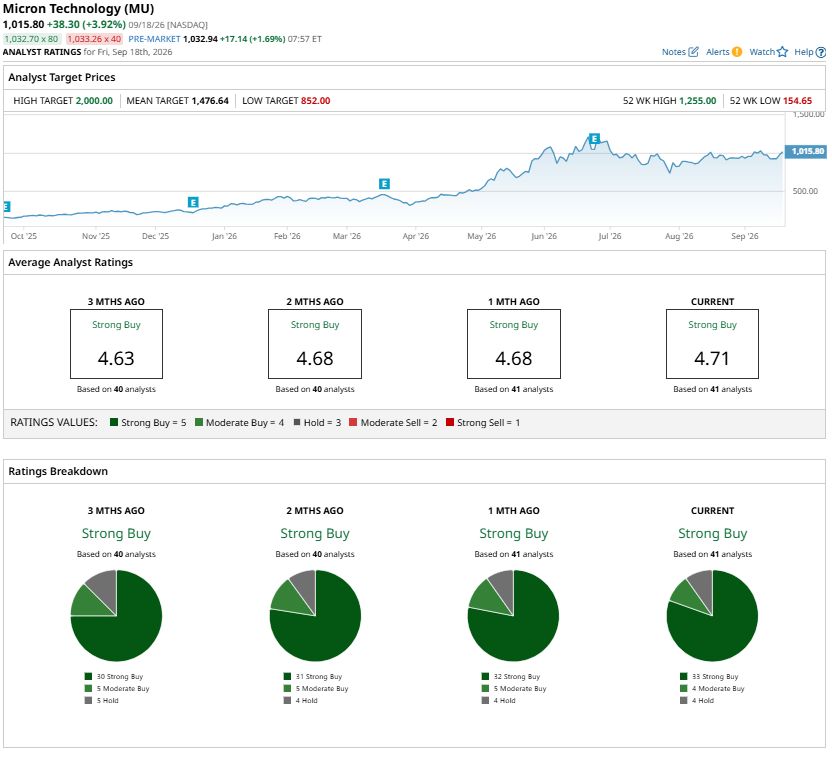
Micron currently has a “Strong Buy” consensus rating from analysts.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.