

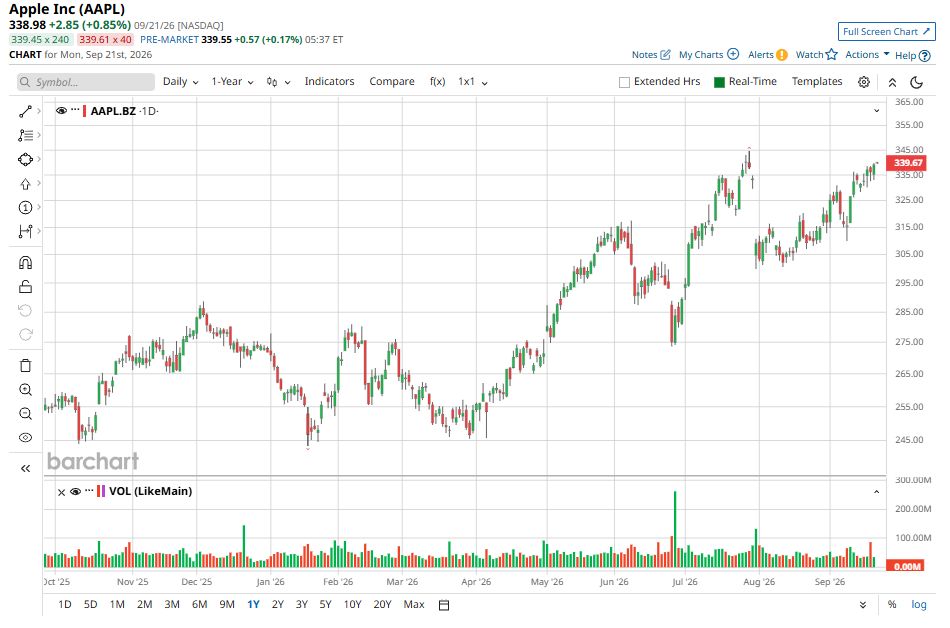
Apple (AAPL) stock may not have generated headline-grabbing gains, but the stock has outperformed the S&P 500 ($SPX) and its big tech peers. Apple is up about 24.7% year-to-date and has emerged as the strongest performer among the Magnificent Seven stocks in 2026, ahead of even Nvidia (NVDA).
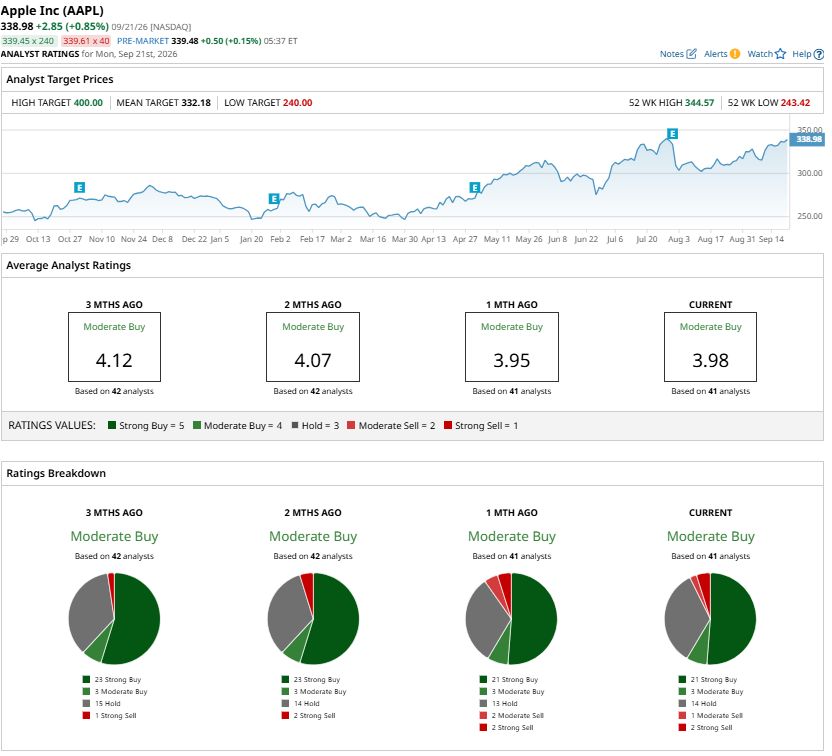
With Apple trading close to its record high, continued strength in iPhone demand could provide another catalyst for the stock. Wall Street analysts’ highest price target for Apple currently stands at $400 per share, which is within reach as the launch of new iPhone models could further support sales growth and potentially help Apple move toward that level.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
iPhone Demand to Power Apple Stock Higher
Sustained consumer interest in Apple’s flagship product will likely drive its revenue and earnings, especially as the newest iPhone lineup is expected to stimulate a stronger upgrade cycle and power its stock higher.
Recent industry data points to healthy demand for Apple’s latest iPhone models. Evercore ISI’s consumer research indicated that the company could be entering a stronger-than-expected iPhone upgrade cycle, with consumer interest supported by the launch of newer models.
Separately, JPMorgan noted that lead times for the iPhone 18 Pro models increased during the second week of orders, eventually reaching levels broadly comparable with those observed for the iPhone 17 series.
 www.barchart.com
Apple’s recent financial performance reflects the importance of the iPhone franchise. The company generated $109.4 billion in revenue in the fiscal third quarter, up 16% year over year. The iPhone remained Apple’s largest individual revenue contributor, generating $54.3 billion, up 22% from the same quarter a year earlier. This means roughly half of Apple’s quarterly revenue comes from the iPhone business.
The broader Products segment also demonstrated strong momentum, with revenue reaching $78.7 billion, an 18% year-over-year increase. Double-digit growth in both iPhone and Mac sales contributed to the result. Apple also saw strength across each geographic segment and highlighted a record number of iPhone upgraders.
From an investment perspective, these figures matter beyond the immediate increase in handset sales. Apple’s large installed base gives the company a recurring pool of potential customers, making the timing and strength of upgrade cycles key determinants of revenue growth. A higher proportion of existing users upgrading to newer devices will likely support monetization across Apple’s hardware, software, and services ecosystem.
Overall, iPhone could meaningfully contribute to Apple’s revenue and earnings growth, supporting its share price.
Apple’s Services Business to Provide a Durable Source of Growth
Apple’s Services segment remains an important source of growth and diversification for the company. In the latest reported quarter, Services revenue reached $30.7 billion, representing a 12% year-over-year increase. This growth is particularly significant because Apple reported quarterly revenue records across major service categories, including advertising, the App Store, AppleCare, Apple Music, and Apple TV+. At the same time, cloud and payment services also reached record levels.
A key structural advantage is Apple’s large installed device base. With more than 2.5 billion active devices, Apple has a substantial, recurring customer base it can monetize through subscriptions, digital content, payments, advertising, cloud storage, and other services. This ecosystem creates a strong link between hardware adoption and longer-term services revenue. As the number of active devices expands, Apple gains additional opportunities to generate revenue from existing users.
Why Apple Stock Could Hit $400 Soon
The path to $400 is not without risks. Apple's valuation is high, with the stock trading at a forward earnings multiple of 38.4. Supply constraints are another variable to monitor. In addition, not all analysts back Apple stock, and it carries a “Moderate Buy” consensus rating.
Still, the $400 price target represents about 18% upside from yesterday’s closing price of $338.98, which is achievable given its strong growth prospects. Resilient iPhone demand, a solid upgrade cycle driven by the latest iPhone models, and continued strength in the Services business will likely drive solid revenue and earnings and push the stock higher.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Apple Stock Nears Record High. Why $400 Could Be Next. Coinbase Stock Surges as Crypto Giant Eyes Financial Markets Expansion A 1,252% Revenue Surge Isn’t the Most Important Number in This Nvidia-Backed AI IPO Micron vs. SanDisk: 2 AI Memory Winners, But Only 1 Is Built for the Long Term