

The AI stock market is already crowded. Nvidia (NVDA), AMD (AMD), Broadcom (AVGO), CoreWeave (CRWV), Nebius (NBIS), and a growing list of infrastructure companies are fighting for investor attention as the AI story has now moved from chips into data centers, power, cooling, and compute.
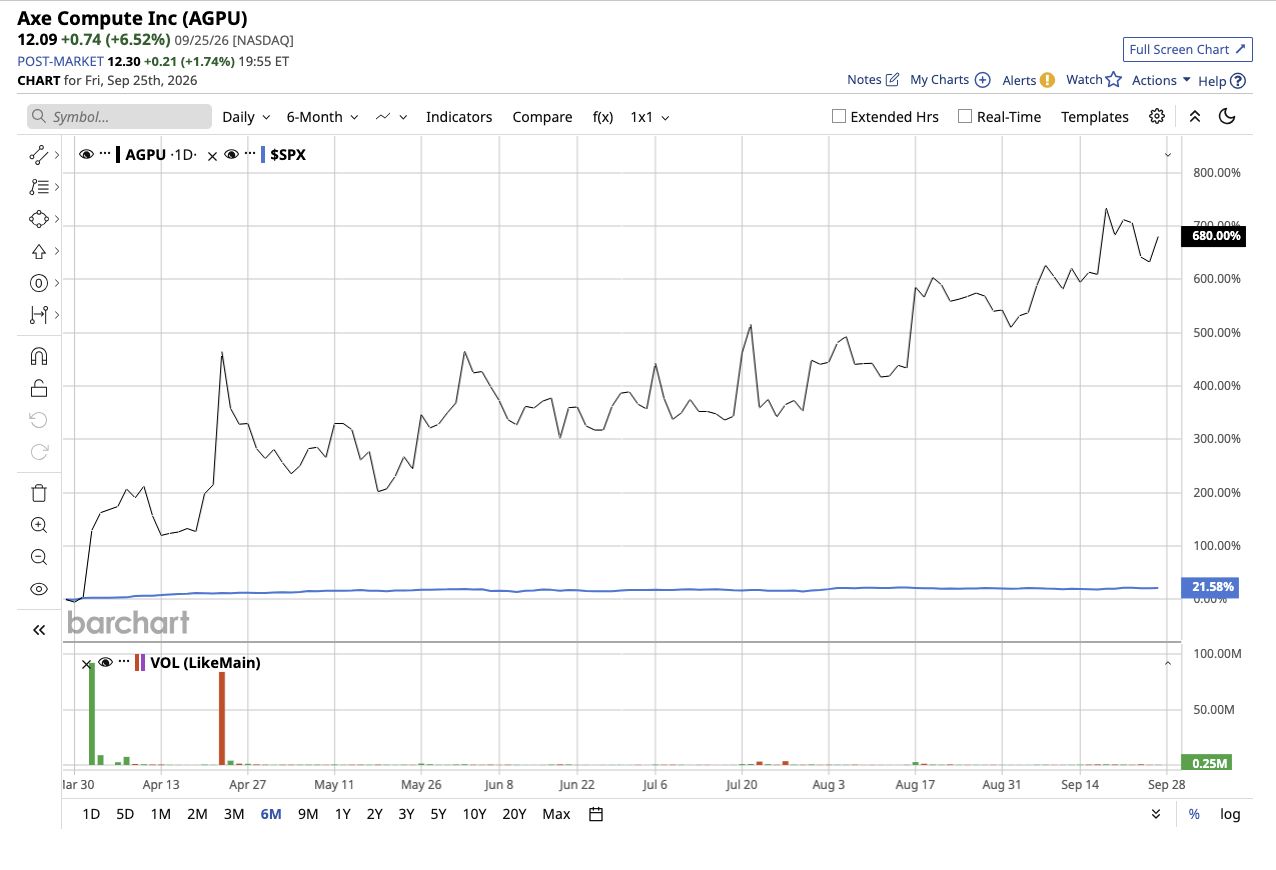
Axe Computing (AGPU) has sold its cancer diagnostics business to become a pure-play AI infrastructure company. AGPU stock’s roughly 67% year-to-date (YTD) gain reflects a dramatic change in what investors think the company could become. But in a market this competitive, can Axe Compute keep up?
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
The Cancer Business Is Officially Gone
On Sept. 15, Axe Compute sold its wholly owned Helomics subsidiary, its remaining oncology business, to DataMeds AI (MEDS). However, the company didn’t completely walk out of its oncology business. It has retained exposure through DataMeds shares and the convertible note, which resulted in a total purchase value of $1.5 million. Management stated that this way Axe shareholders will retain potential upside if the acquired oncology platform grows under its new owner.
Axe Compute Is Now Betting on GPUs
The sole reason for the sale was to let Axe Compute focus entirely on GPU infrastructure. Investors should understand that the company is not starting as an AI company from scratch. In fact, AI infrastructure has been the company’s side business since 2025. However, now management wants it as the central growth engine.
Axe’s business model involves providing enterprises with access to dedicated GPU infrastructure without requiring those customers to build and operate the underlying hardware themselves. Through its Build business, Axe Compute designs, sources, finances, and operates dedicated GPU clusters under long-term contracts. Its Access business provides faster access to existing compute capacity. In the second quarter, the company generated $3.2 million in revenue from its first full quarter of compute operations.
And Axe also has a significant amount of customer commitments going forward. During its second quarter, the company announced adding $2.8 billion of contracts, bringing its 2026 signed contracted value above $3 billion. Axe expects these contracts to generate an annualized revenue run rate of more than $696 million once the deployments are fully operational. That will be a massive jump from what the company generates now. However, this revenue depends on infrastructure being deployed, accepted, and placed into service.
Axe Compute’s AI story is not just based on these future commitments. As of August, the company had already received more than $317 million in customer prepayments tied to the more than $3 billion of AI infrastructure contracts it announced in July. Axe expects this to help fund the deployment of its dedicated GPU infrastructure across the U.S. and Europe.
Investors should note that this $317 million is not revenue that the company has yet to recognize. It is just the customer prepayments made ahead of infrastructure deployment and service delivery.
The company has already begun building the physical infrastructure needed to support the contracts. In August, it announced agreements with Duos Technologies (DUOT) covering as much as 55 megawatts of AI data center capacity across multiple U.S. locations, with expected aggregate payments exceeding $500 million. To meet these commitments, the company is spending heavily to acquire and deploy GPU infrastructure, which is weighing on the bottom line. The company reported a net loss of $17.2 million. It ended the second quarter with $21.9 million of cash, while customer prepayments had helped push contract liabilities to roughly $60.7 million.
Is AGPU Stock a Good Buy Now?
Axe Compute is no longer a cancer-focused company with AI infrastructure as a side business. It is now a pure-play neocloud GPU company with over $3 billion of signed contracts and $317 million of customer prepayments, which gives its new strategy tangible financial backing. However, the challenge now is whether Axe Compute can execute fast enough to turn its contract backlog into revenue and eventually profits. The company has to do all this while competing against much larger AI infrastructure players.
AGPU stock has surged more than 650% in the past six months as investors have started valuing Axe Compute as an AI infrastructure play, but the company still has a lot to prove.
Therefore, Axe Compute remains a high-risk AI story now.
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.