

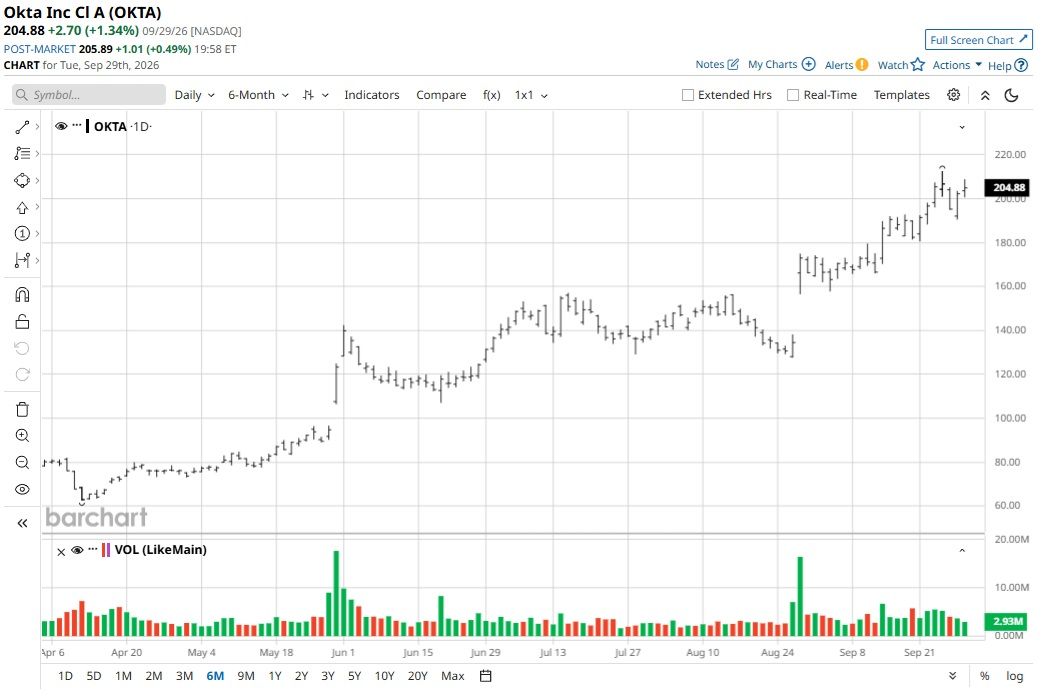
Okta (OKTA) stock has surged 146% year-to-date (YTD). Considering the company's first-half fiscal 2027 top-line growth of just over 10%, clearly there is another factor driving the stock's momentum.
Morgan Stanley analyst Meta Marshall recently reiterated an “Overweight” rating for OKTA stock with a price target of $245. Marshall also highlighted the key factor pushing OKTA stock higher: The company’s exposure to the emerging “Agentic Identity” opportunity. Marshall opined in her analysis that Palo Alto Networks (PANW) and CrowdStrike (CRWD) are being highlighted as winners in the theme. However, upon looking at broader set of names, Okta is a “secular winner from Agentic Identity exposure.”
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Amidst the stock rally, one important point to note is that Okta trades at a forward price-to-earnings (P/E) ratio of 106.6 times. Valuations might look stretched, but Okta believes that its total addressable market is $80 billion. This leaves ample headroom for growth. Further, as its backlog swells, the company has clear revenue and cash flow visibility.
About Okta Stock
Headquartered in San Francisco, California, Okta operates as an independent identity partner. The company’s Okta Platform and Auth0 Platform enables its customers to securely connect the right people to the right technologies and services at the right time.
As of August 2026, Okta had more than 20,000 customers across diversified industries. As of January 2026, the company also had more than 7,000 integrations with cloud, mobile and web applications as well as IT infrastructure and security vendors.
Okta employs the SaaS business model and generates revenue primarily by selling multiyear subscriptions for its cloud-based offerings. For fiscal 2026, Okta generated 20% of revenue from outside of the United States.
For the first half of fiscal 2027, Okta reported revenue growth of 11% on a year-over-year (YOY) basis to about $1.6 billion. For the same period, the company’s operating cash flow and free cash flow were healthy at $511 million and $498 million, respectively.
OKTA stock has surged 169% in the last six months. This performance has been backed by strong Q2 numbers, optimistic guidance, and a surge in remaining performance obligations (RPO), or subscription backlog, to $4.9 billion as of Q2 fiscal 2027.
 www.barchart.com
Growth Acceleration Is Likely
In Q2, new products represented approximately 30% of bookings. Particularly, the launch of AI agent products has been a game-changer for the company in terms of bookings growth and addressable market.
To put things into perspective, Okta is the “first independent neutral identity platform to bring AI agent governance to highly regulated environments,” per CEO Todd McKinnon. With a first-mover edge, the company is well-positioned to benefit. It’s also worth noting that the average deal size for AI-agent products is higher and has already increased contract values. It’s likely that Okta's backlog will continue to swell at a healthy pace in the coming quarters.
Amidst these positives, Okta ended Q2 with a cash buffer of $2.3 billion. Further, the company expects non-GAAP free cash flow of $920 million at the midpoint for fiscal 2027. Therefore, financial flexibility remains robust and is likely to support significant R&D coupled with investments for international expansion. The cash-generation potential is another factor that supports premium valuations for a business that is capital-light.
What Do Analysts Say About OKTA Stock?
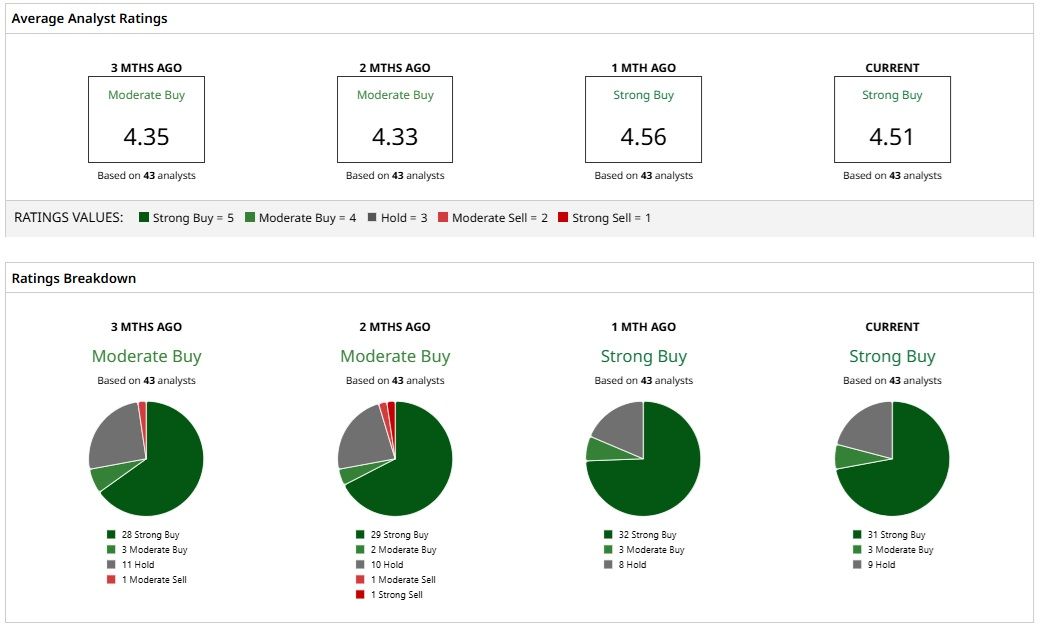
Considering the growth in remaining performance obligations since the launch of AI-agent products, the outlook for Okta appears positive. Based on 43 analysts with coverage, OKTA stock has a consensus “Strong Buy” rating on Wall Street. While 31 analysts have a “Strong Buy” rating for the stock, three have a “Moderate Buy,” and nine analysts have a “Hold” rating.
The mean price target of $210.21 has already been surpassed. However, the most bullish price target of $250 suggests that OKTA stock could climb as much as 18% from current levels.
 www.barchart.com
On the date of publication, Faisal Humayun Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Commercializing AI Agents Will Help Okta Accelerate Its Growth Micron Beat on Earnings and Guided Above Estimates. How Investors Should Play MU Stock Here. Workday Plans to Cut 2.5% of Its Workforce and Revise Its Margin Outlook. How Investors Should View the Move. Chevron Stock May Attract Value Investors, Especially If It Hikes the Dividend Next Year