

With a market cap of $165.3 billion, Union Pacific Corporation (UNP) is one of the largest freight railroad operators in the U.S., moving everything from agricultural products and industrial goods to energy and consumer products across 23 western states. The Omaha, Nebraska-based railroad plays a critical role in connecting businesses and communities to domestic and global markets while offering a more fuel-efficient alternative to trucking.
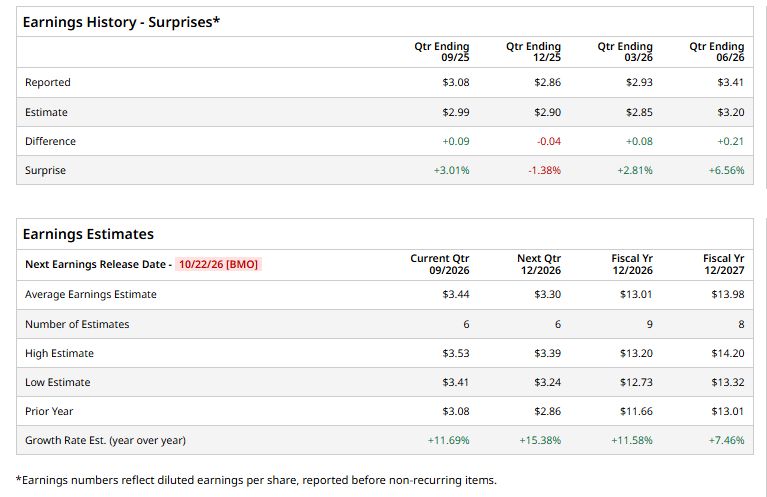
Investors will turn their attention to Union Pacific on Thursday, Oct. 22, when the company is scheduled to report its fiscal Q3 2026 results before the market opens. Wall Street expects EPS of $3.44, an 11.7% rise from $3.08 in the year-ago quarter. UNP has delivered an earnings beat in three of the past four quarters, with just one miss during that stretch.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Looking beyond the upcoming report, analysts remain optimistic about Union Pacific's earnings trajectory. Fiscal 2026 EPS is projected to climb 11.6% to $13.01, from $11.66 in 2025. Moreover, EPS is expected to grow 7.5% year over year to $13.98 in fiscal 2027.
 www.barchart.com
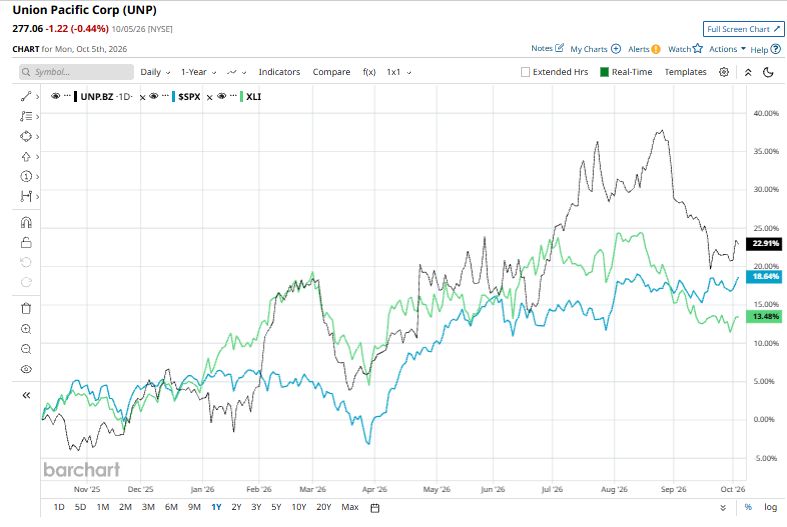
Shares of Union Pacific have increased 17% over the past 52 weeks, outperforming the broader S&P 500 Index's ($SPX) 15.8% return and the State Street Industrial Select Sector SPDR ETF's (XLI) 10.2% gain over the same period.
 www.barchart.com
Union Pacific and Norfolk Southern Corporation (NSC) are gaining momentum in their bid to create America’s first truly coast-to-coast railroad. The Surface Transportation Board unanimously rejected requests to dismiss the companies’ revised merger application, clearing the way for regulators to continue reviewing the proposed combination.
The deal is also picking up support from labor, with SMART-MD signing a jobs-for-life agreement that protects represented positions. The companies argue that combining their networks would create a faster, more efficient freight system by eliminating time-consuming railroad handoffs, converting 10,000 interline routes to single-line service, and adding seven new premium intermodal lanes. If approved, the merger could also take more than 2 million truckloads off U.S. highways, easing congestion while giving customers more direct and potentially lower-cost freight options. The transaction remains subject to STB approval and continued regulatory oversight.
Analysts' consensus view on UNP stock is very optimistic, with an overall "Strong Buy" rating. Among 25 analysts covering the stock, 18 suggest a "Strong Buy," one gives a "Moderate," and six provide a "Hold" rating. The average analyst price target is $332.56, suggesting a potential upside of 20% from current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Is the 60/40 Portfolio Finally Back to Work? It Depends on One Thing. 2 Strong Reasons Micron Is Still a Top Stock to Buy Now Delta Airlines Earnings Trade: A High Probability Options Setup Why On Semiconductor Is Betting Big on AI Power and What Its $5.7 Billion Bet Means for ON Stock