

Elon Musk wants to build his own chip factory, and Taiwan Semiconductor Manufacturing (TSM) could be a key partner. But Taiwan's largest company has drawn a line it will not cross.
The two sides are reportedly discussing Terafab, Musk's Texas chip project. What we do know is they disagree on one key element: who runs the factory?
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
TSMC and Terafab Are Talking, but Who Runs the Fab?
Bloomberg reported that TSMC is in talks about working with Terafab. The project is Musk's effort to manufacture chips for Tesla (TSLA), SpaceX (SPCX), and xAI. Intel (INTC) will help develop the Terafab plant technology.
Notably, TSMC CEO C.C. Wei confirmed the talks on TSMC's third-quarter earnings call on Oct. 15. Then he added the condition, stating:
“But the fab has got to be run by TSMC.”
Last week, Musk said TSMC would lease capacity at most and stressed that his companies would “build and run the fab,” Bloomberg reported. An analyst asked whether it would look like TSMC's ventures in Japan and Europe. Wei said it could go either way, but TSMC must be the operator.
Why TSMC Will Not Hand Over the Keys
TSMC explained that the key reason is efficiency. CFO Wendell Huang said TSMC remains the most cost-efficient manufacturer in every region it operates. Huang said overseas fabs will cut gross margin by close to 2% in 2026. As more U.S. fabs ramp up production, he expects that drag to widen to 3% to 4% in the next few years.
So TSMC is already paying a premium to build in America, and letting someone else run a plant would put its core strength in an outsider's hands.
TSMC can afford to be picky.
Here is what the third quarter looked like, given its continued steady growth.
Here’s how it performed in Q3 of 2026:
Revenue: $46.7 billion, up 16.2% from Q2 and above guidance. Gross margin: 66.4%, down 1.3 points because of the 2-nanometer ramp. Operating margin: 58.7%. So, TSMC kept about 59 cents of every revenue dollar as operating profit. Earnings per share: $0.91 (TWD 29.43). Cash from operations: about $28.5 billion (TWD 920 billion).High-performance computing, the chip category that includes AI, accounted for 68% of revenue. TSMC guided fourth-quarter revenue to between $52.3 billion and $54.3 billion. At the midpoint, that is a 58% jump from the year-ago period. Wei now expects full-year 2026 revenue growth of around 44%.
TSMC also reiterated a 2026 capital budget of $60 billion to $64 billion. In Q3, it spent nearly $14 billion on capital expenditures.
Texas Fits Expansion Plans
Wei said most of TSMC's large customers are in the U.S., and they have asked for more “American” capacity. TSMC has now looked beyond Arizona. Wei said the company sent teams to Texas to evaluate sites. He also said TSMC spoke with a customer building a fab, and Wei named Terafab as a potential opportunity.
TSMC finished building its second Arizona fab, and volume production of 3-nanometer chips is set for the third quarter of 2027, slightly ahead of schedule. Worldwide, nearly 20 fabs are under construction because of strong demand from multiple AI companies.
Is TSM Stock Still a Good Buy?
A deal with Terafab would increase U.S.-origin demand at a time when customers want domestic capacity. However, margin pressure from overseas fabs is set to grow. Wei also warned that consumer and price-sensitive markets are under strain.
TSMC is being prudent in its prospects because of higher prices, making control of the plant even more important.
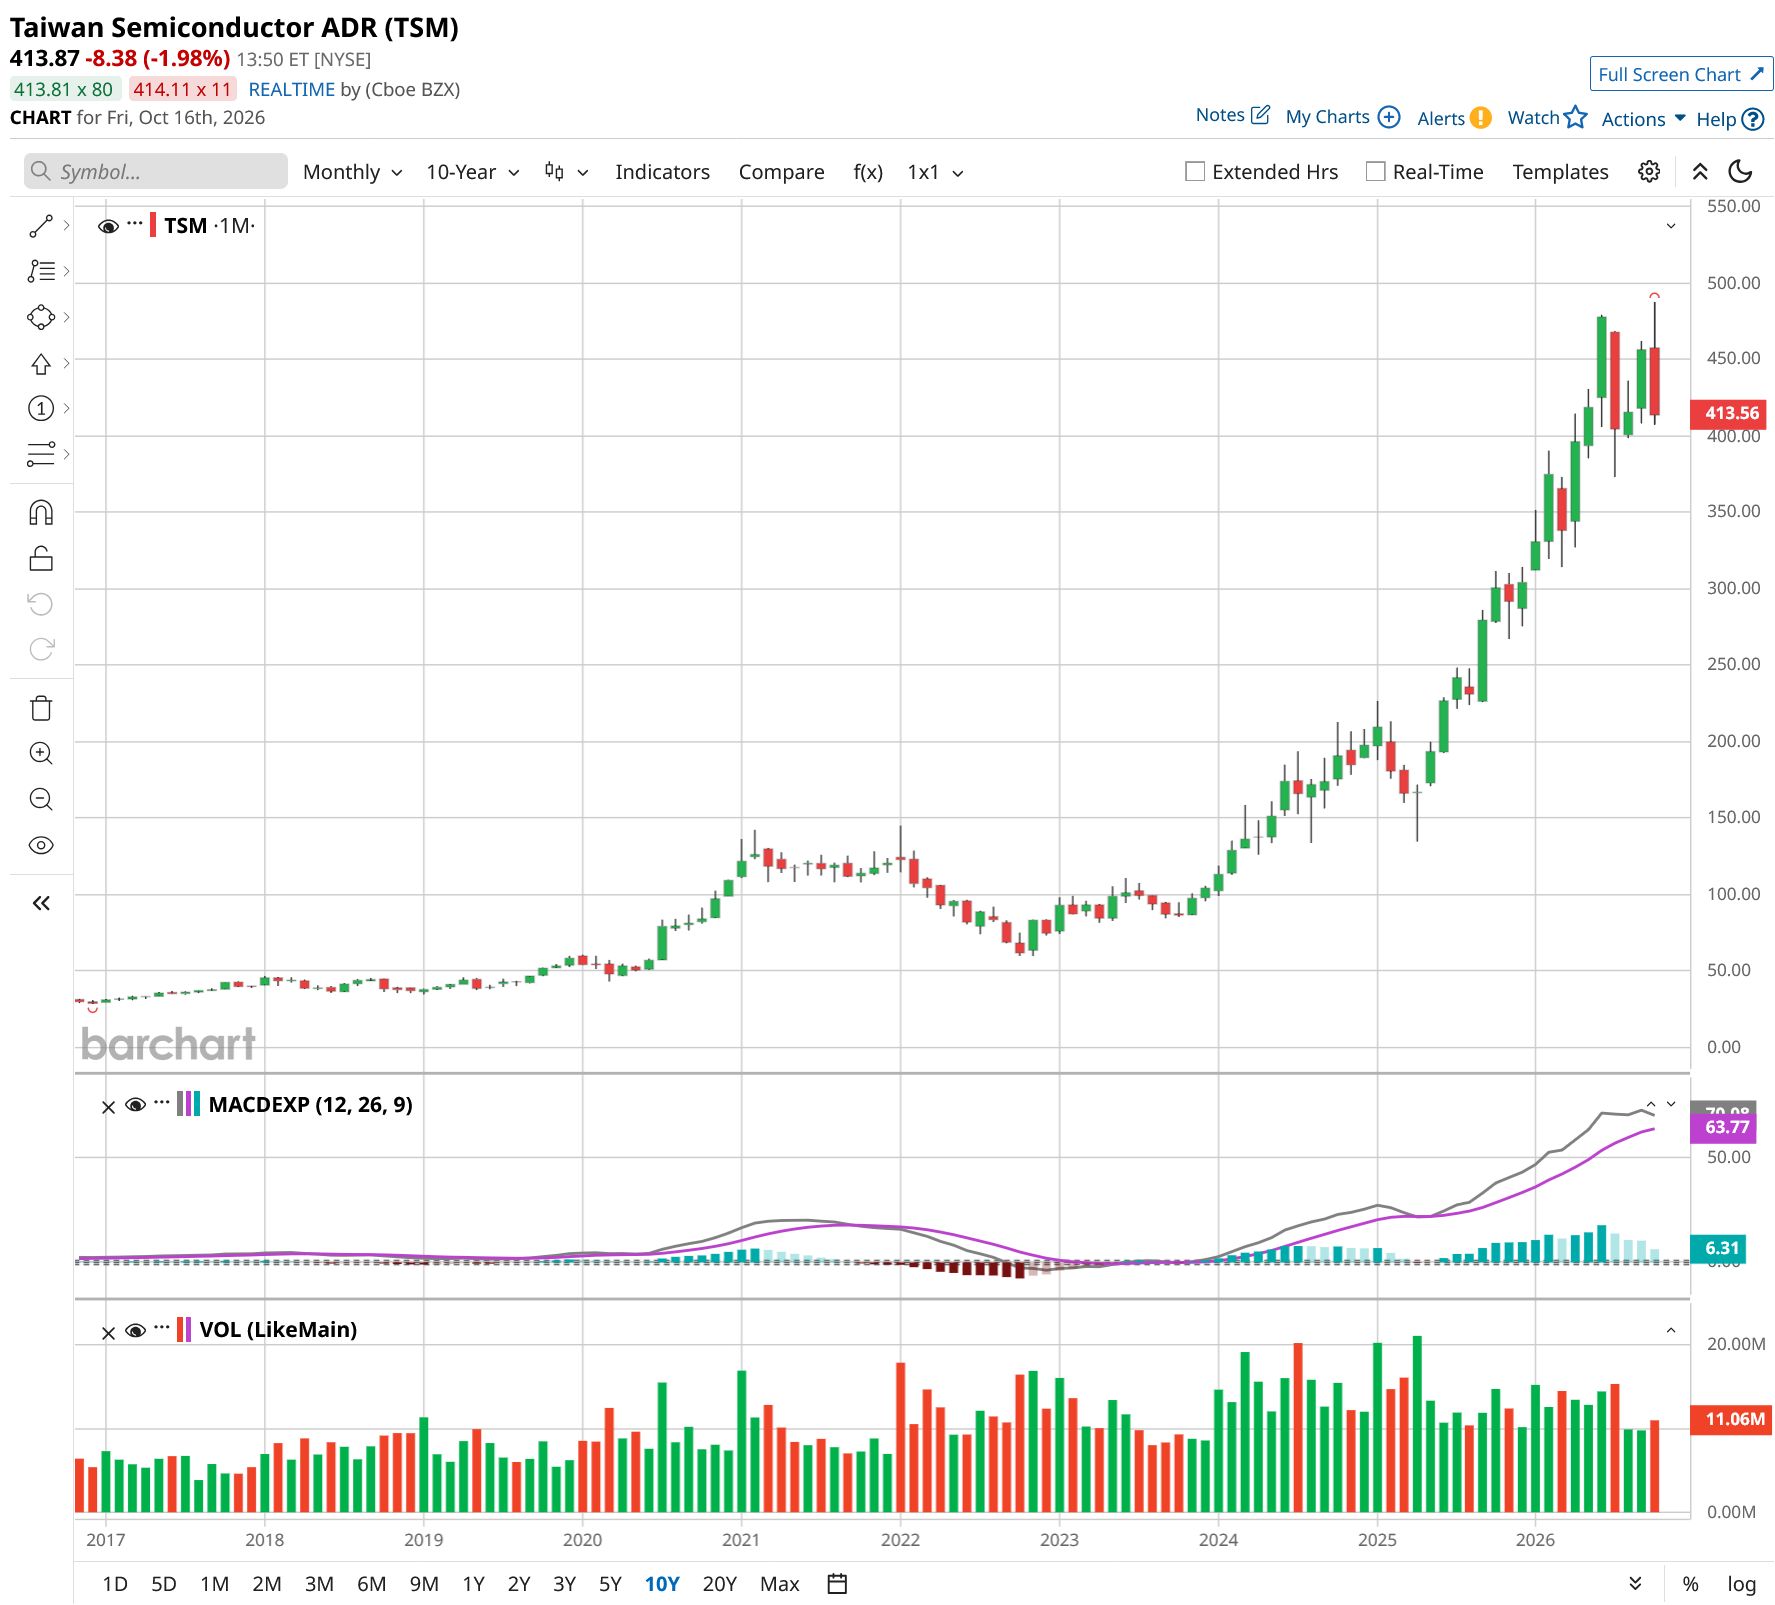
Analysts expect AI-fueled growth for TSMC to continue through 2030. Wall Street expects revenue to grow from $120.6 billion in 2025 to $413 billion in 2030. Over this period, net income is projected to expand from $54.4 billion to $197 billion. If TSM stock is priced at 18x forward earnings, similar to its five-year average, it could surge 75% from current levels.
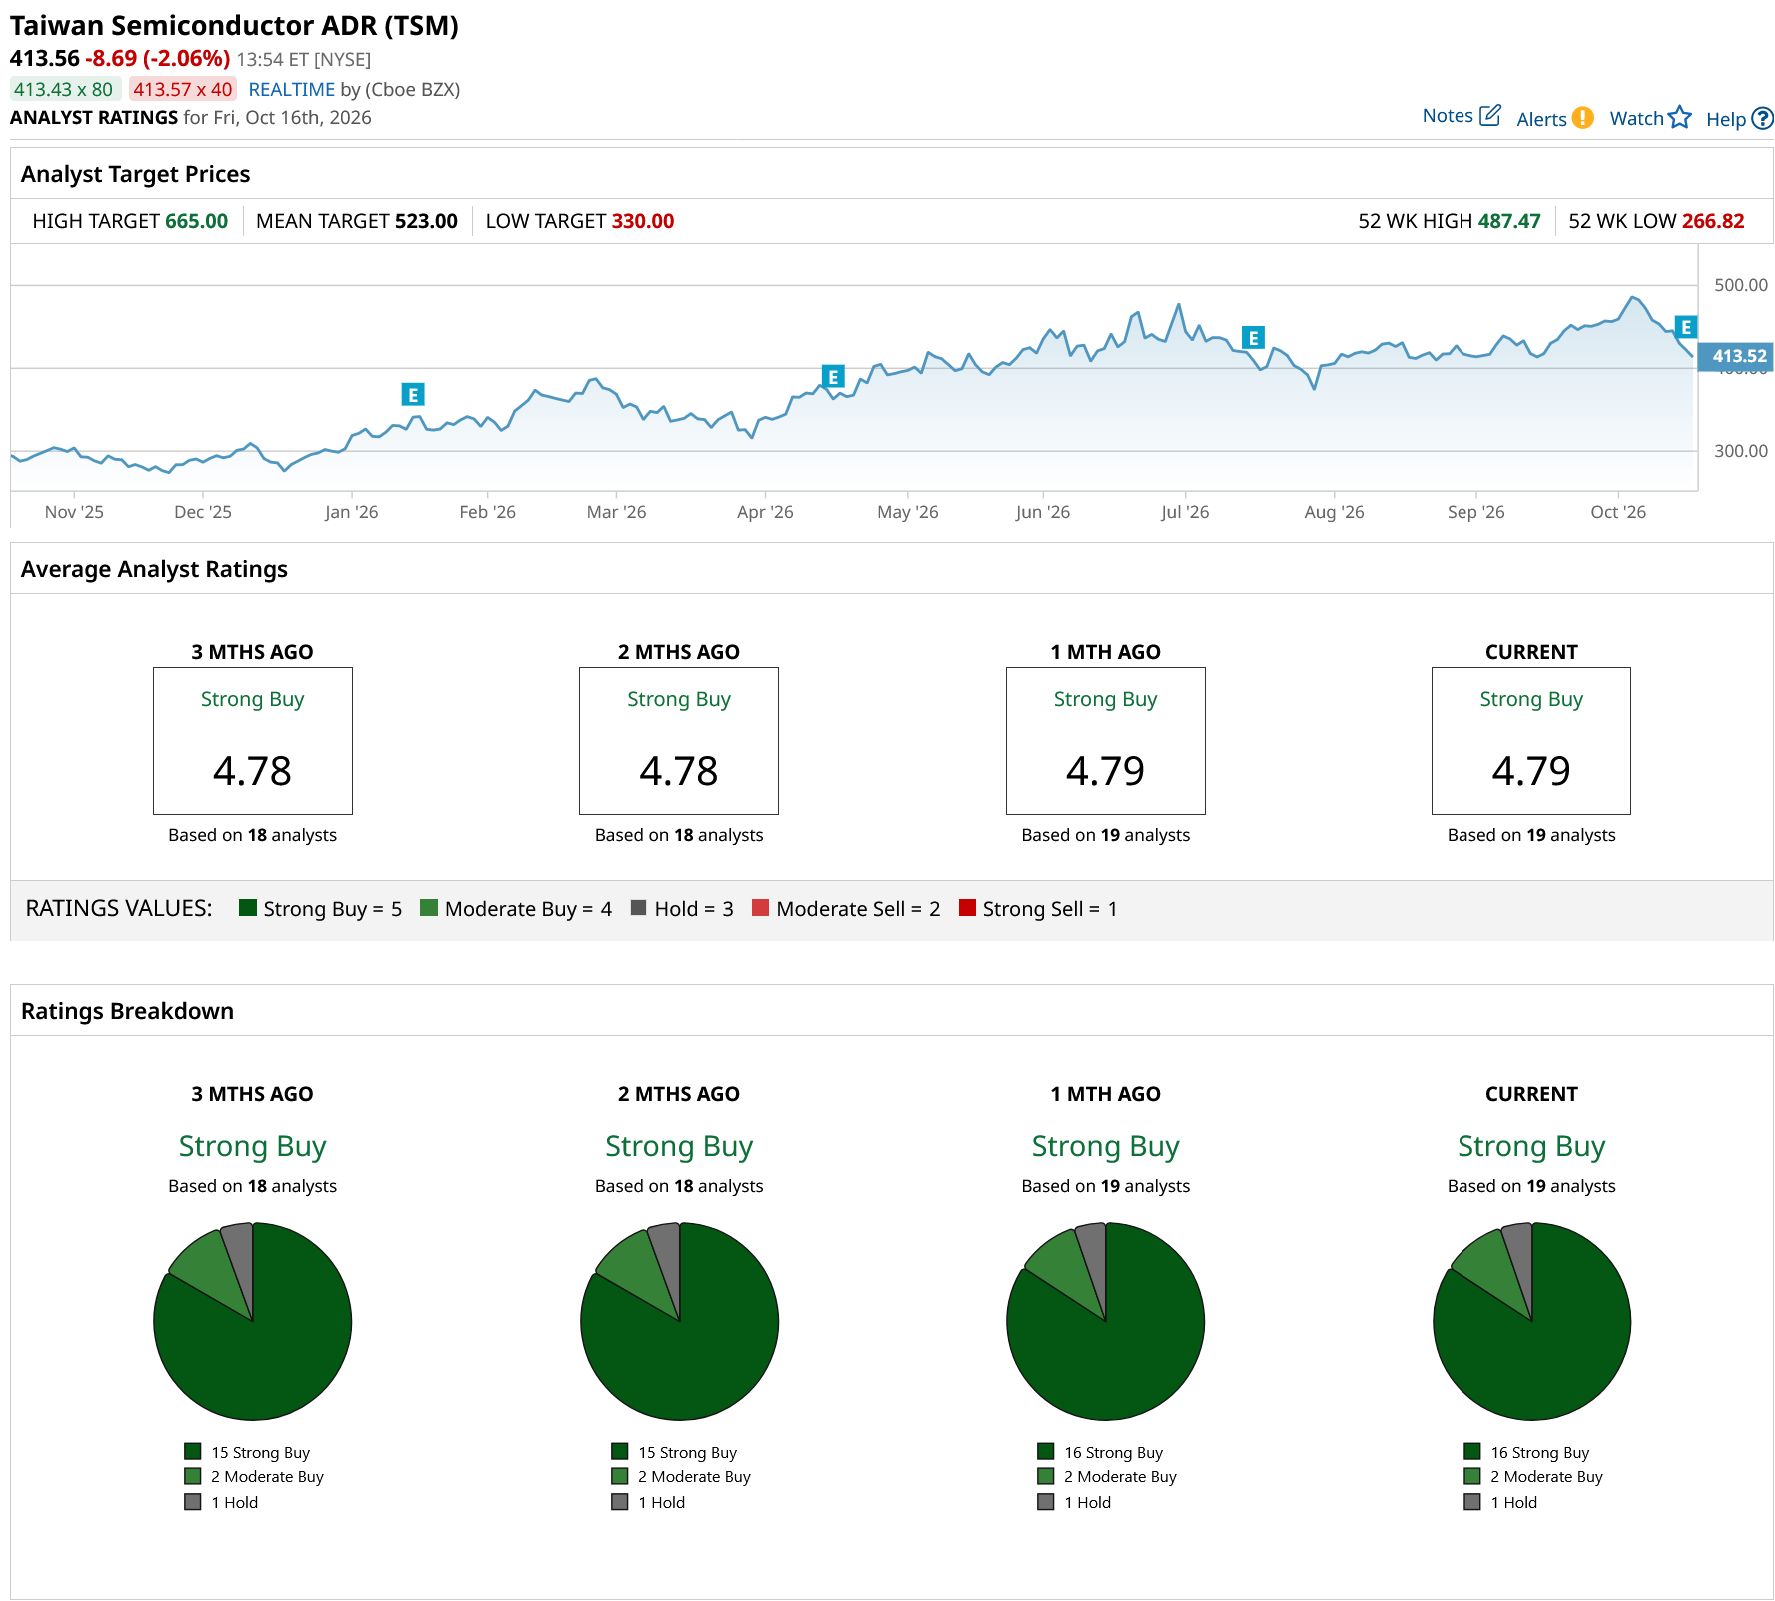
Out of the 19 analysts covering TSM stock, 16 recommend “Strong Buy,” two recommend “Moderate Buy,” and one recommends “Hold.” The average TSM price target is $523, above the current price of about $414.
 www.barchart.com
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why 1 Analyst Is Cooling Their Stance on Red-Hot DELL Stock Intel vs. AMD: The CPU Comeback Has Become a 2-Stock Fight, But 1 Is the Better Buy Taiwan Semiconductor Could Partner With Elon Musk’s Terafab, but It Has 1 Condition Berkshire Hathaway Raised Its Stake in Bending Spoons to 4%. That’s a Big Vote of Confidence Retail Investors Should Follow.