

CoreWeave (CRWV) CEO Michael Intrator isn't happy with Wall Street's assessment of his artificial intelligence (AI) company, and he's making sure his employees know it. According to a Bloomberg report, Intrator sent an internal memo to employees defending CoreWeave's financial strength as investors raised concerns about its massive debt and the cost of financing its AI infrastructure expansion.
"When you are building a new type of technology company, there will be periods of time when the market misunderstands and acts irrationally," he wrote in the memo.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
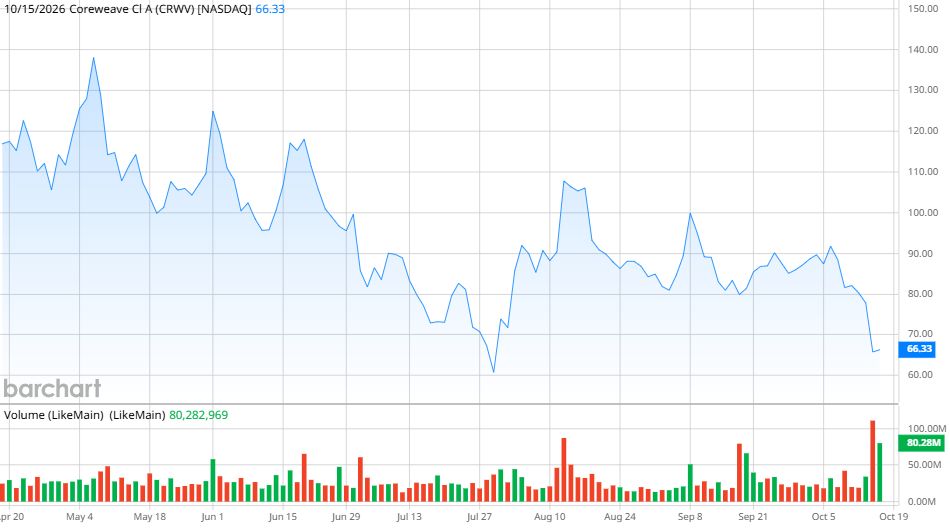
But with CoreWeave facing questions about its borrowing costs and its ability to turn demand for AI computing into sustainable profits, investors have reasons to be concerned. CRWV stock is currently down 16% in the last three months.
Is Wall Street overlooking an opportunity to buy the dip? Or is CoreWeave taking on too much risk?
What Does CoreWeave Do?
Based in Livingston, New Jersey, CoreWeave is a cloud computing company that provides infrastructure for its customers to train and run AI models. Its business revolves around powerful GPUs from Nvidia (NVDA), which are particularly effective at handling the enormous computing workloads required by AI.
Rather than building their own computing infrastructure — something that costs billions of dollars — CoreWeave’s customers rent access to GPU-powered systems. AI developers and businesses get access to powerful computing resources without having to purchase and maintain the equipment themselves.
CoreWeave has established relationships with some of the biggest names in artificial intelligence, including Microsoft (MSFT), Meta Platforms (META), and OpenAI. The company also has an especially close relationship with Nvidia, which announced a $2 billion investment in CoreWeave in January.
CoreWeave's second-quarter earnings report showed a revenue backlog of approximately $104 billion as of June 30, excluding more than $25 billion in additional customer commitments announced earlier in Q3.
 www.barchart.com
Here’s the catch: CoreWeave needs to spend heavily on GPUs, data centers, electricity, and networking equipment before it can deliver the computing capacity its customers are buying. And much of that expansion is being financed with borrowed money.
That makes the company's financial health especially important. The company recorded $2.57 billion in revenue in Q2, up 112% from a year ago. But operating expenses of $2.62 billion completely absorbed that, and once you add in net interest expense and other non-operating items, CoreWeave was left with a net loss of $626 million versus a loss of $290 million a year ago. Diluted EPS came in as a loss of $1.14 per share versus a loss per share of $0.60 in Q2 2025.
Management projected that CoreWeave will end the year with 1.85 gigawatts of computing capacity, up from previous guidance of 1.7 GW. Meanwhile, Q3 revenue is projected at $3.45 billion to $3.6 billion, with adjusted operating income of $200 million to $260 million. However, the company is projecting interest expense between $860 million and $940 million — a reflection of the company’s debt load — and CoreWeave also plans to spend $11.5 billion to $13.5 billion on capital expenditures during the quarter.
What Do Analysts Expect for CRWV Stock?
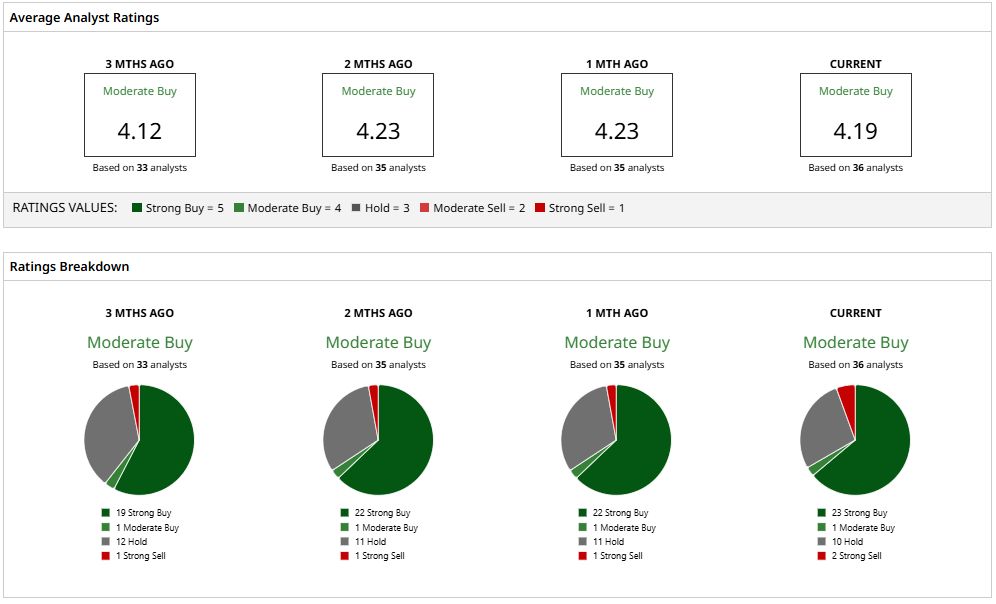
Analysts are generally positive, although there has been some slippage in the company’s overall rating. Based on 36 analysts with coverage, CoreWeave stock has a consensus “Moderate Buy” rating overall, although two of those analysts have “Strong Sell” ratings. The mean price target of $136.23 suggests that CRWV stock could climb as much as 122% from current levels.
 www.barchart.com
Intrator has a point when he argues that CoreWeave's underlying business deserves attention. A $104 billion revenue backlog provides evidence of substantial customer demand, and the company's partnerships with major technology firms give it opportunities to grow.
But CoreWeave still has to build and deliver the infrastructure required under those contracts, and that takes enormous amounts of capital.
For investors considering CRWV stock, the important issue isn't whether Intrator believes Wall Street is treating his company unfairly. It's whether CoreWeave can turn its massive backlog into enough cash flow to support its expansion and debt obligations. That's how the company can make its case to investors.
On the date of publication, Patrick Sanders had a position in: NVDA . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Traders Give Google a 70% Chance of Having the Best AI Model. Most People Can’t Even Use It Yet. CoreWeave’s CEO Says the Market Doesn’t Understand His Company. Whether or Not It Does Isn’t What Matters Here. Chevron Stock Price Targets Are Up and Put Credit Spreads Are Attractive to Value Players Ahead of General Motors Earnings, Here's What Barchart Data Says Comes Next for GM Stock