

Taiwan Semiconductor Manufacturing Company (TSM) isn't just the world's biggest chip foundry. It's the backbone of the entire AI hardware food chain. Nvidia (NVDA) designs the chips. Apple (AAPL) specs them. AMD (AMD) pushes them. But TSMC actually builds them.
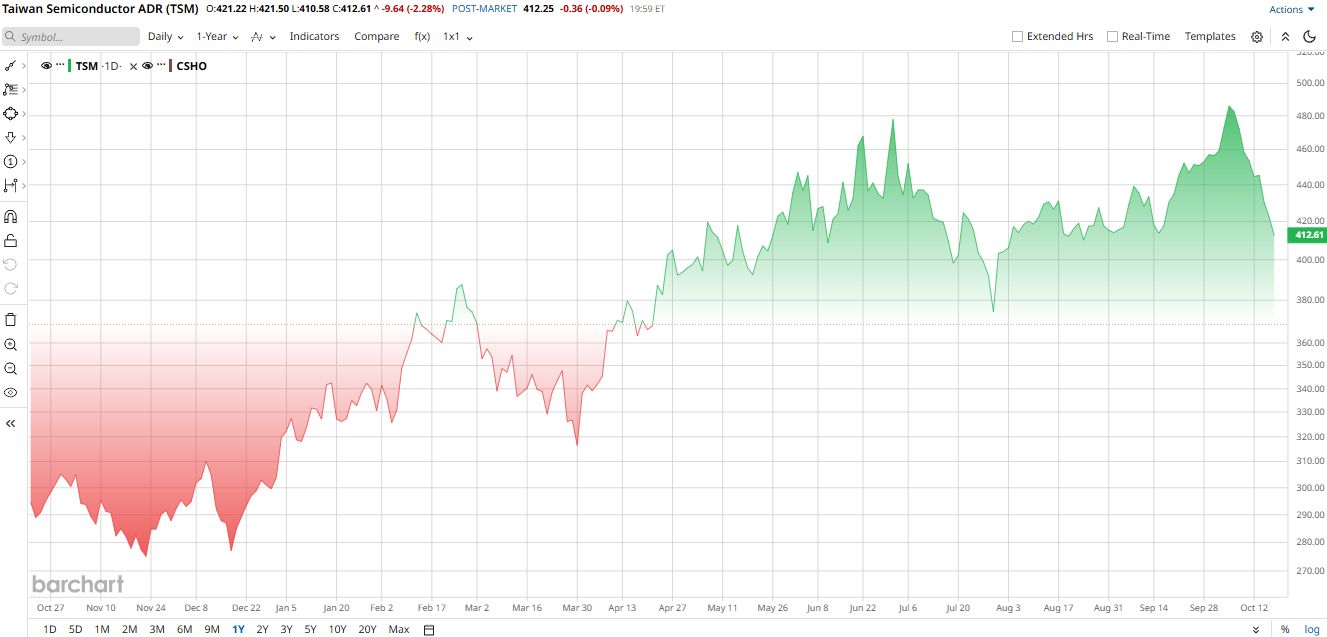
That reality is why TSM stock has soared roughly 37% so far in 2026, despite a 6% selloff over the past week along with the broader index.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Now the news is that Taiwan is reportedly planning a $4 billion industrial hub in Texas to support TSMC's sprawling supplier network.
The idea is simple. Move the ecosystem closer to the customer. That could lower costs, reduce tariff risk, and speed up production for Nvidia and Foxconn. This is a game about supply chain gravity shifting toward American soil. And Taiwan Semi sits right at the center of it.
Record Profits Keep TSMC’s AI Growth Story Alive
TSM stock has been a monster performer. Record profits for six straight quarters will do that. The AI data center buildout is still running hot. High-performance computing is now two-thirds of total revenue. But the ride hasn't been perfectly smooth. Sector-wide selloffs have hit chip stocks hard. And management flagged some near-term margin pressure from the 2 nanometer ramp and overseas fab costs. That's a small price to pay for long-term capacity.
And here comes the most interesting thing. At around $412 a share, TSM trades at 27 times trailing earnings. The industry median is 25. Its forward P/E sits at 22. The sector median is 23. That's a clear discount for the undisputed leader in advanced chip manufacturing. You don't often get the best house on the block at a below-average price.
 www.barchart.com
The Texas Hub: What It Means for TSMC
So the thing is that Taiwan's government is seeking to construct a $4 billion facility in Texas. It would provide space for smaller suppliers to TSMC and Foxconn. There's one reason why this is important. Arizona's fabs require an Arizona ecosystem at TSM. If it wasn't, each and every small part would travel across the Pacific. That's Texas math in the making. This also aids in avoiding possible tariffs on imported chip parts for TSM.
Imagine a moat constructed from concrete and logistics. Nearer the circle of suppliers to TSMC U.S. fabs, the more difficult it gets to duplicate the supply chain for the competition. This is a long-term benefit.
Additionally, TSMC didn't wait for Texas. In July, it announced an additional $100 billion investment in Arizona. That brings its total planned U.S. spending to a staggering $265 billion. Taiwan is also tightening export controls on AI chips to align with U.S. restrictions on China. Both moves reinforce a simple idea.
TSMC is becoming a U.S.-centric advanced chip manufacturer. That reduces geopolitical risk and strengthens its relationship with Washington. The Texas hub is just the latest layer.
Taiwan Semi Just Posted Record Earnings
Taiwan Semiconductor Manufacturing Company just posted another quarter of blockbuster earnings, driven by strong demand for AI chips.
The world's biggest contract chipmaker posted a record $46.72 billion in revenue for the third quarter ended on Oct. 15, a solid 41.2% increase from the same period last year. Net income rose by a record 68.7% to NT$763.06 billion.
AI is the business's top growth enabler. Revenue for high-performance computing grew by 22% sequentially and made up 68% of total sales.
But TSMC's prospects could be even better. The management sees revenue in the range of $52.3 billion to $54.3 billion in Q4 and has revised its revenue projections for 2026 to about 44%.
However, investors need to be mindful of the risks. Although facing economic uncertainties, management has taken a conservative approach to build 2027; management is already investing $60 billion to $64 billion in 2026 to grow capacity to meet demand.
But the opportunity for investors must surely be compelling, and yet growth must continue, and costs must be kept in check.
What Wall Street Says About TSM Stock
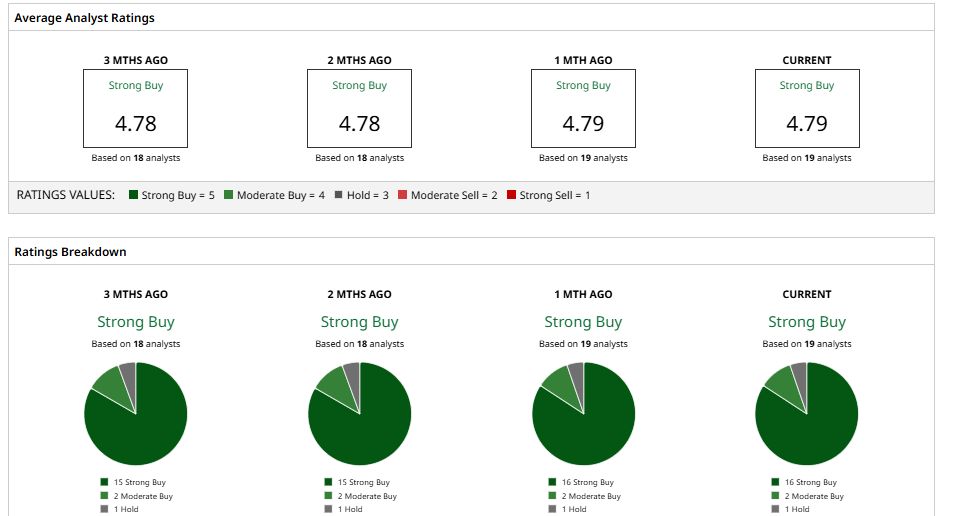
Analysts are overwhelmingly bullish.
Barchart data for TSM stock shows a consensus of “Strong Buy” with a split of 16 “Strong Buy” ratings, two “Moderate Buys,” and one “Hold.” The consensus average sits at $670, implying a massive 62% upside from current levels.
Morgan Stanley calls TSM its highest-certainty AI semiconductor play and rates it “Overweight” with an NT$3,088 target. Goldman Sachs has a “Buy” rating and a $660 target. The firm expects AI demand to carry momentum into 2027.
Barclays recently raised its target to $670 while maintaining a “Buy” rating. BofA moved its target to $620, citing 2 nanometer capacity as a sales and margin driver. The message is consistent. TSM is expensive for a reason. But it's not overvalued relative to its growth.
All told, TSM isn't a flashy stock. It doesn't make headlines like Nvidia. It just makes the chips that make Nvidia possible. The Texas hub adds another layer to an already formidable US footprint. For long-term investors, the story remains simple. The world needs advanced chips. Taiwan Semi builds most of them. That's a pretty good business to own.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Goldman Sachs Just Upgraded CoreWeave Stock, but Leverage Raises Red Flags for Nervous Investors A $4 Billion Reason to Buy TSMC Stock Now Charlie Munger Said He Was Still Buying Apartment Complexes ‘To Give Me Something To Do’ but Ran Them the Opposite Way, ‘It’s All Deferred Gratification’ Elon Musk’s Midterm Spending Reaches $90 Million Despite Previously Saying He Has ‘Done Enough’ Political Spending