

Western Digital Corporation (WDC) is set to unveil its first-quarter fiscal 2027 results on Thursday, Oct. 22, after the market closes, and Wall Street is expecting another strong showing. The data storage maker has beaten analysts’ estimates in each of the past four quarters, setting the bar rather high for its next performance.
And investors are paying attention for good reason. Artificial intelligence (AI) may be grabbing the headlines, but behind every chatbot, cloud application, and data-heavy workload sits a less glamorous necessity—storage. As tech giants expand data centers and businesses generate mountains of digital information, demand for high-capacity hard drives continues to build. Western Digital is right in the middle of that opportunity, with favorable pricing, improving demand visibility, and new storage technologies supporting its growth prospects.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Management is also working to squeeze more capacity out of its existing infrastructure, improve manufacturing productivity, and expand its advanced drive lineup. That could mean stronger margins and healthy cash generation if execution stays on track. Of course, this is not a guaranteed victory lap. Ramping next-generation drives, meeting customer qualification timelines, and fending off HDD rivals won’t be easy. Flash-based alternatives add another challenge.
So, with expectations running high, can Western Digital deliver another earnings surprise, or will competition and execution risks spoil the party? Let’s take a closer look before the company reports.
About Western Digital Stock
Founded in 1970 and headquartered in San Jose, California, Western Digital is a major player in the data storage industry, with a market capitalization of $136.4 billion. The company designs and sells hard disk drive (HDD)-based storage solutions under its Western Digital and WD brands, catering to everyone from cloud service providers and large enterprises to everyday consumers.
Its product lineup includes internal and external hard drives, data center storage platforms, and network-attached storage (NAS) systems. Backed by extensive research and development and a strong patent portfolio in magnetic recording technology, Western Digital continues to develop higher-capacity storage solutions for an increasingly data-hungry world. Its global distribution network spans original equipment manufacturers, retailers, and channel partners.
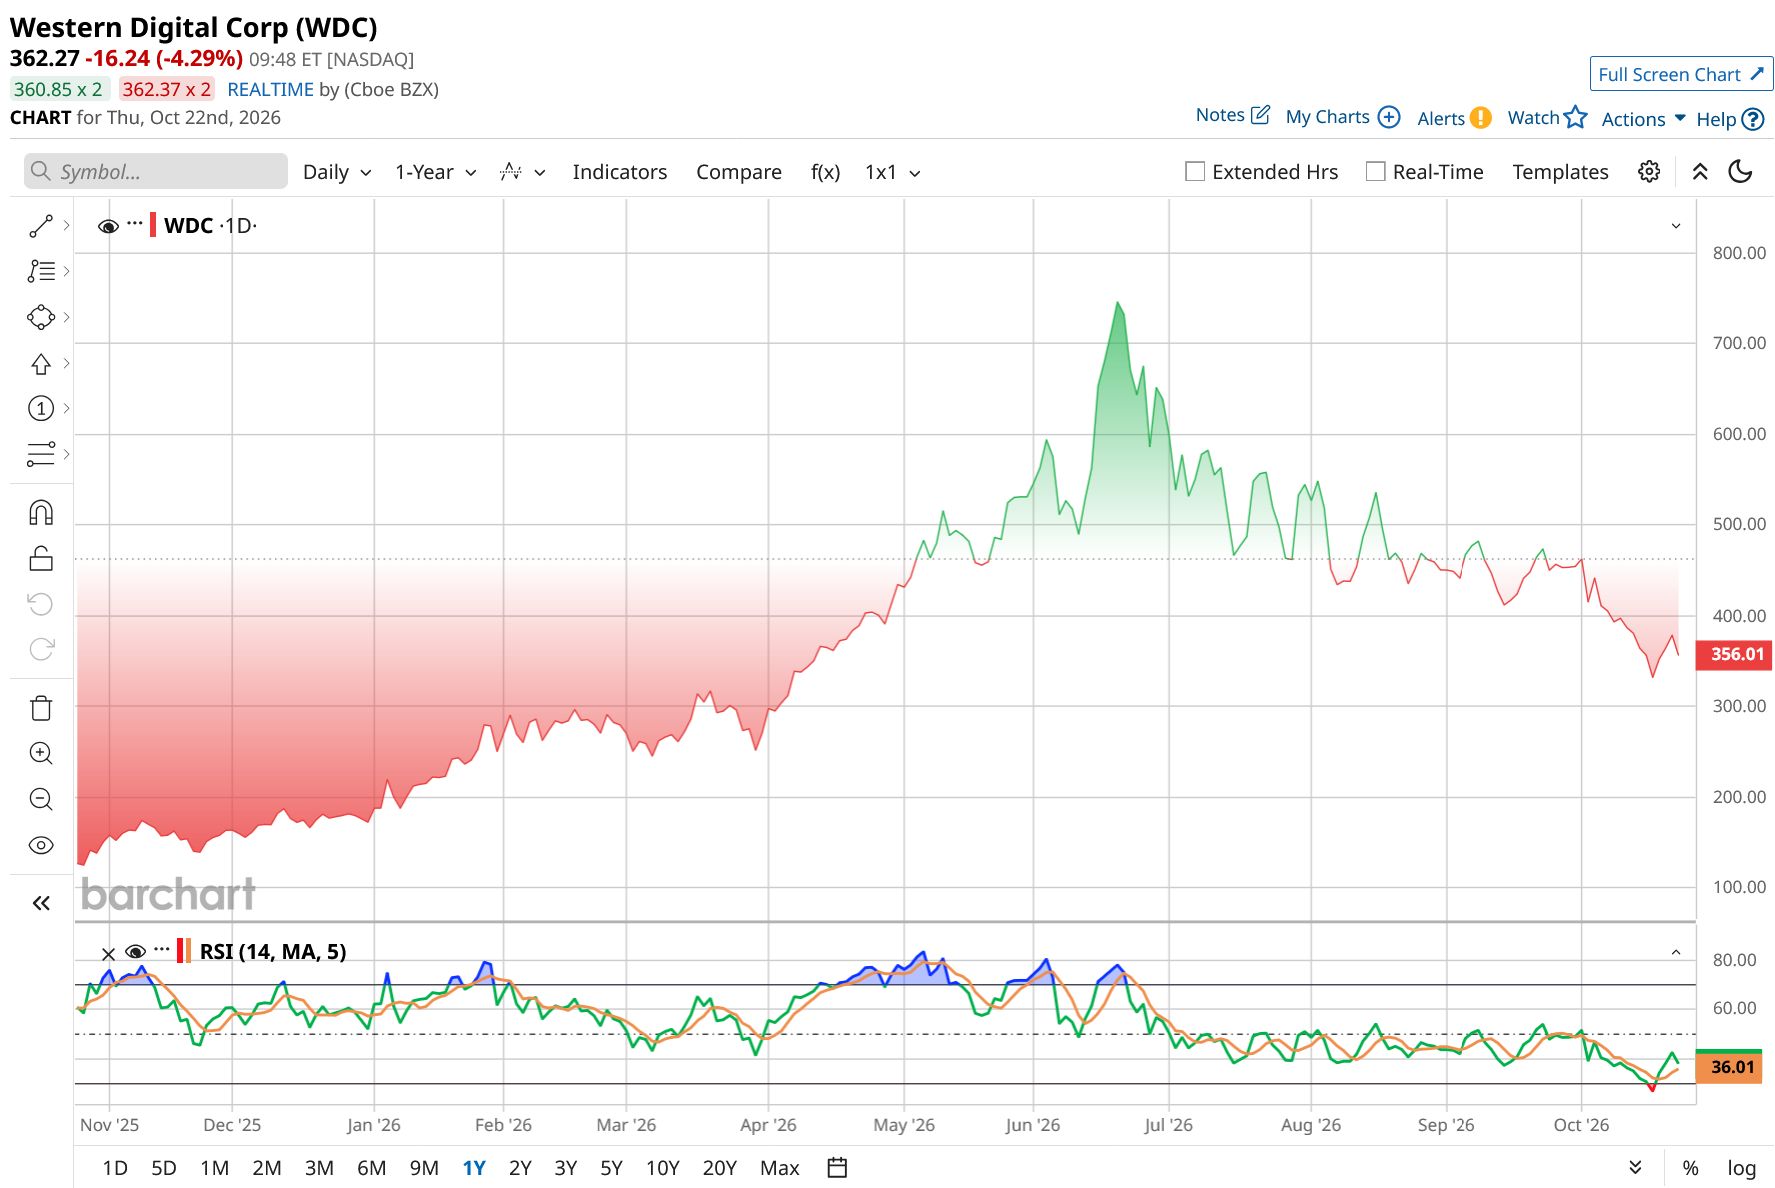
And investors have certainly taken notice. Over the past 52 weeks, WDC stock has surged 200%, while shares have gained 107% on a year-to-date (YTD) basis, reflecting strong investor enthusiasm for the company’s role in the AI and cloud storage boom. The rally, however, has not exactly been a smooth ride.
WDC stock hit a record high of $799.87 on June 18, but the mood has since shifted. Shares now trade 55% below that peak, following a sharp correction driven by profit-taking, concerns about gross margins, and broader industry supply worries. On Aug. 6, the stock tumbled 13% after management’s fiscal Q1 2027 gross margin outlook fell short of expectations set by rival Seagate (STX). Since then, the pressure has continued, with shares plunging 36% over the past three months and 23% in just the past month.
With earnings around the corner, investors will be watching closely to see whether strong storage demand can help restore the stock’s momentum.
 www.barchart.com
Valuation-wise, Western Digital presents a mixed picture. The stock trades at around 17.6 times forward-adjusted earnings, below both the sector average and its historical median, suggesting its earnings multiple looks relatively reasonable. However, its price-to-sales (P/S) ratio of 7.06 times sits above both benchmarks, indicating investors are paying a premium for every dollar of revenue.
As for dividends, the company returns some cash to shareholders, with quarterly payments translating to an annualized payout of about $0.60 per share. However, its dividend yield is just 0.16%, so income seekers probably won’t get too excited.
A Snapshot of Western Digital’s Q4 Earnings Report
Western Digital wrapped up fiscal 2026 on a strong note, and the numbers indicate that demand for data storage is giving the company plenty to celebrate. In August, the data storage company reported fourth-quarter fiscal 2026 adjusted EPS of $3.56, beating Wall Street’s expectations. The bottom line jumped 109% year-over-year (YoY) and 31% sequentially, exceeding even the high end of management’s guidance.
Revenue climbed 44% YoY to $3.75 billion and surpassed analysts’ estimates. For the full fiscal year, revenue grew 36% to $12.9 billion. The growth reflects more than just a good quarter. As AI applications expand and cloud providers build out their infrastructure, the need to store increasingly large volumes of data continues to rise. Western Digital is benefiting from that demand, supported by its technology roadmap, operational execution, and favorable pricing environment.
Cloud remained the biggest growth engine, accounting for 89% of total revenue. Sales from this segment surged 43% YoY to $3.3 billion, fueled by demand for higher-capacity nearline drives and favorable pricing. Client revenue, representing 6% of the total, rose 61% to $225 million, while Consumer revenue increased 38% to $187 million.
The company shipped 231 exabytes of storage during the quarter, up 22% YoY, driven by strong demand for nearline hard drives and solid growth in non-nearline products. It also began shipping its next-generation ePMR hard drives, offering capacities of up to 40 terabytes, with volume shipments expected to ramp up over the coming quarters.
Cash generation was another bright spot. As of July 3, 2026, Western Digital held $1.6 billion in cash and cash equivalents against $1.1 billion in debt. It generated $1.4 billion in operating cash flow, while free cash flow climbed 90% YoY to $1.3 billion. Plus, the company remains committed to consistently returning FCF to shareholders, as it has done over the past four to five quarters, through a combination of dividend payments and share repurchases. During the quarter, the company paid $54 million in dividends and repurchased $1 billion worth of shares.
Looking ahead, management expects the momentum to continue into the first quarter of fiscal 2027. Western Digital projects adjusted revenue of $4.1 billion, plus or minus $100 million, implying 45% YoY growth. Adjusted earnings are forecast at $4 per share, with a $0.15 margin either way.
While the company is all set to release its quarterly report soon, Wall Street’s expectations are broadly in line with management’s outlook, with analysts anticipating $4.15 billion in revenue and earnings of $3.99 per share, up 143.3% YoY. Looking further ahead, fiscal 2027 EPS is expected to double to $19.65, followed by another 73.8% increase to $34.15 in fiscal 2028.
With AI and cloud infrastructure continuing to drive storage demand, Western Digital appears well positioned to capitalize on the opportunity. The question is whether its upcoming results can keep pace with the increasingly optimistic expectations.
What Do Analysts Expect for WDC Stock?
Wall Street is bullish on Western Digital, but analysts are also keeping an eye on how quickly the company can ship more storage capacity. On Oct. 21, Bank of America raised its price target on WDC stock to $800 from $720 and kept the “Buy” rating, even as it trimmed its expectations for near-term shipment growth. Analyst Wamsi Mohan expects first-quarter exabyte shipments to rise 21% YoY, below management’s longer-term target of roughly 25%.
However, there’s a silver lining. BofA expects the average price per terabyte to climb 24% annually, as demand for hard drives continues to outstrip supply. That pricing power could help Western Digital protect its margins, with the bank forecasting a 56.4% Q1 gross margin, slightly above management’s 55% to 56% guidance. For the December quarter, BofA sees margins approaching 59%.
The bank also raised its fiscal 2027 EPS estimate to $22.37 from $19.17, supporting its higher price target despite lowering its valuation multiple to 16 times earnings from 19 times. Meanwhile, Western Digital’s 40 TB ePMR drive has qualified with two customers and is entering volume production. BofA expects the transition to accelerate shipment growth in the second half of fiscal 2027.
Morgan Stanley lowered its price target on WDC to $643 from $676 on Tuesday, citing uncertainty around competition and AI funding, despite improving hard-drive fundamentals. However, analysts led by Erik Woodring see the recent selloff as a buying opportunity and maintain an “Overweight” rating on WDC.
Industry checks point to stronger storage demand and a potential 400-exabyte supply shortfall in 2027 and 2028. Spot HDD prices running two to five times contracted levels could further boost margins. Morgan Stanley expects WDC to beat September-quarter estimates and deliver stronger December-quarter guidance, with its earnings forecasts roughly 10% above consensus. The firm remains bullish ahead of earnings.
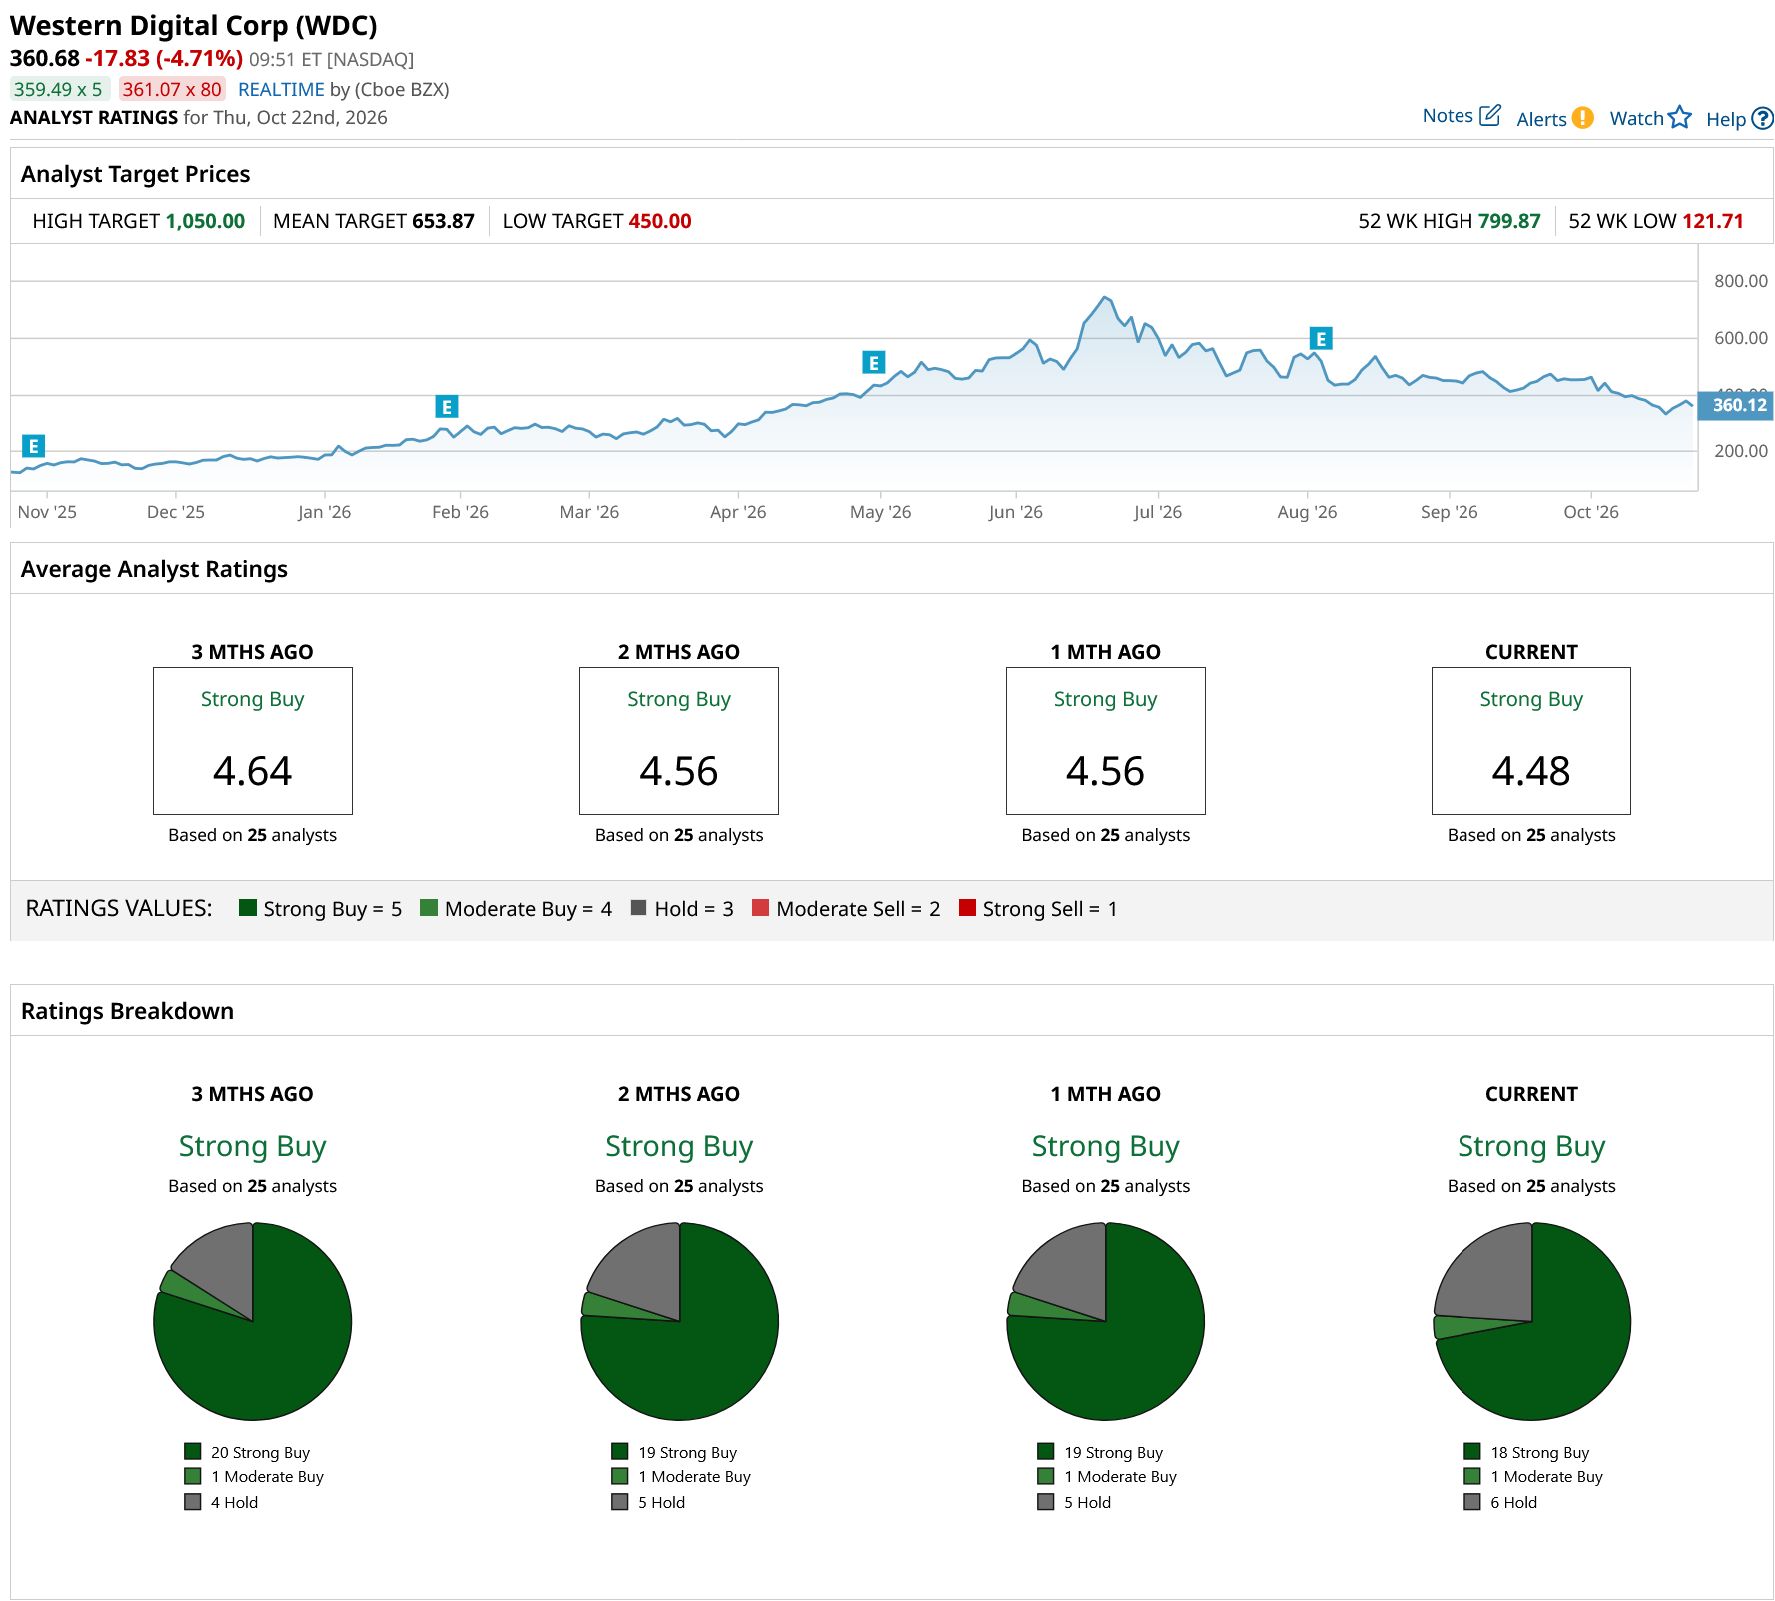
The consensus rating on WDC stock remains at “Strong Buy.” Among 25 analysts covering the stock now, 18 advise a “Strong Buy,” one suggests a “Moderate Buy,” and six analysts are playing it safe with a “Hold” rating.
Even as the stock slides, analysts remain bullish. The average target of $653.87 signals nearly 82% rebound potential, and the Street-high target of $1,050 suggests that WDC stock could rise as much as 191%.
 www.barchart.com
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Deutsche Bank Wants You to Buy the Dip in CoreWeave Stock Dear Western Digital Stock Fans, Mark Your Calendars for October 22 With Robust Growth, Palantir Stock Is Worth Considering at a Premium EBAY Stock Layoffs: What to Know as eBay Plans Job Cuts for Second Time This Year