

QUALCOMM Incorporated (QCOM) is a leading semiconductor and wireless technology company headquartered in San Diego. The company is best known for designing Snapdragon processors and modem chips used in smartphones, PCs, automotive systems, and connected devices worldwide. Qualcomm has increasingly expanded beyond its traditional handset business into artificial intelligence infrastructure, automotive technology, edge computing, and data center chips. Qualcomm currently has a market cap of $187.8 billion, making it one of the world’s largest semiconductor companies.
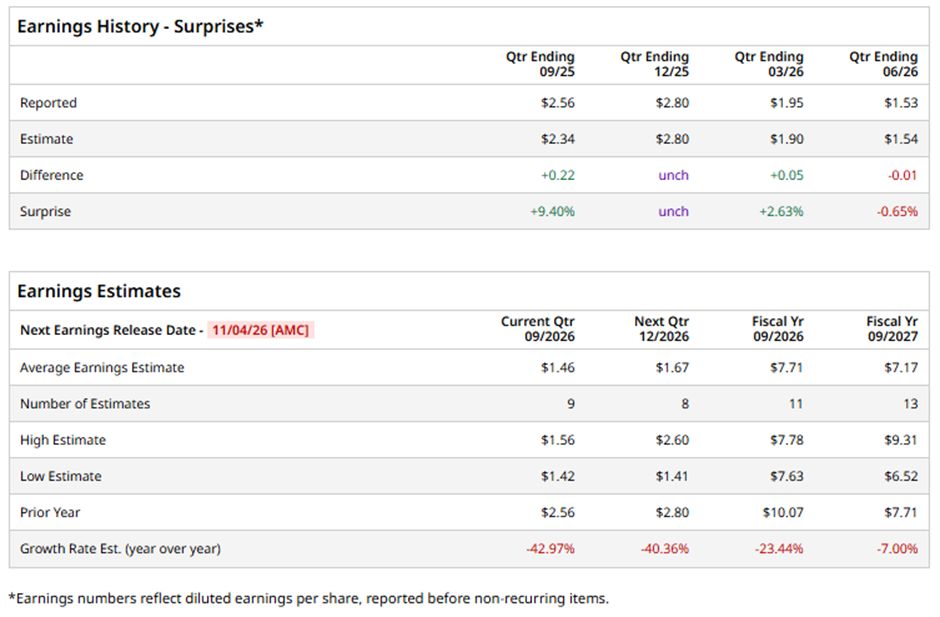
The semiconductor and equipment giant is scheduled to release its fiscal Q4 2026 earnings results on Wednesday, Nov. 4, 2026, after the close of the market. Ahead of the event, analysts expect QCOM to report a profit of $1.46 per share, down 43% from $2.56 per share in the year-ago quarter. The company has surpassed or met Wall Street’s EPS estimates in three of the trailing four quarters, while missing slightly in the last quarter.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect QCOM to report EPS of $7.71, down 23.4% from $10.07 in fiscal 2025. Plus, its EPS is expected to decline another 7% year-over-year (YOY) to $7.17 in fiscal 2027.
 www.barchart.com
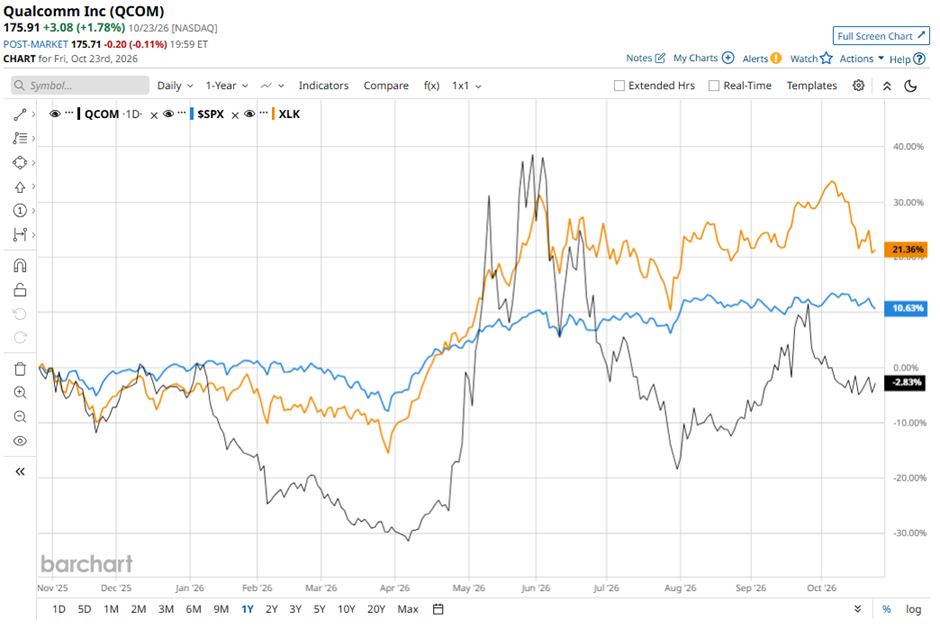
QCOM stock has underperformed the S&P 500 Index’s ($SPX) 13.1% gains over the past 52 weeks, with shares up 3.5% during this period. Similarly, it lagged behind the State Street Technology Select Sector SPDR ETF’s (XLK) 26.8% returns over the same time frame.
 www.barchart.com
Qualcomm stock has underperformed as investors remain concerned about weakness in its core smartphone business, rising semiconductor input costs and the faster-than-expected loss of Apple-related revenue. Qualcomm has warned that higher costs for wafers, memory, packaging and testing are squeezing margins, while handset revenue has been hurt by weaker demand and changes in premium smartphone chip mixes. The company also expects Apple-related revenue to decline sharply as Apple accelerates its shift toward internally developed modems.
More recently, Qualcomm announced plans for a global workforce reduction, underscoring concerns about weakening consumer-electronics demand. These headwinds have overshadowed optimism surrounding Qualcomm’s expansion into AI infrastructure and data centers, where growth is expected to take time to offset pressure on the traditional handset business.
Analysts’ consensus opinion on QCOM stock is fairly bullish, with a “Moderate Buy” rating overall. Out of 34 analysts covering the stock, 10 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” 18 give a “Hold,” one advocates a “Moderate Sell,” and three recommend a “Strong Sell.” QCOM’s average analyst price target is $199.38, indicating a potential upside of 13.3% from the current level.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Microsoft May Be the Only Hyperscaler to Stay Cash-Flow Positive. What It Means for MSFT Stock Nvidia vs. Broadcom: One Grew AI Revenue 221% Last Quarter. The Other Grew 117%. Micron’s Taiwan Unit Reached a Deal With the Taichung Union. Here’s What to Know. IBM’s CEO Just Issued a Warning Message on AI Spending. He Ended Up Hurting His Own Stock.