

Snowflake (SNOW) recently borrowed $3.75 billion from big investors, more than the $3.5 billion it initially planned to raise. The unusual part is that Snowflake pays no interest on the loan; instead, the lenders get the option to trade the loan for Snowflake shares later. For the loans due in 2029, swapping into shares only makes sense if the stock rises above about $500. That’s roughly 52.5% higher than where it traded when the deal was set.
That’s the part that caught my attention. Big investors agreed to lend billions of dollars without earning any interest, betting that SNOW stock climbs more than 50%. The latest results support that bet. Product revenue rose 37% year-over-year (YOY) to $1.49 billion in the second quarter of fiscal 2027. The period was the third-straight quarter of faster growth, helped by rising artificial intelligence (AI) revenue. Existing customers spent 26% more than a year earlier, and management raised its full-year product revenue forecast to $6.07 billion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Snowflake Stock
Snowflake provides a cloud-based data platform for various organizations in the U.S. and abroad. The company's AI Data Cloud allows businesses to bring data from different sources together, gain insights, build data-driven applications, and use AI to solve business problems. Snowflake operates seamlessly across major cloud providers including Amazon's (AMZN) Amazon Web Services, Microsoft (MSFT) Azure, and Alphabet's (GOOGL) Google Cloud. Founded in 2012, the company is headquartered in Menlo Park, California.
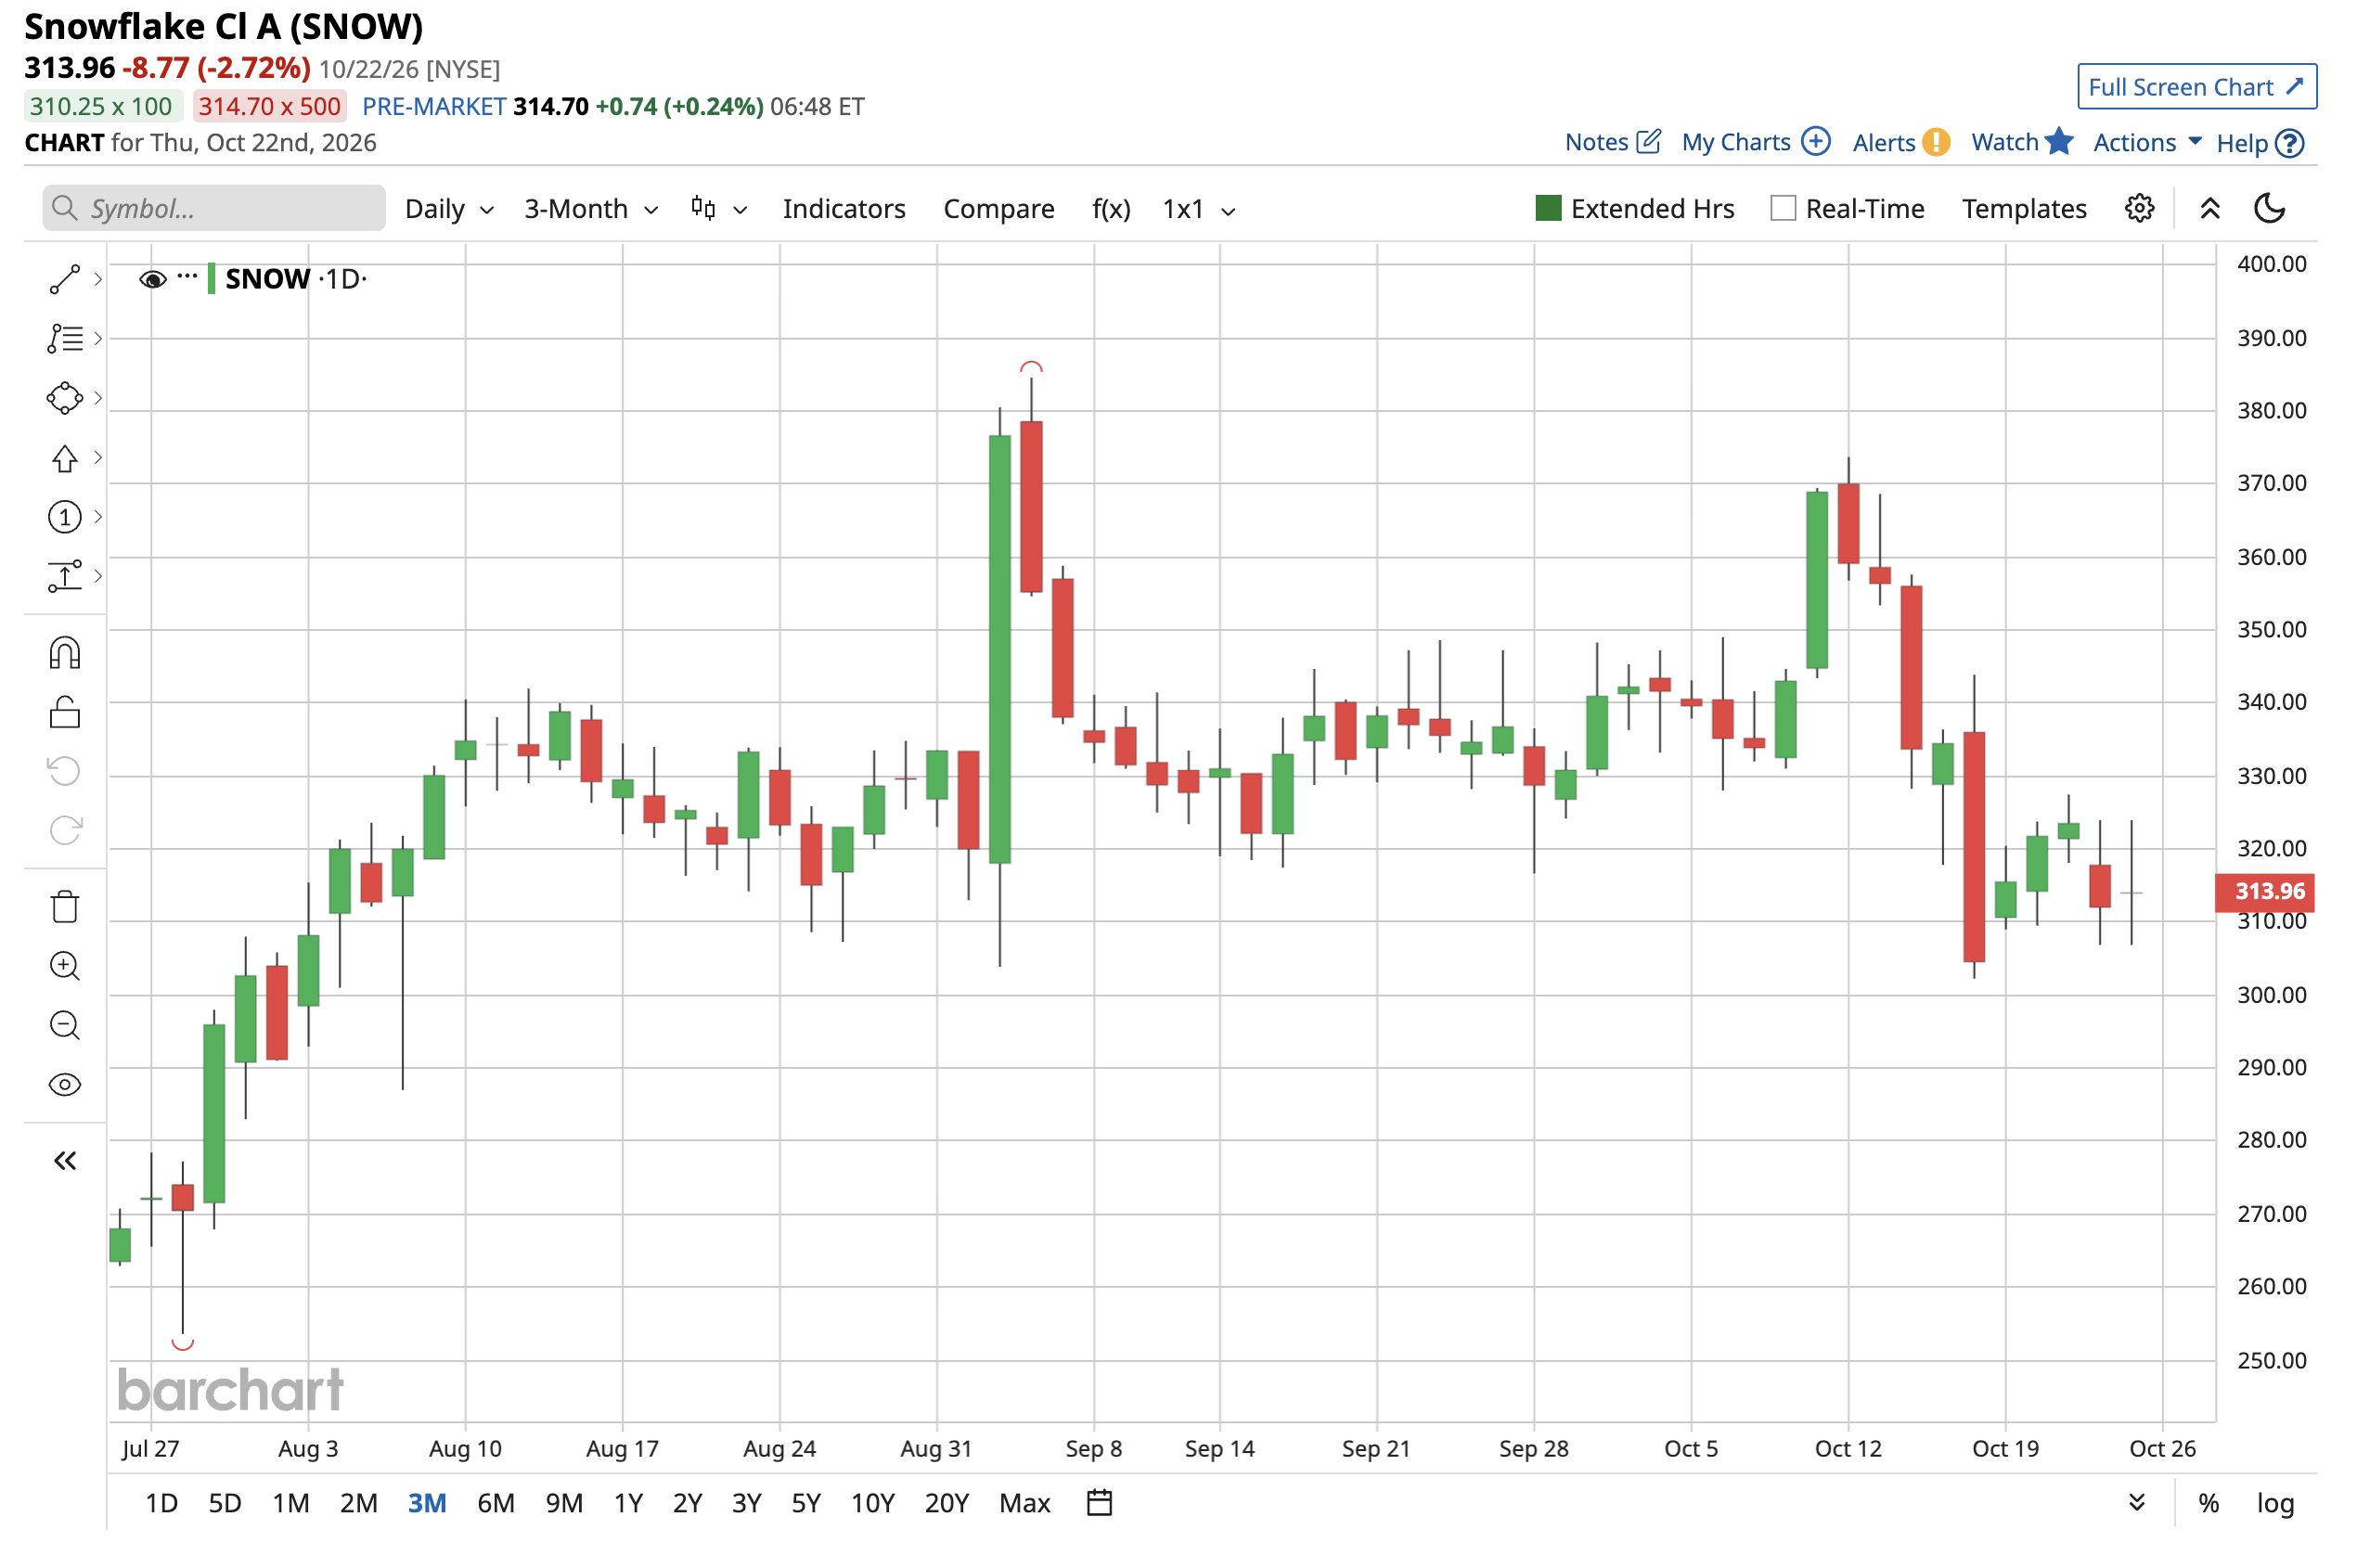
SNOW stock has surged 30% over the past year, although the path has been far from smooth. Shares slid from the mid-$200 range in late 2025 to a 52-week low of $118.30 in April 2026, then reversed sharply. By contrast, the S&P 500 ($SPX) has gained about 13% over the same period. SNOW stock has outperformed the broader market, suggesting that company-specific factors — not just overall market sentiment — have driven its share price.
 www.barchart.com
SNOW Stock Is Expensive
Snowflake’s forward price-to-earnings (P/E) ratio of about 137 times is undoubtedly steep, although it does sit 62% below its estimated five-year average of about 366 times. Meanwhile, the forward price-to-sales (P/S) ratio currently comes in at 23.6 times.
The EPS outlook helps explain the high multiples. Analysts expect earnings to jump 57% in fiscal 2027, then grow 40% YOY in fiscal 2028. At that pace, the stock's P/E ratio could drop to comparatively more reasonable levels.
Snowflake Beats Earnings Estimates as AI Demand Accelerates
Snowflake reported Q2 fiscal 2027 earnings on Sept. 2, and the release helps explain why investors have been willing to pay a premium. Revenue rose 35% YOY to $1.55 billion, exceeding Wall Street’s $1.48 billion estimate. Adjusted earnings reached $0.62 per share, clearing the $0.45 consensus forecast. Snowflake also produced $237 million in adjusted operating income, ahead of estimates of $185.9 million and equating to a 15.3% margin. The company still reported a GAAP operating margin of -17%. However, that was a considerable improvement from -29.7% a year earlier.
Looking forward, Snowflake raised its full-year product revenue forecast to $6.07 billion, representing 36% YOY growth. The company also guided for Q3 product revenue of $1.588 billion to $1.593 billion, implying 37% to 38% YOY growth. The higher outlook reflects strength in both the core business and AI products. Finally, Snowflake lifted its full-year non-GAAP operating margin guidance to 14.5% from 13.5%.
What Do Analysts Think of SNOW Stock?
JPMorgan analyst Samik Chatterjee recently reiterated a “Buy” rating on SNOW stock, pointing to a combination of factors related to Snowflake’s strengthening growth trajectory and platform adoption. In addition, Truist Financial maintained a “Buy” rating on Snowflake stock with a price target of $425.
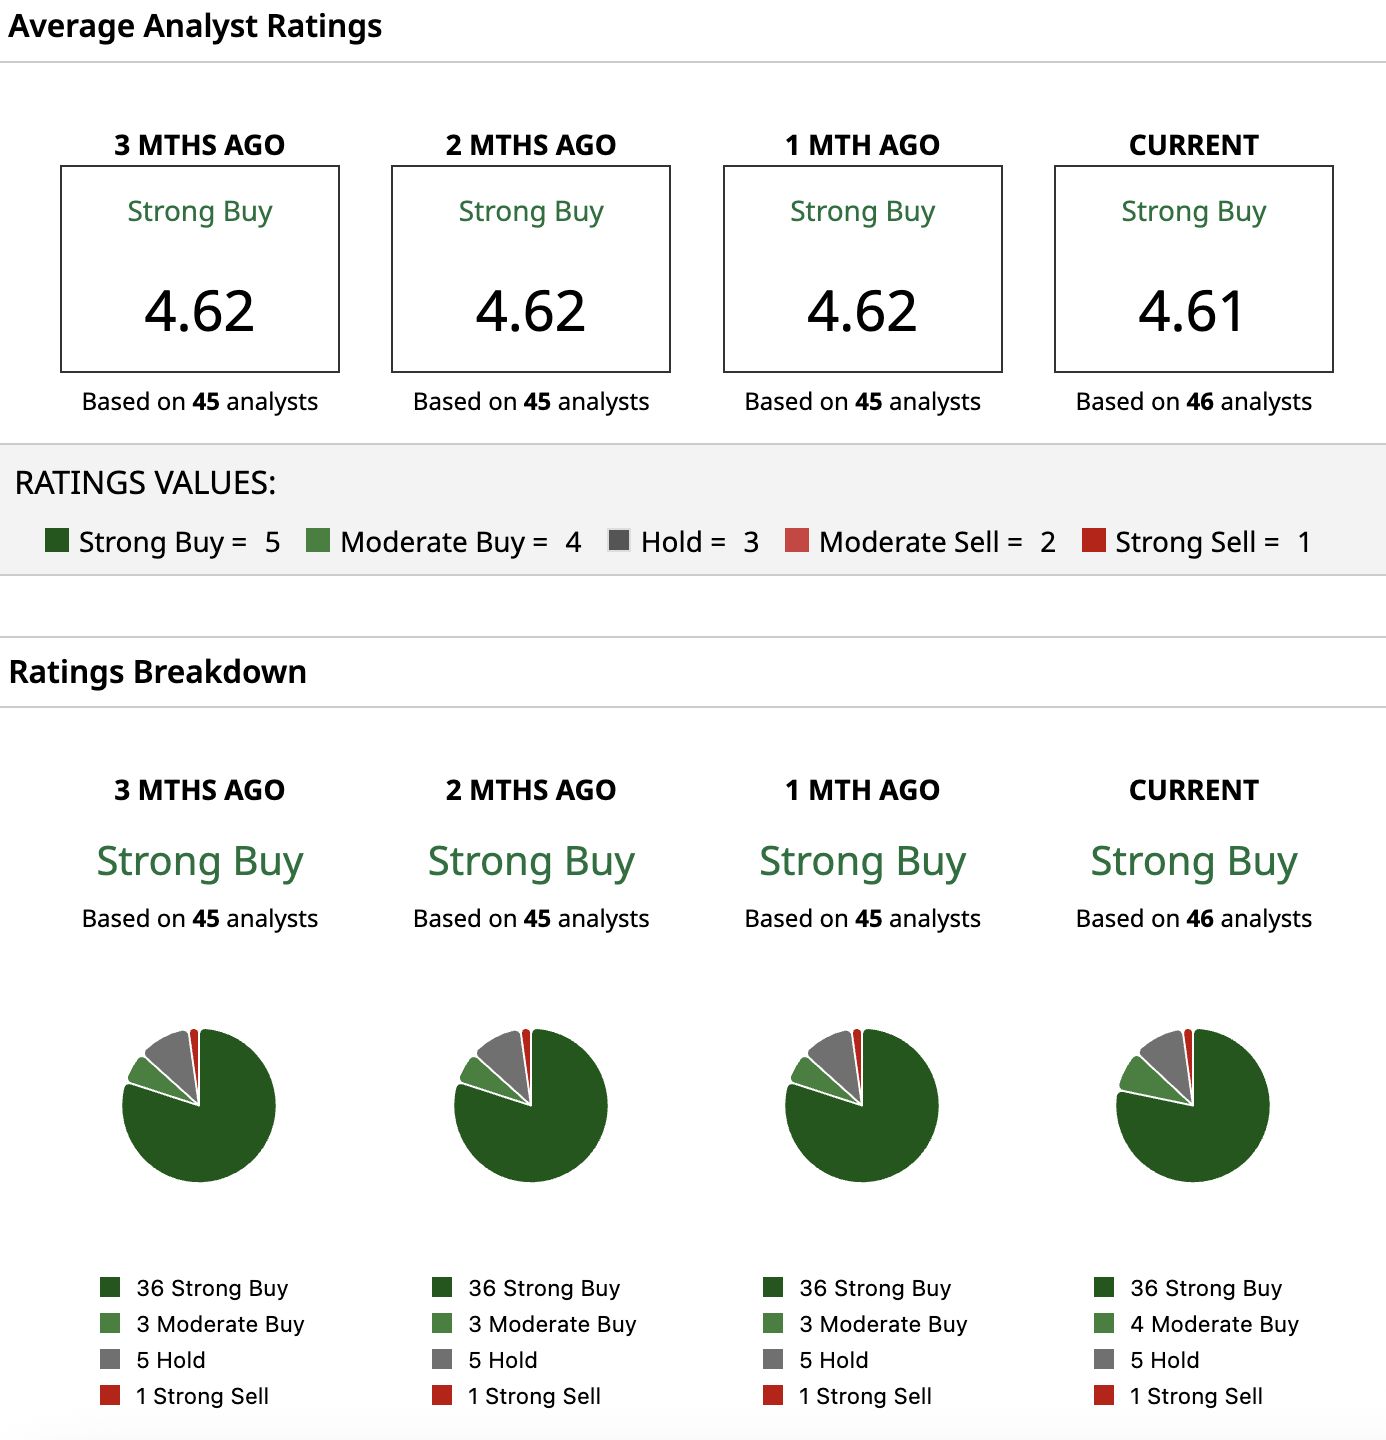
Broader analyst sentiment remains firmly positive. Based on 46 analysts with coverage, Snowflake has a consensus “Strong Buy” rating overall. The average price target stands at $429.04, pointing to potential upside of about 29% from current levels. Meanwhile, the Street-high price target of $525 reflects potential upside of 57% from here.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Let’s Be Like the Amish and Let’s Only Use Al for Certain Things’ — Bill Gates Says He’ll Leave It to the Younger Generation to Figure Out in the Next 20 Years Dear eBay Stock Fans, Mark Your Calendars for October 28 Snowflake’s P/E Is 62% Below Its Average. Smart Money Is Lending It Billions At 0% Interest. How to Manage Your Portfolio in a Volatile Market, Protect Your Nest Egg, and Profit from the Turmoil