

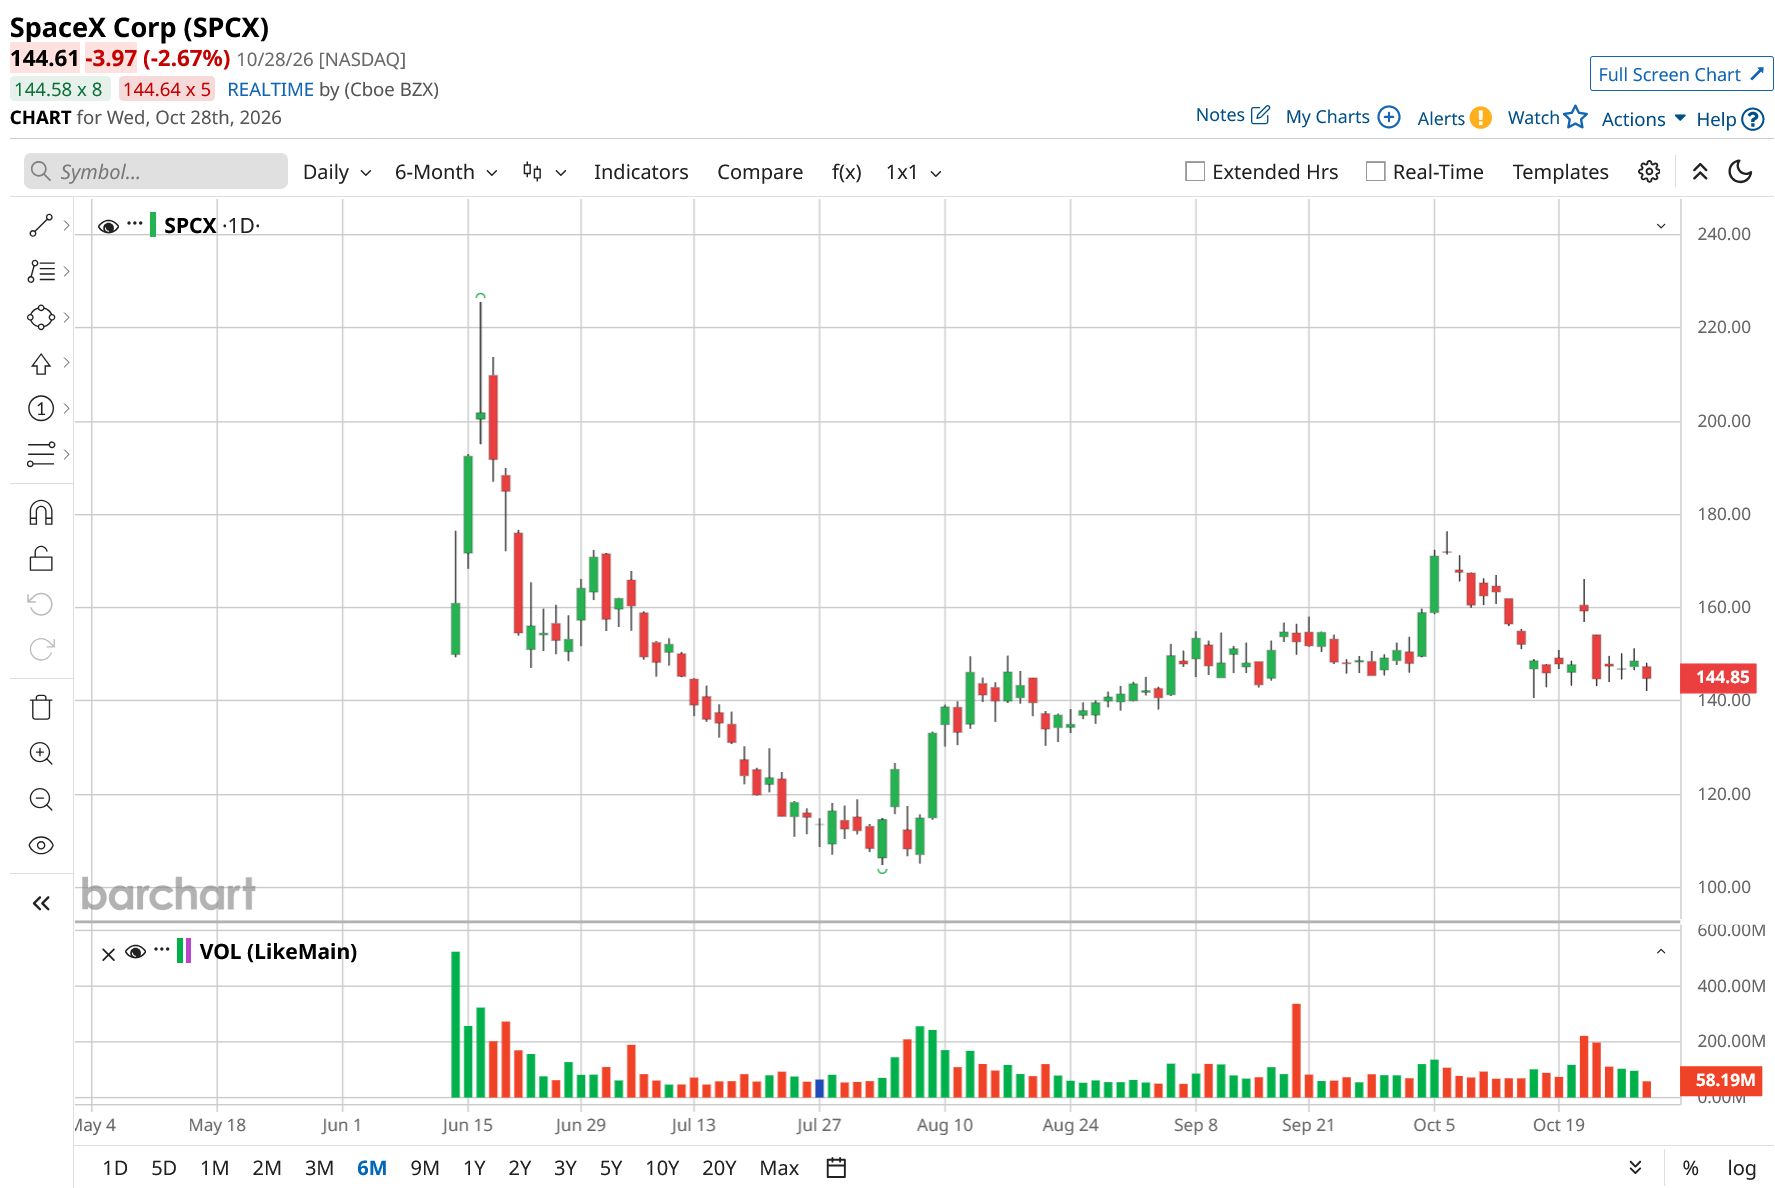
Elon Musk's SpaceX (SPCX) is reportedly seeking to obtain at least 80,000 U.S. cell sites as it looks to launch a mobile network. Showing that it's serious about the plan, the company is in talks about the matter with “at least one big tower owner,” Crown Castle (CCI), Bloomberg reported. But it will probably take many years for a mobile network to deliver a positive return on investment (ROI) for SpaceX, so the initiative could take a long time to boost SPCX stock.
Moreover, in order to make the undertaking work, the company will have to overcome multiple, tough obstacles, and there are some reasons to believe that the venture will not succeed at all. On the other hand, SpaceX does have some strengths that could enable its mobile network to eventually thrive. Still, in light of the likely long ROI time of the project and the difficulty of predicting whether it will succeed, the mobile network initiative does not increase the overall appeal of SPCX stock.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
And given the uncertain outlook of a number of SpaceX's other ventures, along with its enormous valuation, it does not seem like a good stock to buy at this point.
 www.barchart.com
A Long ROI, Steep Obstacles, and Reasons to Be Skeptical
To launch a mobile network, the company will have to spend vast amounts of money on spectrum and cell sites. T.D. Cowen analysts estimate it would cost over $80 billion. Given the high marketing budgets that the incumbents—AT&T (T), Verizon (VZ), and T-Mobile (TMUS)—possess, along with the significant switching costs that consumers have when it comes to joining a new carrier, Musk's firm will have to spend a great deal on marketing and will likely have to undercut the incumbents when it comes to prices. Due to these points, I believe that it will take, at best, a very long time for the venture to deliver a positive ROI.
Further, it may not be easy to attract customers to the network at all. Musk's political activism has alienated a large segment of U.S. consumers, while the technical problems that Tesla (TSLA) has had with its robotaxis and Cybertruck suggest that SpaceX's mobile network may not experience smooth sailing on the technical side in its initial stages. Nor is Tesla's overall growth very inspiring: its deliveries for 2023, 2024, and 2025 came in at 1.8 million, 1.79 million, and 1.64 million, respectively. Finally, Starlink, SpaceX's satellite internet service, has been in business for several years and has a presence in many markets globally but only has 13.6 million subscribers. By comparison, Comcast (CMCSA) had 28.3 million residential broadband customers in the U.S. as of the end of last quarter.
Reasons to Believe That the Mobile Network Venture May Eventually Succeed
To Musk's credit, he did build Tesla into a major, successful, profitable firm, while SpaceX's satellite business has been quite successful, launching many spacecraft with an excellent safety and launch-success record. What's more, the tycoon, due to his status as one of the world's most famous people, can obtain a great deal of free media coverage for his companies. The latter advantage should help the mobile network recruit customers.
SpaceX Has Other Tough Tasks and a Sky-High Valuation
As I've pointed out in past columns, SpaceX's AI agent, Grok, faces steep competition from, among others, ChatGPT, Anthropic, and Alphabet (GOOG) (GOOGL). Further, SpaceX has to spend a great deal of money on buying Nvidia's (NVDA) chips to power its current data centers, and it will likely have to pay Intel (INTC) large amounts to provide the technology for its Terafab. Finally, SpaceX's space-based data centers may never materialize due to technical challenges.
On the valuation front, the shares are changing hands at a huge price-to-sales (P/S) ratio of 104x.
On the date of publication, Larry Ramer did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Just in Case You Had Pre-IPO FOMO, Anthropic S-1 Says There Might Not Be Enough Insurance in the World to Cover Rogue AI Risk Ahead of Amazon Earnings, Here's What Barchart Data Says Comes Next for AMZN Stock Tough Obstacles, Long ROI Time Make SpaceX’s Mobile Network Plan Unappealing This Dividend Powerhouse Is Heading Into Q3 Earnings With Plenty at Stake