

Memory major SK hynix's (SKHY) subsidiary, Solidigm, is contemplating an investment of $45 billion to build a NAND manufacturing plant, according to Bloomberg. Acquired by SK hynix exactly six years ago from Intel (INTC) for $9 billion, Solidigm specializes in NAND flash memory and enterprise solid-state drives (SSDs).
A supposed angle to the investment involves Solidigm seeking concessions from the U.S. government to send additional semiconductor manufacturing equipment to the former's facility in Dalian, China. Meanwhile, the proposed facility is expected to be set up in Upstate New York. However, neither SK hynix nor Solidigm has officially confirmed this.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About SK hynix
SK hynix traces its origins to 1983 and was founded by Chung Ju-yung, the well-known founder of the Hyundai Group. Now under the ownership of the SK Group, the company ranks among the world’s largest producers of semiconductor memory. Long established as a major force in DRAM and NAND flash memory, SK hynix has emerged as one of the primary beneficiaries of the artificial intelligence expansion thanks to its strong position in high-bandwidth memory chips that power AI accelerators, including Nvidia graphics processing units. The firm is widely viewed as the technology leader in the high-bandwidth memory segment and holds a strategically critical role within the global artificial intelligence supply chain.
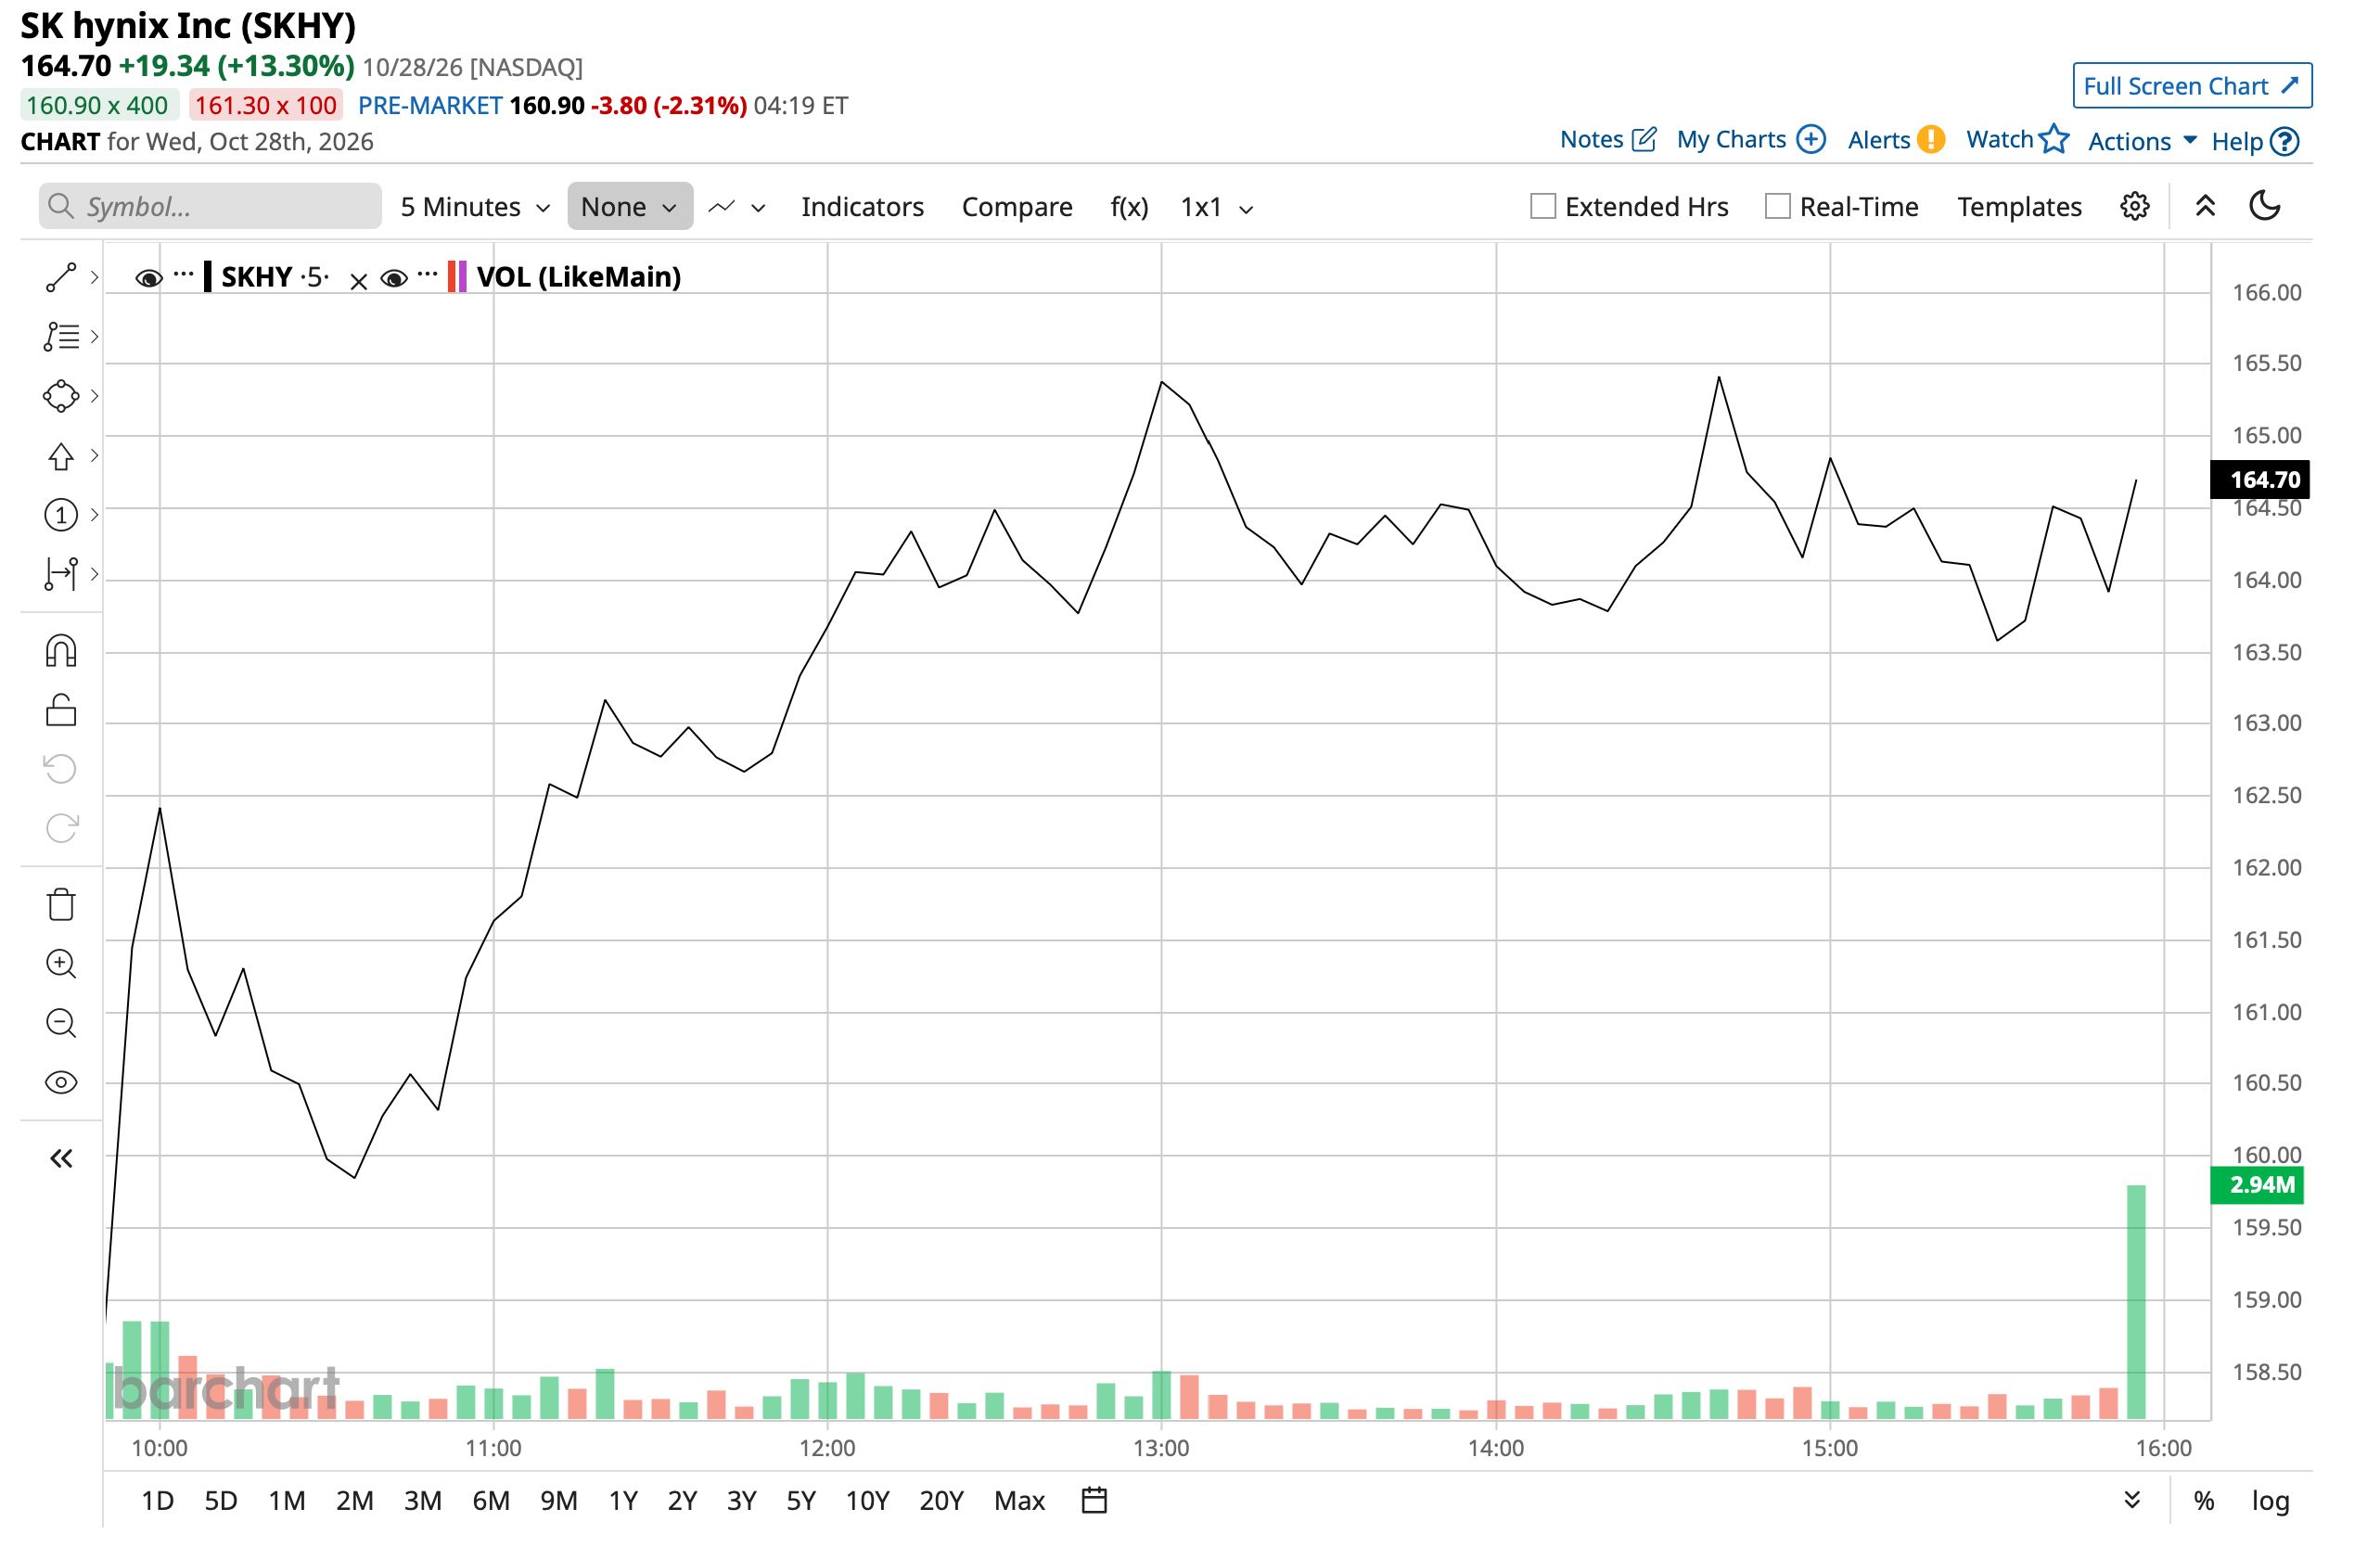
With its ADRs listed on July 10, 2026, on the Nasdaq, the company currently commands a market cap of $1.4 trillion. Notably, the ADRs recently witnessed a pop of 13.3% following record quarterly results. Each ADR represents one-tenth of an ordinary share of the company.
But what role can Solidigm's proposed investment play in SK hynix's broader strategy? Let's find out.
 www.barchart.com
Solid NAND
Prior to acquiring Solidigm, SK hynix's place in the NAND memory space was already well-established. However, what it was lacking was enterprise and data center storage capabilities. With Solidigm in its fold, that issue was resolved. What Solidigm brought to the table for SK hynix was an established SSD business, industry-leading NAND SSD technology, QLC NAND expertise, and the Dalian manufacturing facility in China.
Thus, SK hynix could combine its NAND manufacturing expertise with Intel's enterprise storage technology to compete more effectively in high-capacity SSDs used in data centers. SK hynix explicitly described this as an opportunity to strengthen its enterprise SSD capabilities, a market that is poised to reach a size of $111.29 billion by 2034, and in which SK hynix with Solidigm holds a 30.2% share, making it the second-largest player.
Meanwhile, the $45 billion expected investment would not be Solidigm's first in the country. Its first clearly announced investment initiative after its formation was a commitment to invest $100 million in research and development facilities in the Greater Sacramento region of California. The initiative focused on its headquarters in Rancho Cordova and the surrounding R&D campus. The aim was to strengthen its research capabilities, develop storage technologies, and expand its local workforce. This was strategically significant because Solidigm's business depends on developing increasingly dense, efficient, and high-capacity SSDs for enterprise customers. Research and development is therefore central to its competitiveness, particularly as AI data centers require more storage.
And this investment in R&D is leading to more product development that has the potential to not only solidify but also expand SK hynix's market share as well as challenge market leader Samsung. One of the key products is its 321-layer, 2-terabit QLC NAND. As per the company, compared with its previous QLC generation, the new technology doubled data-transfer speed, improved write performance by up to 56%, increased read performance by 18%, and improved write power efficiency by more than 23%.
Then, at Future of Memory and Storage 2026, SK hynix highlighted its PS1101 high-capacity enterprise SSD lineup, based on QLC NAND. The company said the product offered approximately 55% higher performance than the previous 176-layer generation and began sample shipments to major cloud service provider customers in August 2026.
Finally, the company also showcased 375-layer 4D NAND at the August 2026 event. Here, the technology uses wafer bonding and delivers 2.5 times the performance per watt of the previous generation. It also highlighted packaging technologies designed to increase density and improve space efficiency. Notably, SK hynix expects to begin mass production of high-performance enterprise SSDs based on this technology in the first half of 2027.
SK hynix's Record Q3
Having said that, SK hynix's latest results for Q3 2026 showcased a company that is firing on all cylinders, leading to a remarkable record-breaking showing.
The company saw quarterly sales surpassing 100 trillion won for the first time as revenues came in at 104.62 trillion won, a 32% growth from the previous year. DRAM continued to be the biggest revenue segment of the company at 75%, followed by NAND at 24%.
Operating profits followed a similar trajectory, growing by 38% in the same period to 83.33 trillion won, as operating margins expanded to 80% from 47% in the prior year. EPS jumped as well to 54,454 won per share from 17.850 won per share in the year-ago period.
Crucially, the company expects demand to outpace supply through 2030, as the company secured long-term agreements with 14 major customers, covering more than 50% of its total production capacity for 2027 and 2028.
Meanwhile, cash flow from operating activities rose by 281.3% over the past year to 54.8 trillion as the company closed the quarter with a mammoth cash balance of 114.5 trillion won, much higher than its short-term debt levels of 4.56 trillion won.
Shareholder activities also remained robust as the company returned 14 trillion won as dividends, with plans to return 100 trillion won in FY 2026.
Shifting focus to valuations, SKHY ADR is trading at a discount to its peers. Its forward P/E, P/S, and P/CF of 5.49, 2.84, and 5.94 are all below the sector medians of 29.81, 3.37, and 20.43, respectively.
Analyst Opinion on SKHY Stock
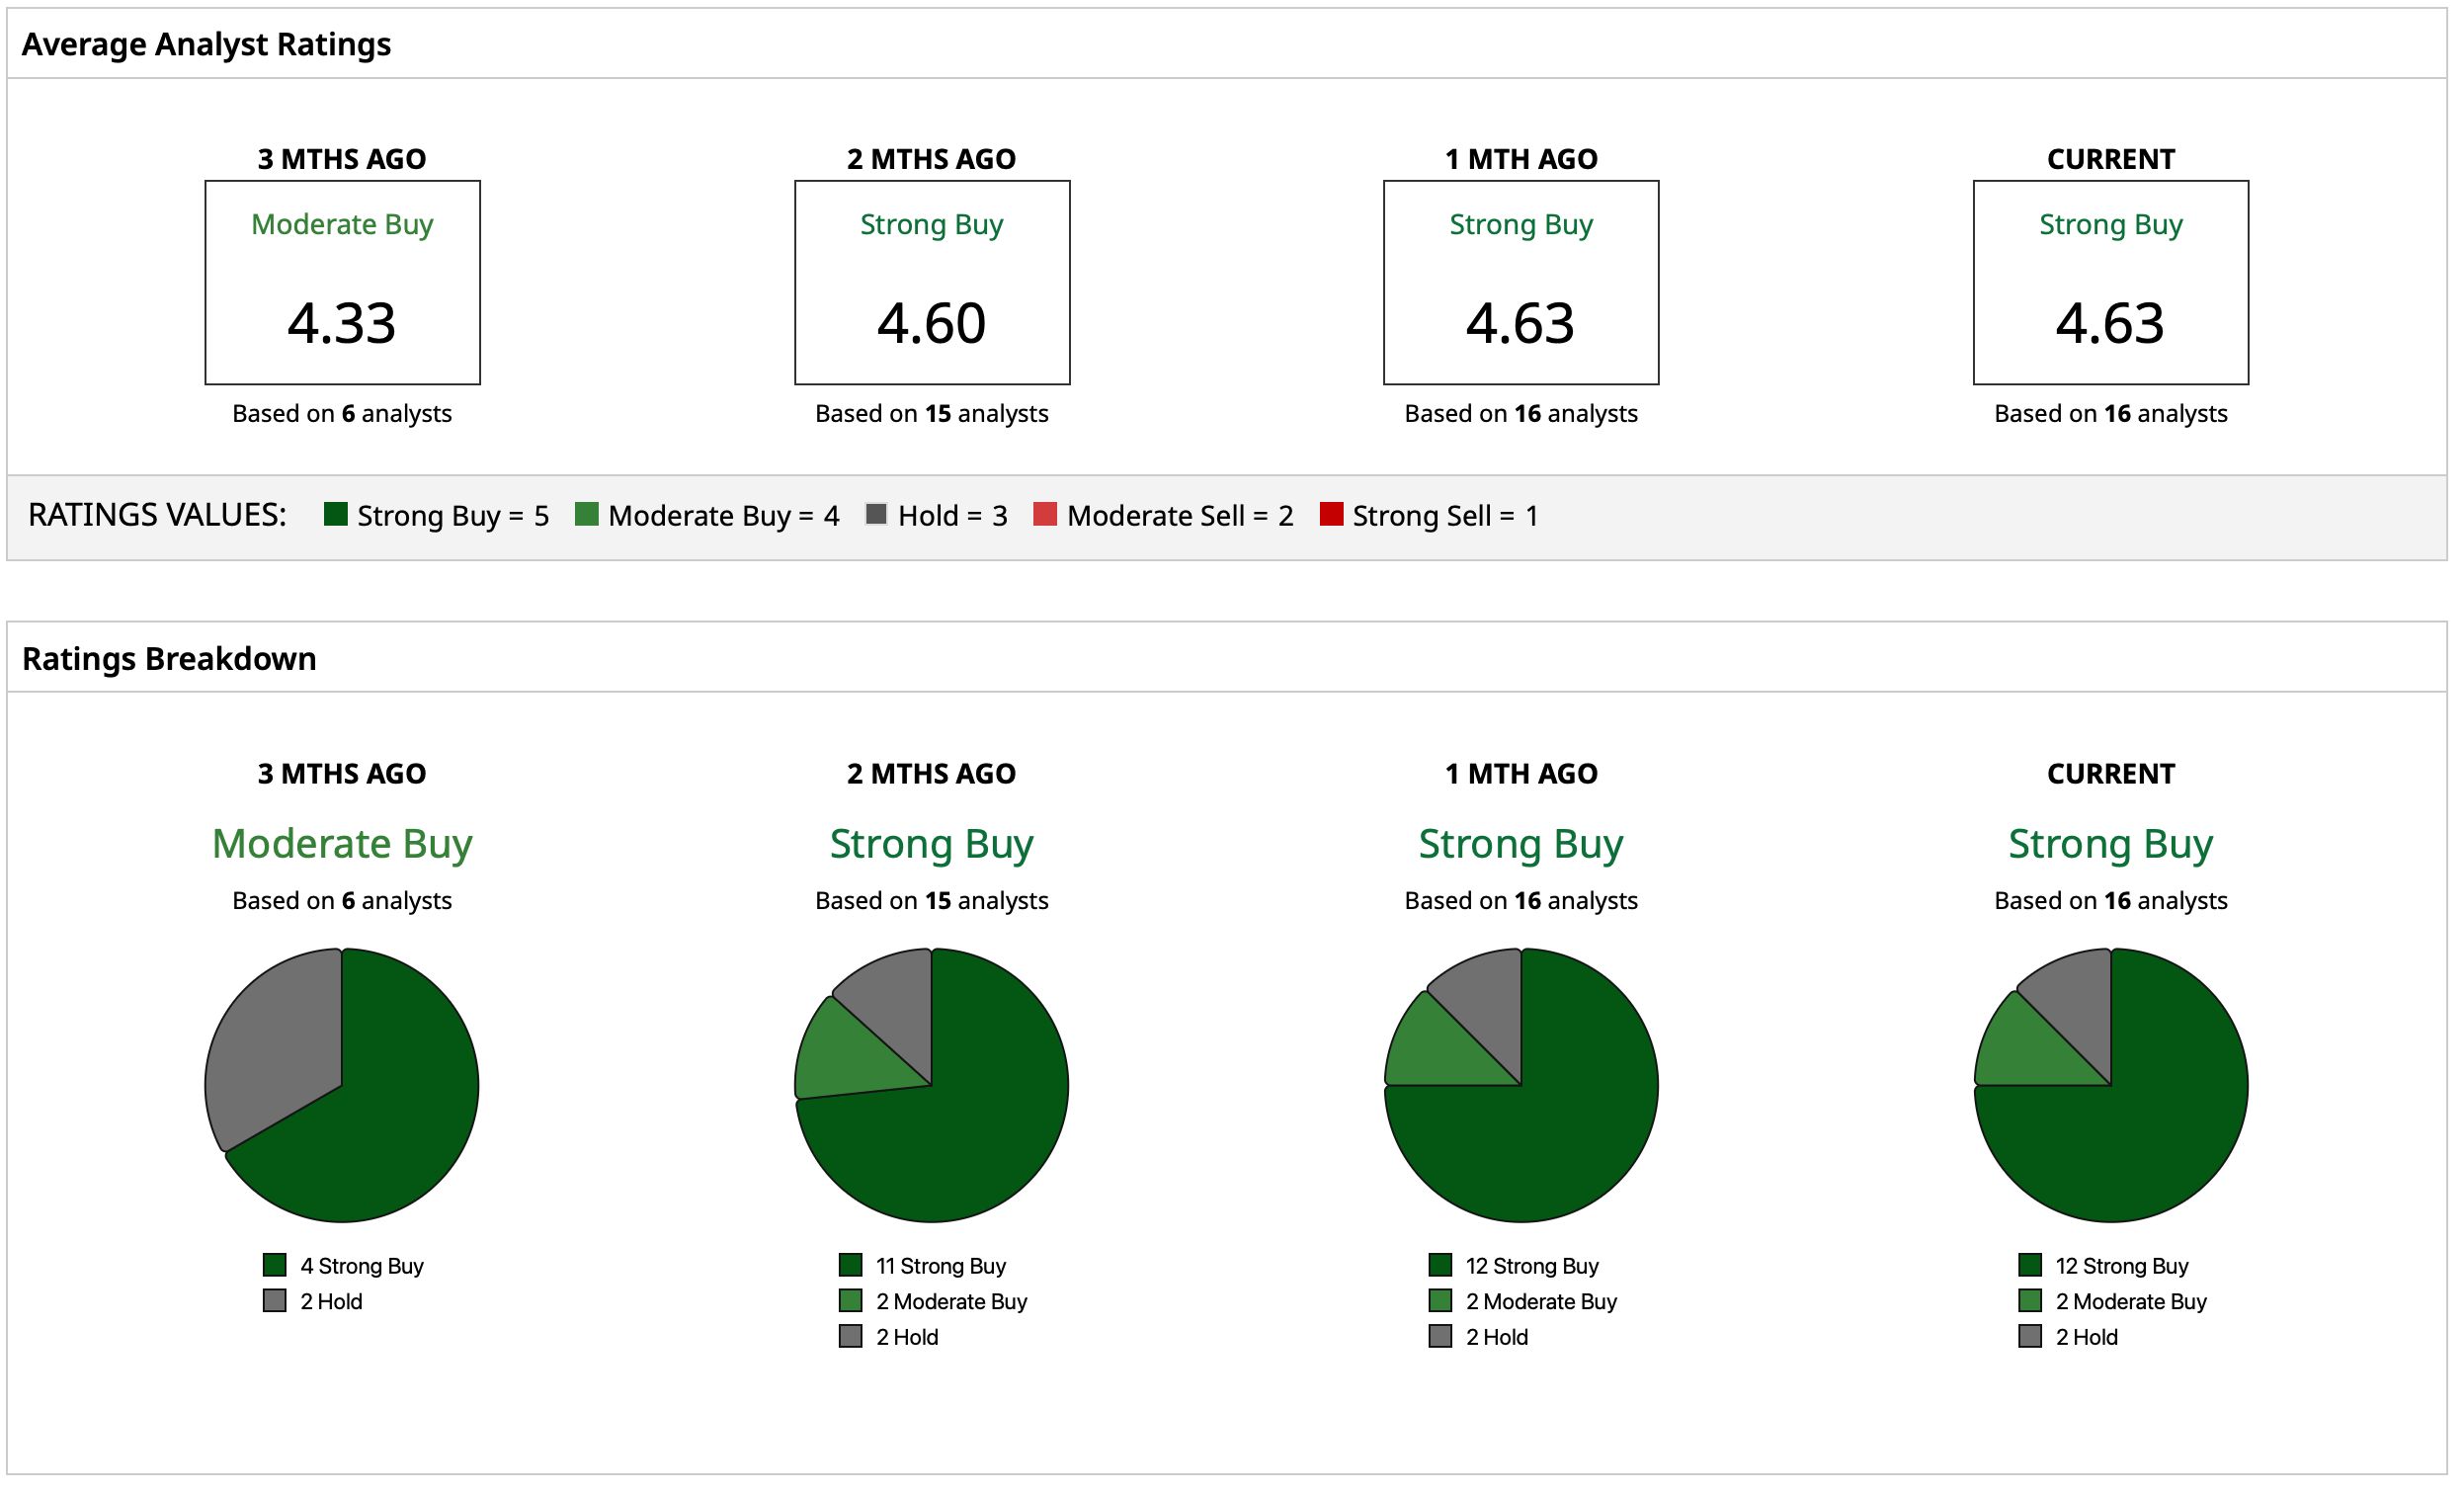
Taking all of this into account, analysts have assigned an overall rating of “Strong Buy” for SKHY stock. The mean target price of $248.82 denotes a potential upside of 52% from current levels. Out of 16 analysts covering the stock, 12 have a “Strong Buy” rating, two have a “Moderate Buy” rating, and two have a “Hold” rating.
 www.barchart.com
On the date of publication, Pathikrit Bose did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
SK hynix's Solidigm Is Mulling a $45 Billion Chip Plant Investment. What This Means for SKHY Stock. SpaceX Reportedly Faces Higher Borrowing Costs on Its $40 Billion GPU Deal. What It Means for SPCX Stock. Ahead of On Semiconductor Earnings, Here's What Barchart Data Says Comes Next for ON Stock The AI Red Queen Effect: Why Big Tech Can’t Afford to Stop Spending