

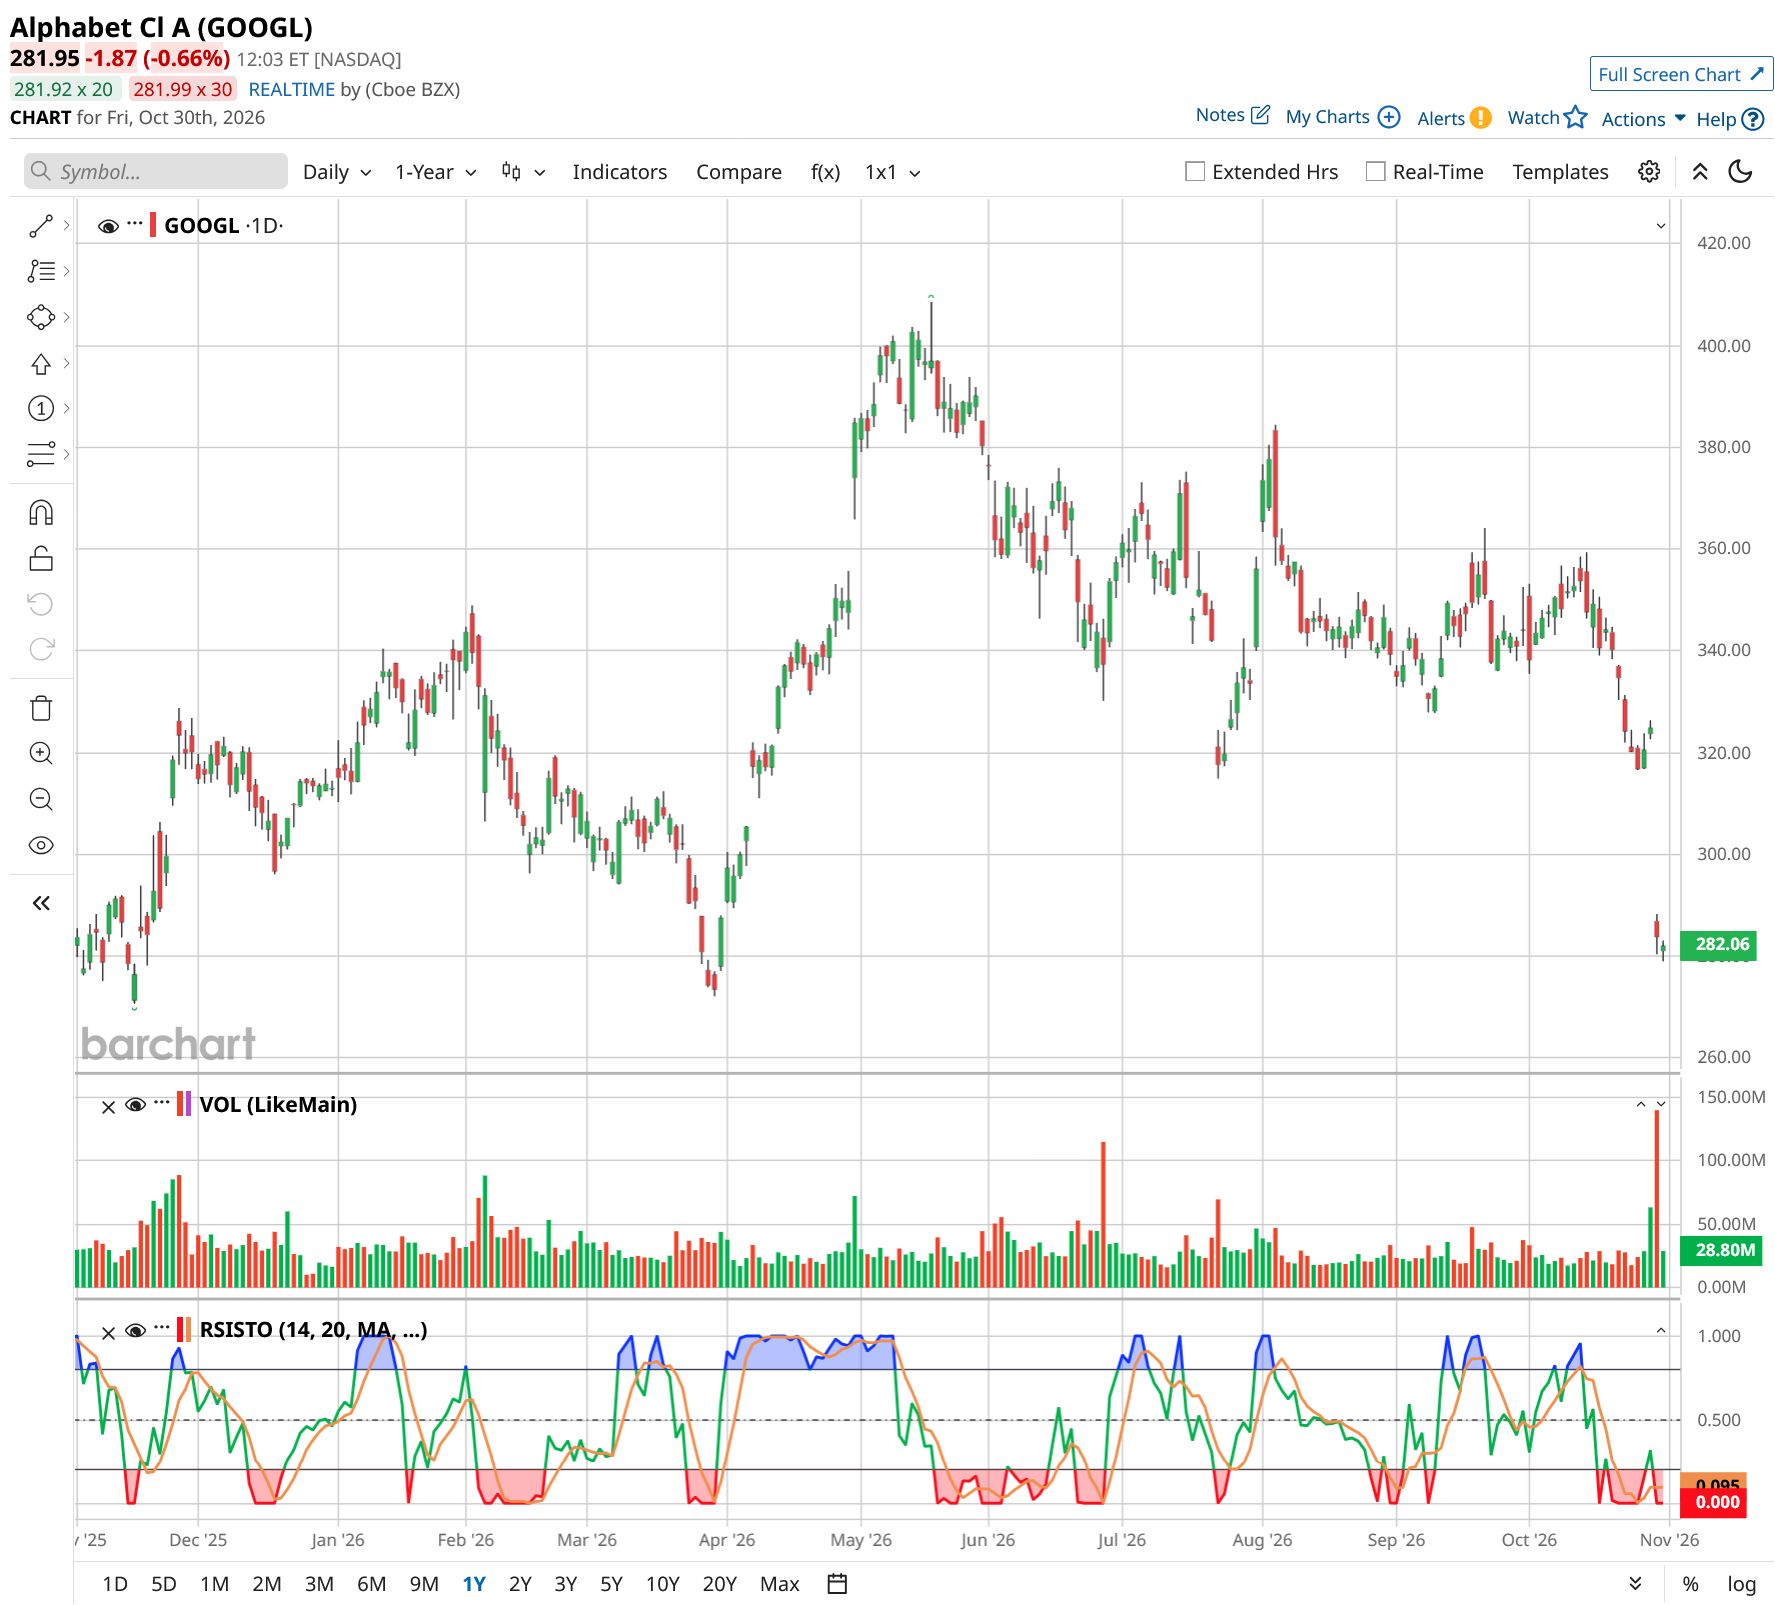
Alphabet (GOOG) (GOOGL) shares fell sharply after the company’s Q3 earnings announcement, plunging more than 12% in a single day and wiping billions of dollars from its market capitalization. The decline was driven mainly by slower-than-expected growth in Google Search and concerns about the company’s rapidly escalating investments in artificial intelligence (AI).
Google Search, Alphabet’s largest revenue-generating segment, delivered revenue of $63.3 billion, up about 12% year-over-year (YoY). This marked a deceleration from the 17% growth reported in Q2 and fell short of Wall Street expectations. Although challenging YoY comparisons contributed to the moderation, investors were particularly concerned about the slowdown occurring alongside a substantial increase in AI-related spending.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The slowdown raises concerns over whether Alphabet can generate sufficient returns from its aggressive AI investments to justify the associated costs. During Q3, capital expenditures reached $51.4 billion, with most of the spending directed toward the technical infrastructure required to support AI. While these investments could strengthen Alphabet’s competitive positioning and create new monetization opportunities over the longer term, their near-term impact on profitability and cash generation remains a concern.
 www.barchart.com
The pressure on cash flows is already becoming evident. Alphabet reported negative free cash flow of $9.1 billion in Q3, reflecting the substantial financial burden associated with expanding its technical infrastructure and building inventory of Tensor Processing Unit (TPU) systems as it scales its AI-related operations. Continued investment at this pace could constrain free cash flow in the coming quarters.
Near-term challenges are also likely to persist. Google Search faces tough year-over-year (YoY) comparisons in Q4, which could make it difficult to reaccelerate reported growth. At the same time, elevated capital expenditure requirements may continue to restrict free cash flow.
Why Buy GOOGL Stock?
Despite near-term headwinds, including concerns over moderating Search growth and elevated capital expenditure, Alphabet’s long-term investment outlook remains solid. The company’s strong positioning in AI, accelerating Google Cloud growth, and expanding the subscription ecosystem provide multiple avenues for sustained revenue expansion. Against this backdrop, the recent share price correction presents an attractive entry opportunity for investors with a long-term investment horizon.
A key driver of Alphabet’s growth is the accelerating momentum in Google Cloud, supported by growing enterprise demand for AI-related infrastructure and solutions. In the latest quarter, Cloud revenue surged 103% YoY to $30.7 billion, reflecting robust performance across AI infrastructure, AI solutions, and core Google Cloud Platform (GCP) offerings. Growth also accelerated from the previous quarter, highlighting improving momentum. Moreover, sales of its TPU systems have become a meaningful contributor.
Google Cloud’s backlog reached $561 billion in the third quarter, and management expects to recognize slightly more than 55% of it as revenue over the next 24 months. The sizeable backlog provides considerable revenue visibility.
Alphabet’s AI ecosystem is also gaining traction. The Gemini application has reached 1 billion users, making it the fastest-growing product in the company’s history. This growing adoption strengthens Alphabet’s position in the increasingly competitive AI market and creates opportunities to monetize its AI capabilities across consumer and enterprise offerings.
Meanwhile, the subscription business is providing an additional source of growth and diversification beyond advertising. Subscription, Platforms, and Devices revenue increased 11% YoY to $14.3 billion, driven by strong demand for YouTube subscriptions, particularly YouTube Music and YouTube Premium, as well as growing adoption of AI-powered plans within Google One. Continued expansion of subscription revenue is strategically important because it broadens Alphabet’s revenue mix and reduces its dependence on advertising over time.
Overall, although Google Search faces challenging comparisons and AI-related investments are likely to keep capital expenditure elevated, Alphabet’s accelerating Cloud business, expanding AI ecosystem, and resilient subscription operations provide compelling long-term growth drivers. These businesses could help offset moderation in Search growth and support continued revenue diversification. Consequently, the recent pullback offers a favorable opportunity to buy GOOGL stock at a better price.
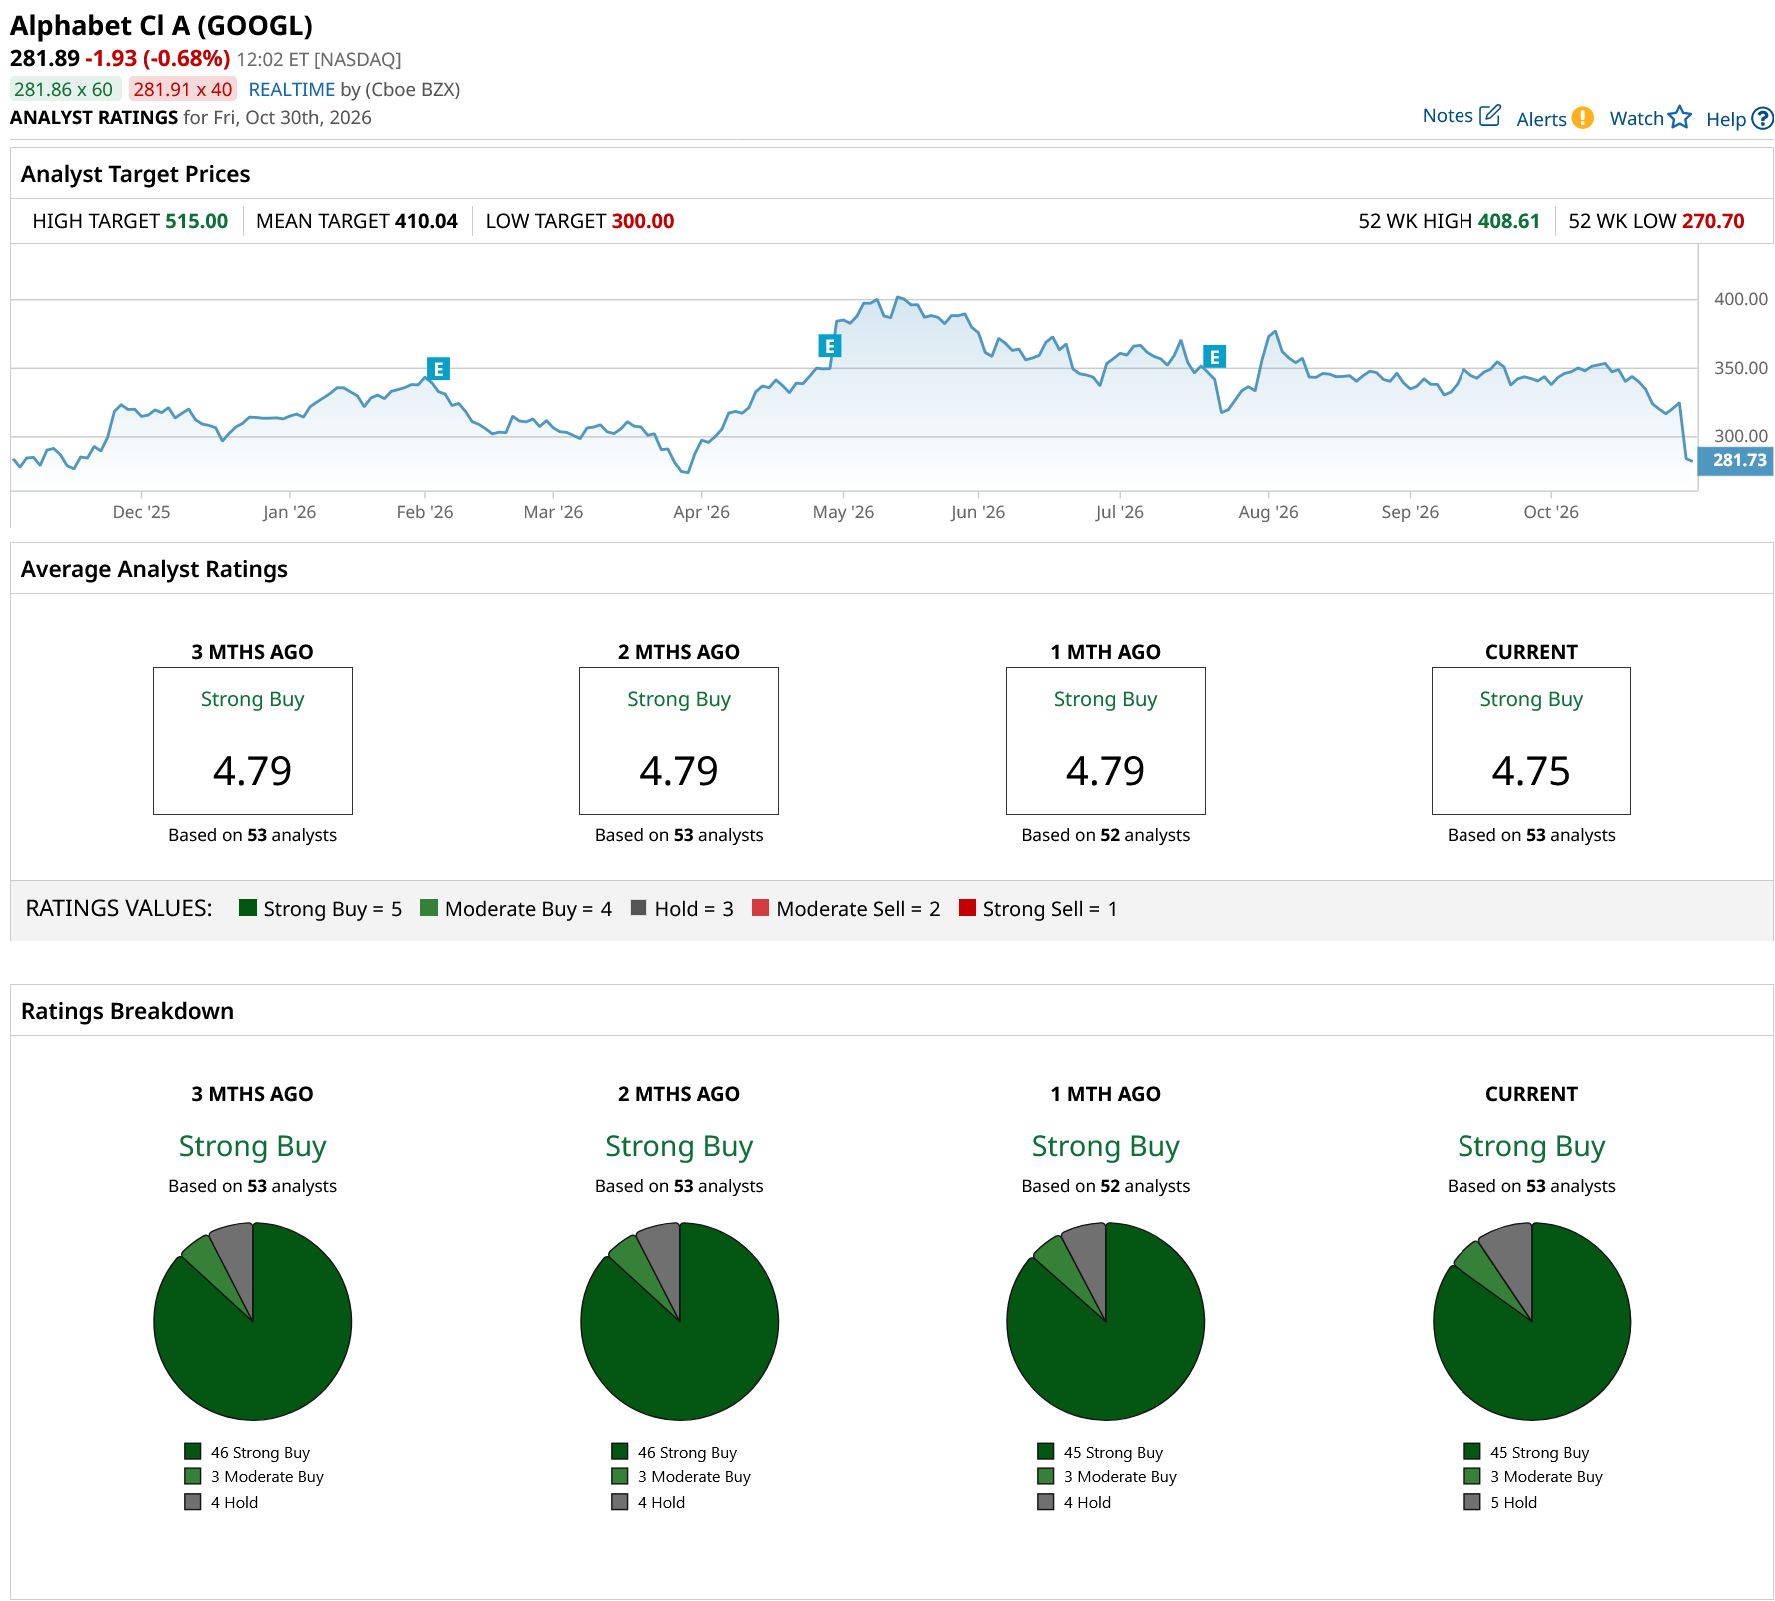
Analysts remain bullish, with a “Strong Buy” consensus rating on GOOGL shares, reflecting continued optimism about the company’s growth potential.
 www.barchart.com
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear ON Semiconductor Stock Fans, Mark Your Calendars for November 2 Why It's Time to Buy the Pullback in Alphabet Stock Dear Roku Stock Fans, Mark Your Calendars for November 2 Why Now Is Not the Time to Load Up on Netflix Stock