

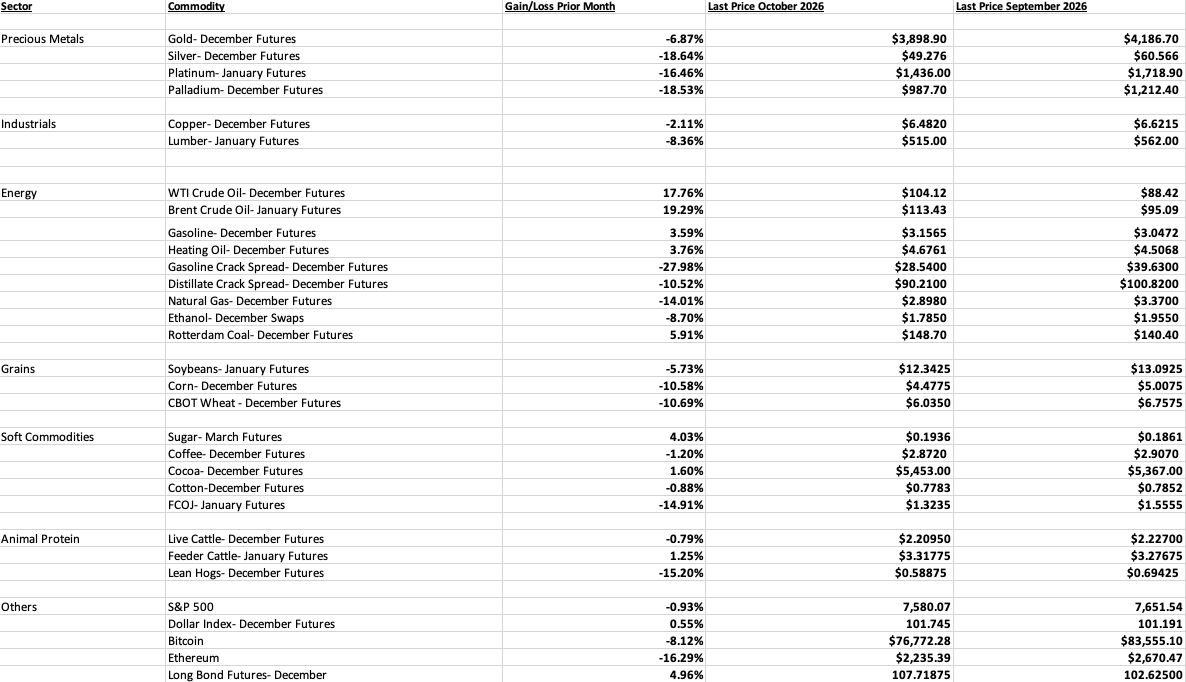
In the commodities asset class in October 2026, Brent and WTI crude oil futures were the only two commodities posting double-digit percentage gains. There were double-digit percentage declines in the precious metals, energy, grains, softs, and animal protein sectors. The DJIA and Russell 2000 indices edged higher, while the tech-heavy NASDAQ and S&P 500 were lower. Long bond futures recovered after falling to the lowest level since 2002. The December dollar index futures rose 0.55%. December Long bond futures rose 4.96%. A higher dollar index and slightly lower interest rates sent mixed signals for commodity prices, but most raw material futures, except crude oil, posted losses. The Fed left the Fed Funds Rate unchanged at the most recent October FOMC meeting.
Crude oil rallies on geopolitical uncertainty
A continuation of the stalemate between Iran and the United States, along with a tightening of the economic noose around Iran, drove crude oil prices higher. At the end of October, tensions remained high, as the U.S. attempt to use economic weapons has caused backlash from Iran. Crude oil, oil products, and Rotterdam coal posted gains in October, while crack spreads, natural gas, and Chicago ethanol swap prices declined.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
Iran continued to stall for time, submitting proposal after proposal, but the U.S. has rejected the efforts as they do not include Iran’s agreement to abandon its nuclear aspirations, open the Strait of Hormuz, and stop its proxies from attacking Israel and Saudi Arabia near the Bab al-Mandeb Strait. The periodic attacks continued in October, while the Iranian economy continued to decline.
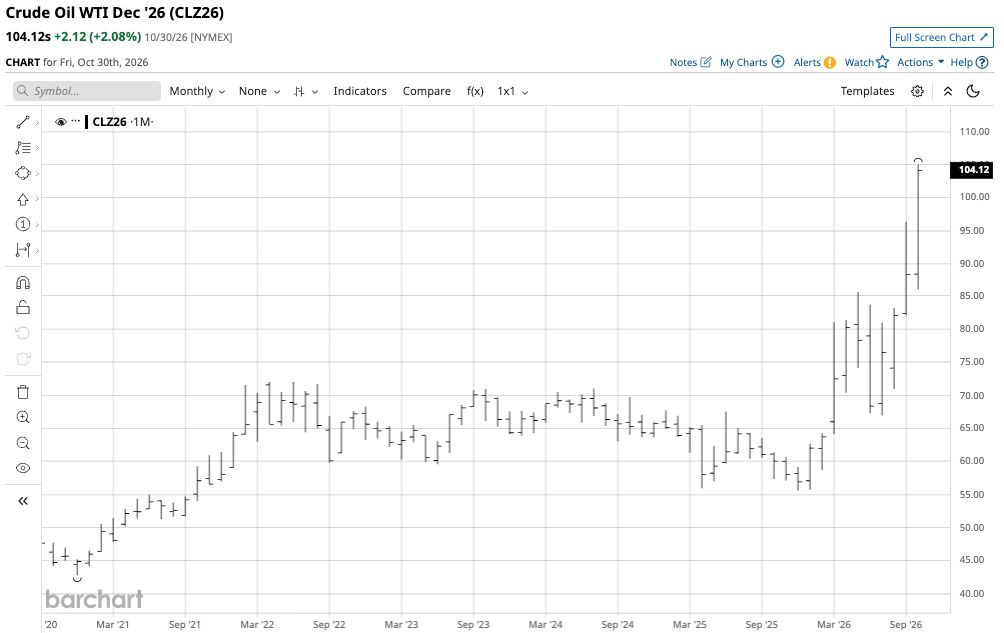
The monthly December NYMEX WTI crude oil futures chart shows that the price rose 17.76% in October. January Brent crude oil, the benchmark for Middle Eastern petroleum, outperformed the WTI, posting a 19.29% monthly gain.
Crude oil prices remained volatile in October, rising on events in the Middle East and around the Strait of Hormuz and the Bab al-Mandeb Strait, as well as the lack of a peaceful resolution.
Gasoline futures moved 3.59% higher, while heating oil futures, which are a proxy for other distillate fuels, rose 3.76%. The products rose less than crude oil as the lag between refinery stocks and crude oil supplies kept product prices elevated.
Crack spreads reflect the refining margins for processing crude oil into gasoline and distillate products. The December gasoline crack spread fell 27.98% in October, while the December distillate crack spread fell 10.52%. Pump prices lag crude oil prices. Seasonality weighed on the gasoline refining spread as the winter approaches.
December Chicago ethanol swaps, the biofuel additive to U.S. gasoline, fell 8.70% for the month, while December coal futures for delivery in Rotterdam, the Netherlands, rose 5.91% in October. Meanwhile, December U.S. natural gas futures fell 14.01% even though natural gas is moving into the peak season, when inventories begin to decline in late November. European natural gas futures prices moved substantially higher in October on Middle Eastern supply concerns. U.K. natural gas futures prices for December delivery and natural gas futures prices in the Netherlands for December delivery rallied in October as concerns about winter supplies increased. The Middle East continued to drive European natural gas prices higher, which could put upward pressure on U.S. natural gas as European demand for U.S. LNG rises throughout the rest of 2026 and into early 2027. While U.S. natural gas prices have dropped, they have fallen to a level that could offer a bargain in the coming weeks and months.
Metal prices drop
Precious metal prices soared in 2025 and early 2026, but they ran out of upside steam in late January. In August, prices recovered, but they declined in September. In October, precious metals prices plunged. Base metals prices also moved mostly lower.
Gold, the leading precious metal, moved 6.87% lower in October. The volatile silver futures market fell 18.64%. NYMEX palladium futures fell 18.53%, while NYMEX platinum futures fell 16.46%. The four precious metals fell to new lows in 2026.
Copper, the leading nonferrous metal, declined by 2.11% on the December futures contract in October. December COMEX copper rose to a new record high of $6.9600 on August 6, 2026, but fell below $6.50 per pound at the end of October.
Nonferrous metals on the London Metals Exchange turned in mixed results. LME three-month copper forwards moved lower in October after reaching a new record high in September. LME aluminum three-month forwards declined in October despite the turmoil in the Middle East. LME nickel forwards fell, LME lead forwards rose, LME zinc prices edged marginally lower, and LME tin forwards fell in October.
Lumber and agricultural commodities were mostly lower
The harvest season in the Northern Hemisphere ended in October. While the grain and oilseed markets faced fertilizer shortages due to issues at the Strait of Hormuz and rising conflicts around Black Sea ports, prices moved lower in September and October. New crop January Soybean futures fell 5.73%, while December corn futures fell 10.58%, and December CBOT soft red winter wheat futures fell 10.69%. Russia and Ukraine are significant wheat producers. Soybeans fell even as biodiesel prices moved higher with crude oil and oil products.
Soft commodities turned in mixed results in October. December cocoa rose 1.60%, and March 2027 world sugar futures rallied 4.03%. Cocoa’s price stabilized as supply concerns continued, while sugar has followed developments in the Middle East, as Brazil depends on sugarcane for ethanol production. Sugar has followed crude oil and gasoline prices over the past months. Cotton futures for December delivery edged 0.88% lower in October, correcting after the rally that took the price over 90 cents per pound in August. December Arabica coffee futures fell 1.20%. The volatile January FCOJ futures plunged 14.91% in October.
Physical lumber futures for January delivery fell 8.36% in October as the construction season ended and interest rates remain high, slowing demand for new homes.
The 2026 peak grilling season began in late May and ran through early September. Cattle prices rose in September after August declines, as the off-season got underway. In October, the cattle futures posted mixed results. The live and feeder cattle futures for December and January delivery fell 0.79% and rose 1.25%, respectively, in October. Meanwhile, lean hog futures for December delivery plunged 15.20% for the month ending Friday, October 30.
Spotlight on silver and natural gas
U.S. NYMEX natural gas futures could be a sleeping bullish giant over the coming weeks and months as the peak heating season, when inventories decline, begins in November.
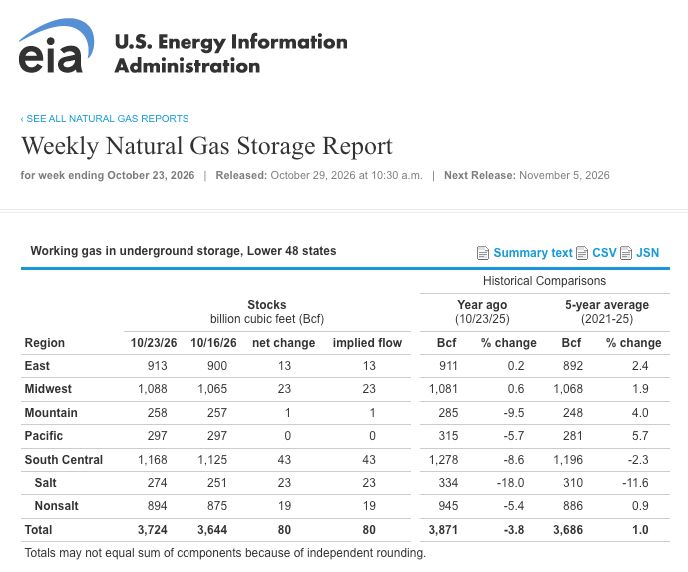 Source: EIA
As of the week ending October 23, 2026, natural gas in storage across the United States was 3.724 trillion cubic feet, 1.0% above the five-year average but 3.80% below the late-October 2025 level.
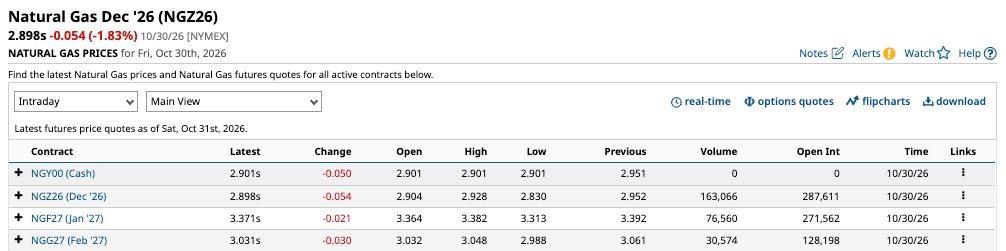
The U.S. natural gas futures forward curve at the end of October shows that the price is below $3.40 per MMBtu for January 2027 deliver and near $3.00 for February 2027 delivery.
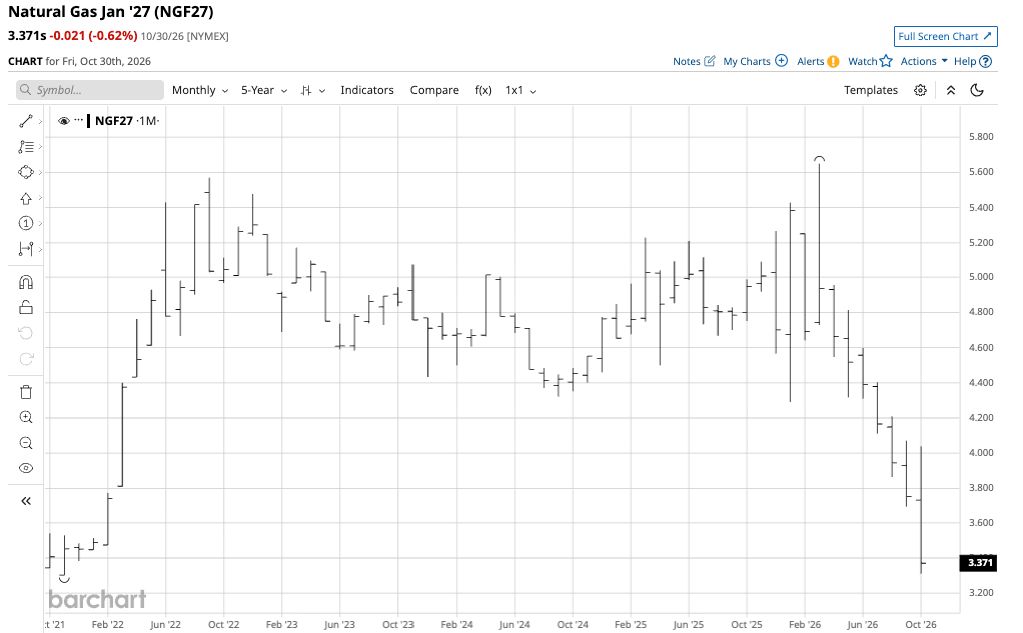
The monthly chart shows that the January 2026 range in U.S. natural gas prices was $4.29 to $5.428, and in February 2026 was $4.643 to $5.25 per MMBtu. In March 2026, natural gas futures reached the 2026 high of $5.65 per MMBtu.
Sky-high European natural gas futures prices and supply concerns could increase the demand for U.S. LNG, causing U.S. inventories to decline more than usual during the coming weeks and months. Moreover, a cold winter in the U.S. and Europe could put upward pressure on prices. At below $3.40 for January 2027 delivery and near $3 for February 2027 delivery, U.S. natural gas futures could be inexpensive at the end of October, limiting the downside risk on long positions.
Silver broke out above its 45-year 1980 high of $50.36 per ounce in October 2025, rising to a record peak of $121.785 in late January, where it ran out of upside momentum. The 45-year technical resistance at $50.36 became technical support.
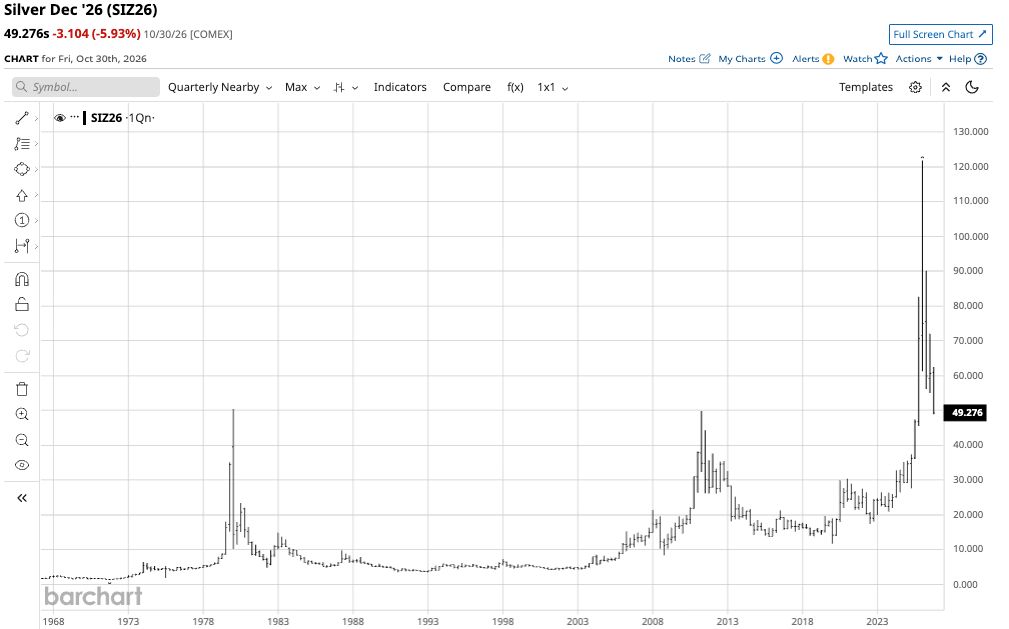
The quarterly COMEX silver futures chart shows that on the final trading session in October, silver fell below the 1980 high and technical support level. Silver closed October at $49.276 per ounce, down 18.64%.
Time will tell whether the silver price carnage continues or if it can bounce back above the 1980 high. The next downside support is at the October 2025 low of $45.51 per ounce. Silver is the most volatile precious metal. While its fundamentals remain bullish, sentiment will drive silver prices over the coming weeks and months. Long liquidation and trend-following shorts drove silver prices lower in October. The trend since late January remains bearish.
Factors to watch in November 2026
As commodities move into November, they face continued uncertainty from the economic and geopolitical landscapes. Seasonality could support lower prices for meats and gasoline as the grilling and driving seasons have ended. We could see buying in natural gas as fall and winter approach and European prices are rising, pushing U.S. LNG demand higher. In crude oil, the U.S. SPR has declined to 282.6 million barrels, 431 million below capacity, which will limit continued withdrawals and could put upward pressure on oil prices.
The situation in the Middle East will continue to dictate the path of least resistance for energy and other commodity prices. The war between Russia and Ukraine and the situation with Iran could roil markets across all asset classes. A potential Super El Niño weather pattern in 2027 could be extremely bullish for agricultural commodities over the coming months.
Tomorrow’s November 3 U.S. midterm elections could impact markets, as the administration’s policy initiatives depend on the outcome. Fractures within the opposition party between middle-of-the-road Democrats and Democratic Socialists could add to uncertainty during the election season as the DSA supports a total ideological remaking of the United States from a capitalist to a socialist country.
Cryptocurrencies have experienced choppy price action and remain at levels that could cause two-way volatility. The dollar index is trending higher, and bonds have recovered from the lowest level since 2002, which is a mixed signal for commodities. Interest rates depend on inflation, and U.S. debt, which is now over $40 trillion. The debt has forced buyers of U.S. government debt securities to demand higher yields as credit deteriorates. Elevated inflation has caused the Fed to raise the Fed Funds Rate in September, but wars could negate the impact of a hawkish central bank. Geopolitical events are bullish, while debt and currency markets offer little guidance on raw material prices as markets move into November 2026.
The bull market in stocks is resting, with the leading indices on either side of unchanged in October. The economic and geopolitical landscapes will determine the path of least resistance for U.S. stocks. Stocks ended October on a very bearish note.
Expect continued volatility in the commodities asset class in November 2026 and beyond, and don't be surprised or disappointed. The volatility creates opportunities, but any new trade or investment requires careful attention to risk-reward dynamics to enhance profits and protect capital. Be careful over the coming weeks, as the midterm election results could create volatile trading conditions across markets and asset classes.
On the date of publication, Andrew Hecht did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.