

I am not going to be one of your hype guys for the upcoming Anthropic (ANT) IPO. Frankly, I find it challenging to identify many stocks I would consider for more than a trade right now.
So I charted literally hundreds of stocks. The entire S&P 500 Index, in fact. And here are three stocks I find most attractive between now and year-end.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
In other words, while I am not a big fan of investing “contests,” I think that these three names will outperform ANT stock by the time the ball drops in Times Square.
Anthropic’s newly revealed IPO filing contains a headline number designed to stop Wall Street in its tracks: a staggering $131.7 billion war chest in cash and short-term investments as of June 30.
According to data compiled by CNBC, that balance gives the nearly six-year-old artificial intelligence firm the third-largest cash pile among all non-banking companies in the United States. It sits behind only Berkshire Hathaway (BRK.B) ($365.5 billion) and Alphabet (GOOGL) ($242.5 billion), while towering over long-standing corporate titans like Amazon (AMZN) ($123B), Meta (META) ($90.3B), Microsoft (MSFT) ($76.8B), and Apple (AAPL) ($62.4B).
To the retail crowd and momentum-chasing algorithms, a $131 billion balance sheet looks like an impregnable fortress.
But when I look beneath the headline, the illusion begins to unravel. In forensic accounting, not to mention fiduciary risk analysis, where cash comes from is infinitely more important than the gross balance sitting in a bank account.
Cash from Operations vs. Cash from Financing
Cash from Operations (Operating Cash Flow): This is the life’s blood of a tenured business with a time-tested stream of revenue and profits. No faking here.
It represents the organic cash collected from paying customers for goods and services, minus the actual cash cost of producing them, paying employees, and keeping the lights on. When operating cash flow is positive and growing, a company is self-sustaining. It feeds itself, funds its own capital expenditures, and distributes excess capital to owners.
Cash from Financing: This is capital brought into the company from outside sources. Than can either be via borrowing debt from creditors or issuing new equity shares to investors. Cash from financing does not mean your product is generating sustainable profits. It simply means outside capital providers wrote you a check.
To understand Anthropic’s $131.7 billion war chest, we have to ask a blunt question: How did a six-year-old company amass a cash reserve larger than Apple’s? It certainly didn’t do it by generating free cash flow from Claude subscriptions or API token usage.
Anthropic’s cash pile is almost entirely the byproduct of the aforementioned cash from financing. It was assembled by selling big equity stakes to venture capital funds, private equity backers, and hyperscalers like AMZN and GOOGL. And that difference is definitely not for the good.
When an established titan holds tens of billions in cash, it represents years of accumulated, undistributed operating profits. When an early stage frontier AI lab holds $131.7 billion, it is better described as an emergency buffer. This is not a death-knell for ANT. It is simply a reminder that its IPO is a high-risk, high return proposition. Maybe not from day one, but sooner rather than later.
Anthropic is legally locked into hundreds of billions of dollars in multi-year, non-cancelable compute commitments with cloud providers. Training and deploying frontier models requires incinerating billions of dollars in power and server capacity every single quarter. Despite impressive revenue growth, the cost of frontier model training, safety engineering, and specialized talent continues to drastically outpace cash receipts from enterprise clients.
That more than $130 billion is not sitting on the balance sheet to fund share buybacks, pay dividends, or opportunistically acquire rivals. It is sitting there because without a colossal pool of outside cash, the company’s compute obligations and training runs would lead to an immediate liquidity crisis.
The 3 Cash Cows I Like Better
I know, I know. Don’t be so old-fashioned. But that’s me. The more buzz now, the more I want to eventually try to profit from the short side later. Such as with SpaceX (SPCX) earlier this year.
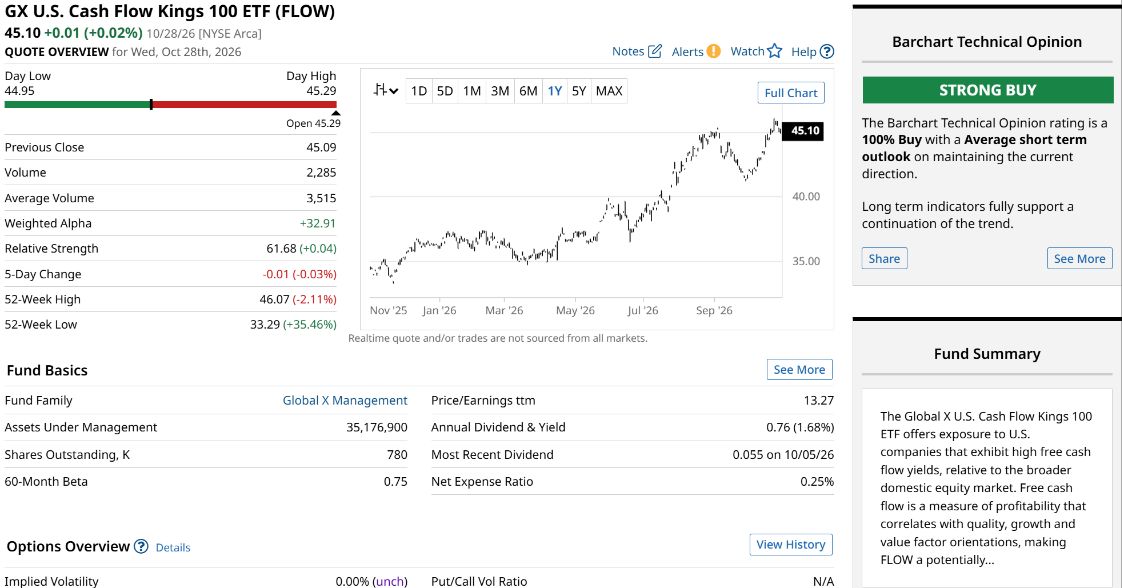
Since I’m a technician primarily, and I use ETFs to narrow down the number of stocks I chart, I used a little-known ETF, the GX U.S. Cash Flow Kings 100 ETF (FLOW), to save a huge chunk of time in the process.
 www.barchart.com
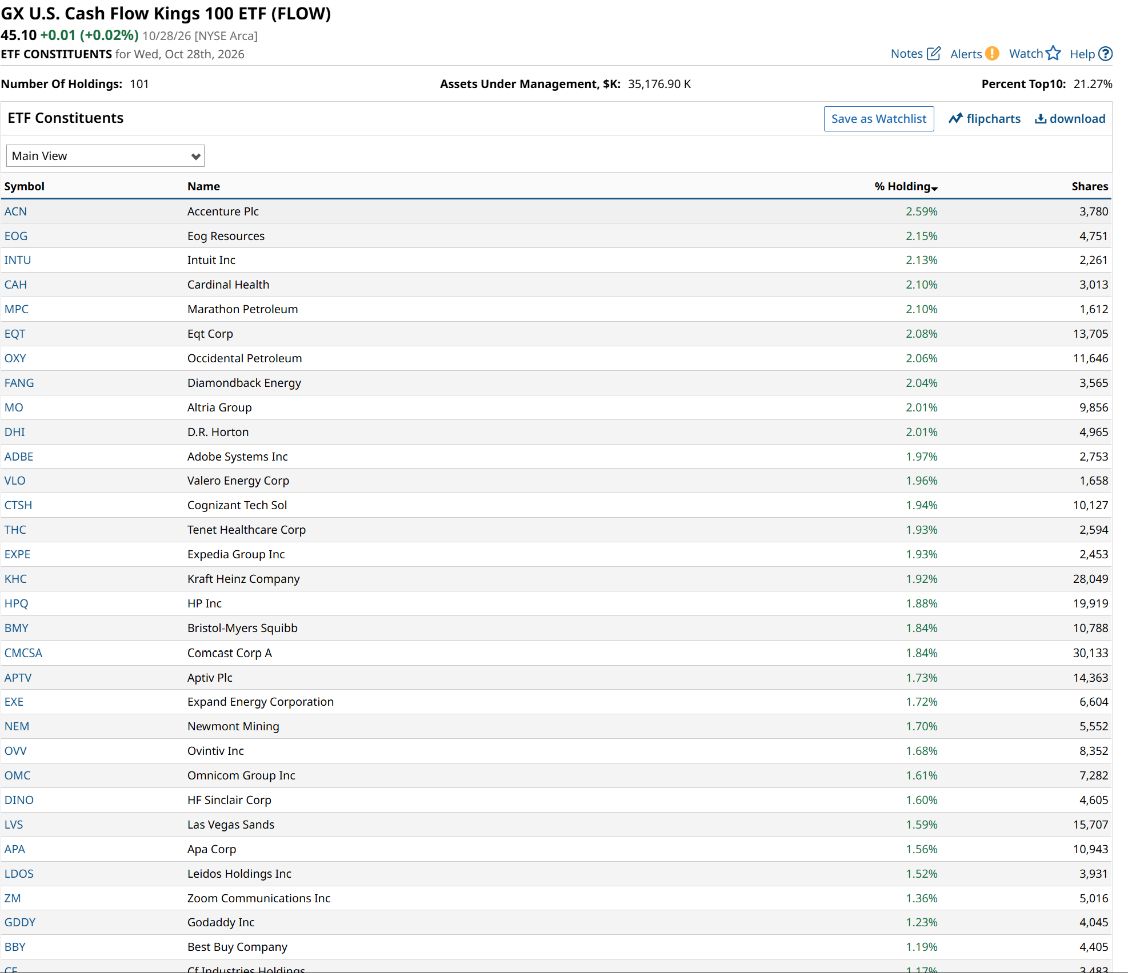
FLOW holds 100 stocks, including these, which are currently the highest-weighted names.
 www.barchart.com
I charted all 100, and here are the three I like best, chart-wise, and with a 6-12-month outlook in mind. This was not easy. Very few stocks look to be on solid ground based on my traditional playbook.
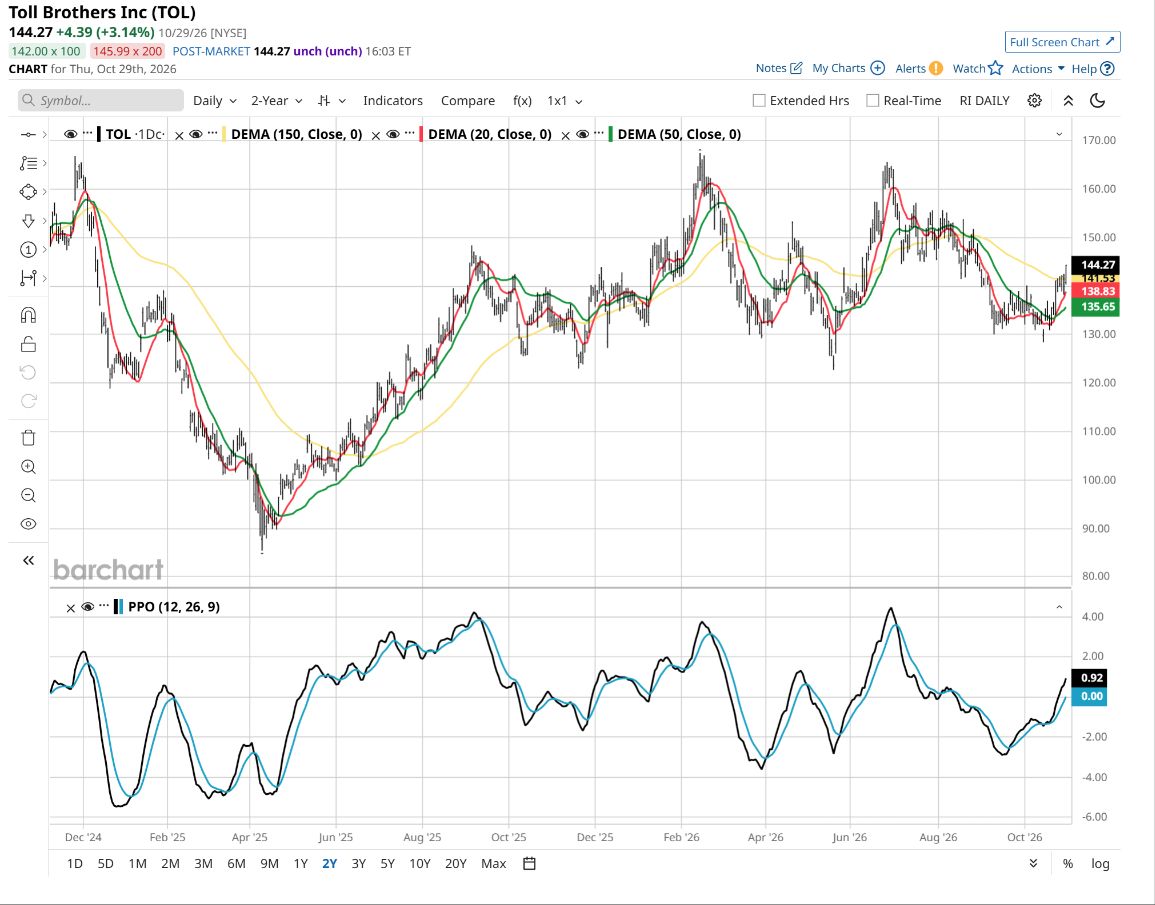
Toll Brothers’s (TOL) chart looking like this should signal that the market is starting to believe rates have topped for a while. That would help homebuilders like this one. Of course, falling rates could also be a sign that a recession is coming. So be careful what you wish for.
 www.barchart.com
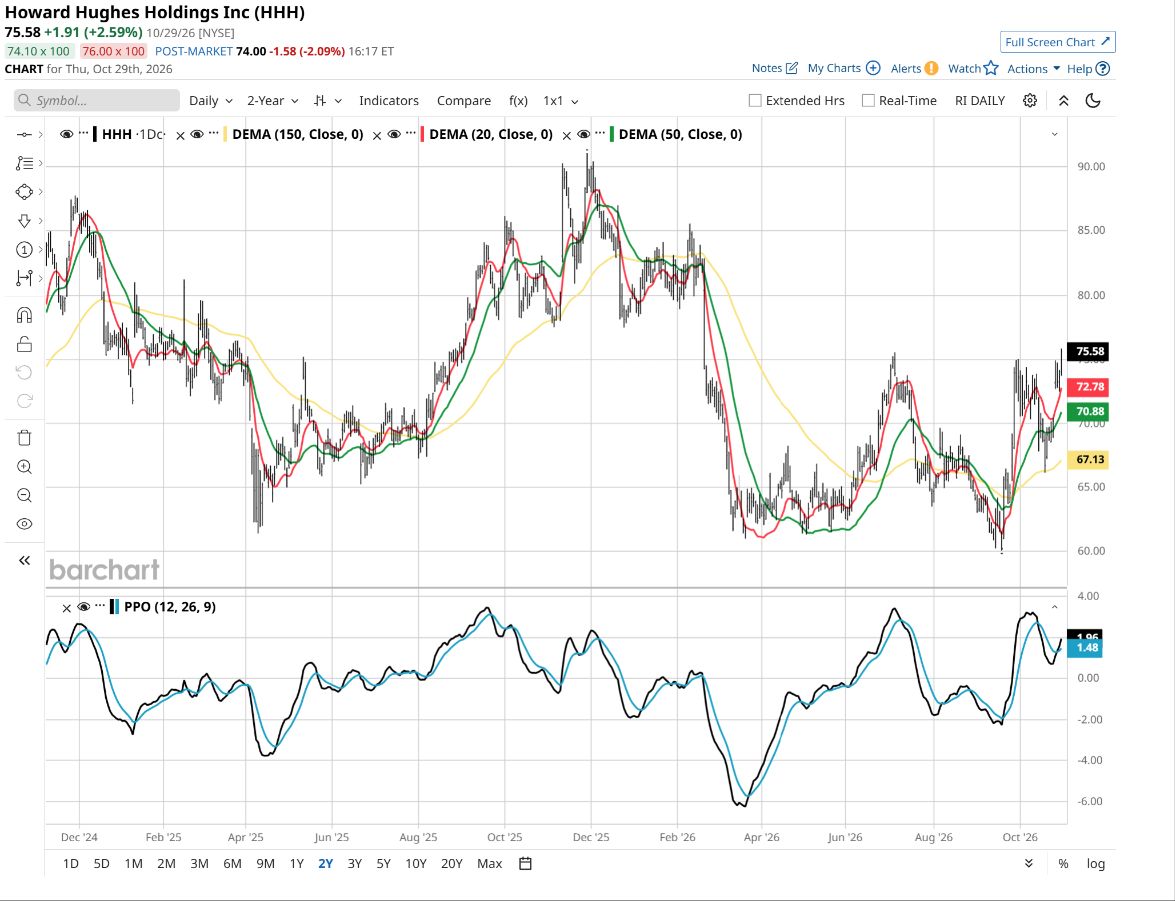
You might have heard of Howard Hughes (HHH), but if you are like me, you would not have guessed that this was a public company. It certainly is, and HHH owns some very high-end real estate, including the Seaport in New York City.
The stock is close to breaking out. Again, this could be more of a sector-driven move. But the profits would still be the same shade of green.
 www.barchart.com
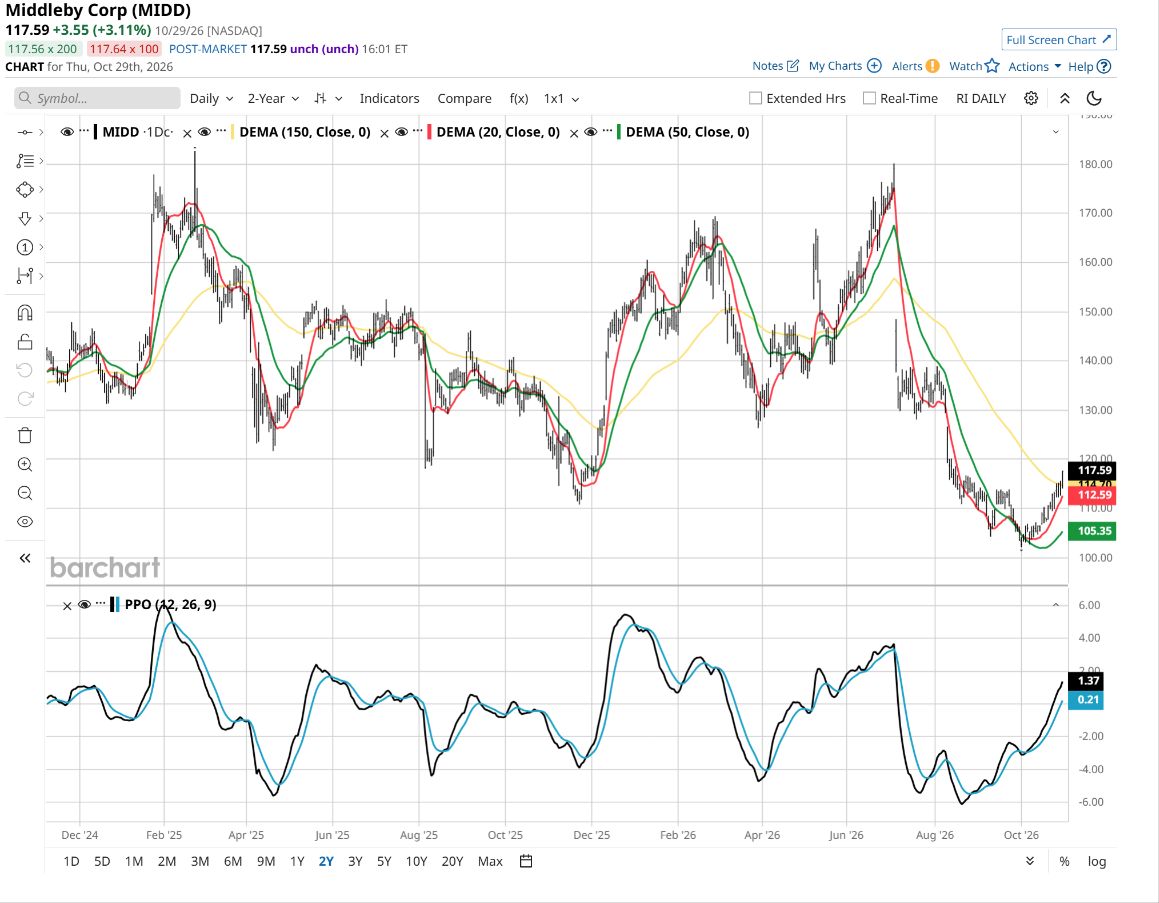
Finally, Middleby Corporation (MIDD) is, ironically, a midcap company, at around $5 billion. This industrial stock has some upside momentum.
 www.barchart.com
To summarize, I don’t like most stocks here. But I still think there are plenty I’d prefer to ANT, at least heading into the much-hyped IPO.
Rob Isbitts is a semi-retired CIO, former fiduciary investment advisor, Barchart columnist, and straight-talker. Download his new free e-book on hedged bond investing for retirement at ETFYourself.com. His research and model portfolios are at ROAR.PiTrade.com.
On the date of publication, Rob Isbitts did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
3 Cash Cow Stocks I Like Better Than Anthropic Heading into a Historic IPO Bill Ackman Isn’t Sweating Meta Platforms’ AI Spending. In Fact, He Says META Stock Is ‘Incredibly Undervalued.’ Dan Ives Thinks Apple’s New MacBook Pro Is a Positive Move with Q4 Earnings Almost Here Anthropic Takes Aim at Wall Street’s 1% Fee Machine With ‘Claude For Financial Advisors.’ Here’s What I Think as a Former Advisor.