

Amid the ongoing tech selloff, another blow for Meta Platforms (META) just picked up as a warning label from Wall Street's most conservative voice. S&P Global Ratings cut its outlook on Meta from “stable” to “negative.” This is not a credit downgrade. Meta still holds an AA- rating. But the negative outlook is a flashing yellow light for investors. S&P is worried about Meta's massive AI spending and its ability to turn those investments into cash.
For years, Meta was a cash machine. Now it is spending cash at a historic pace. That changes the risk profile. That is the headline risk Meta faces today.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
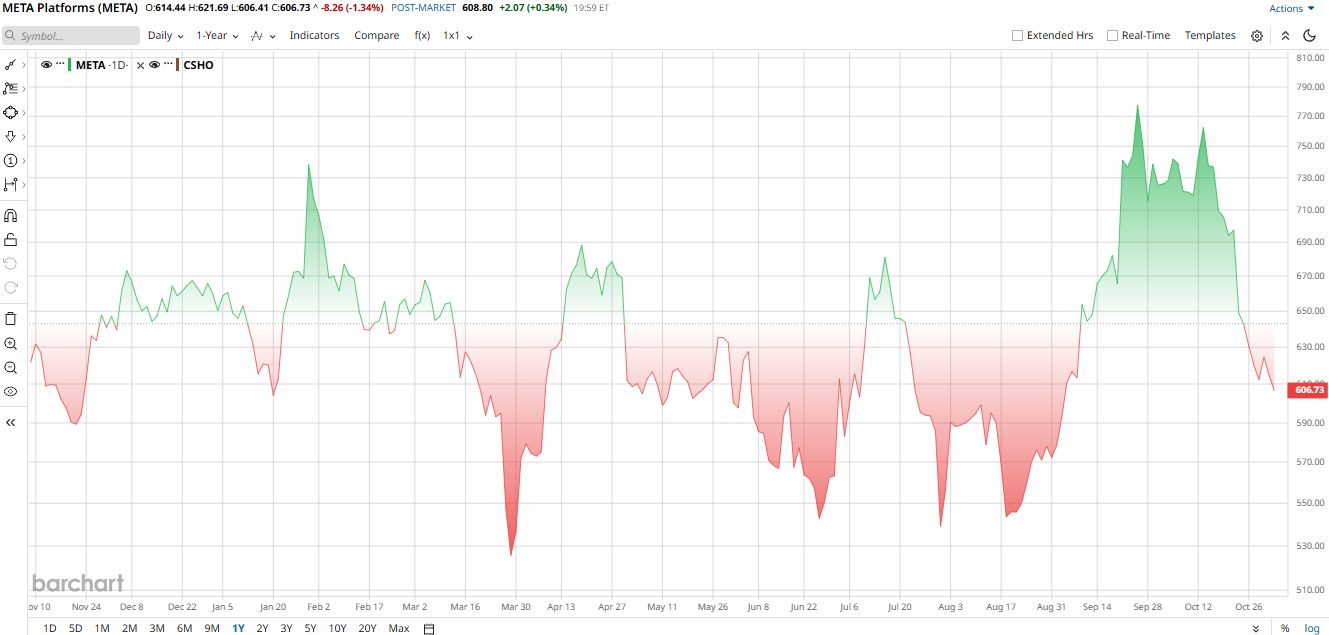
META Stock Has Had a Rough Year
META stock is down about 6% year-to-date (YTD) and closed October down 15%. That was its worst month in four years. Investors are nervous about spending. Meta raised capital expenditure guidance again. Free cash flow turned negative. The S&P outlook cut added fuel to the fire. The stock fell 7% after earnings even though Meta beat revenue estimates. When a company beats and the stock drops, the market is focused on future costs, not the current quarter.
 www.barchart.com
Why S&P Is Worried
The S&P negative rating isn't concerning with the company's primary business. Advertising remains one of the more rapidly expanding segments of the advertising business. You are always concerned about the cash flow. S&P projects free operating cash flow will be negative $39 billion in 2026. Those shortfalls may be made up to $71 billion in 2027. Last, but not least, S&P also thinks that the leverage might be higher than 1.0x. That's more than four times higher than the estimated number of 0.1 percent in 2025.
The reason is funds allocated to capital expenditures. Meta expects to spend between $135 billion and $145 billion on capital expenditures this year. S&P prefers leverage to be less than 1.0 and also for free cash flow to be positive in 2028. The current bearish trend will continue until these factors are overcome.
Meta is seeking to raise a total of up to $97.5 billion in stock sales. It's also making another $20 billion bond sale. That explains why investors are getting tired of debt. The bond sale at Amazon (AMZN) was just 1.6 times oversubscribed recently. This massive yield will likely have to be offered for Meta to find customers.
The Quarter That Started the Worry
Meta's Q3 2026 results were somewhat mixed, with both positives and pressures. Revenue totaled $64.6 billion, or 26% more than previously reported. Advertising revenue is up 26% to $63.1 billion as well. Ad impression increases went up by 10%, and Average price per ad increased by 14%. Operating income of GAAP was compressed by a $9.89 billion litigation settlement.
Net income came to around $9.86 billion, up 264%. Adjusted earnings per share (EPS) was $7.4. Meta exceeded analysts' expectations, which were for $6.52.
The cash flow was the conclusive statement. Strong operating cash flow of $32.79 billion. However, capex was up 30% to $34.91 billion. The free cash flow amounted to a loss of $2.12 billion. One year ago, Meta had positive free cash flow of $10.63 billion.
In a letter to shareholders, CEO Mark Zuckerberg kept his eyes on the bigger picture. The company is to “quote the product, grow revenues, get compute optimization,” he said. Successful direction of fourth-quarter revenue at $73 billion to $76 billion. Full-year analysts estimate revenues at approximately $256.76 billion and EPS at $29.
What Wall Street Is Saying About META Stock
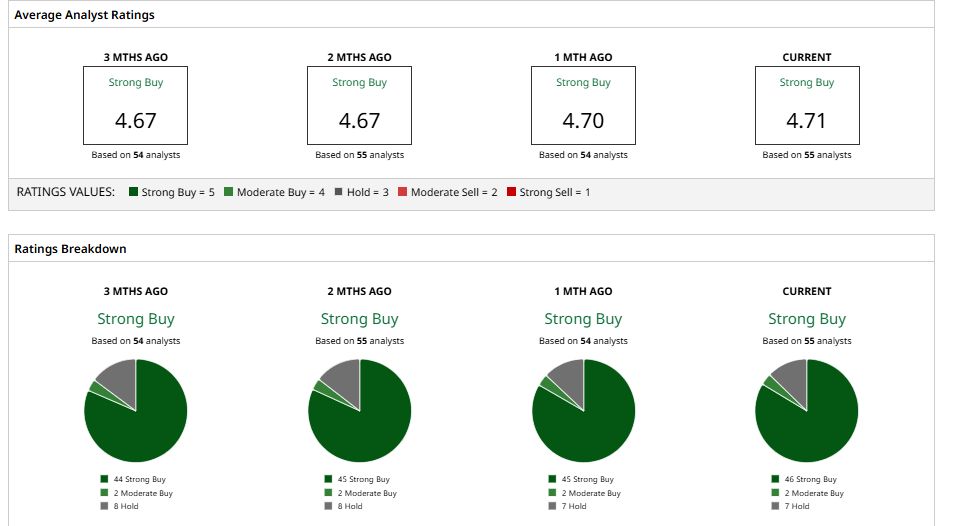
Analysts are not running for the exits. The consensus rating on META stock is a “Strong Buy.” The average price target is around $858, according to Barchart data. That implies roughly 38% upside from the recent price.
Recently, Bernstein's Mark Shmulik raised his target to $850 from $800. Rosenblatt's Barton Crockett raised his target to $900 and said Muse Wonder helps kill the bear case.
Wedbush's Ygal Arounian stayed “Neutral” but lifted his target to $730 from $700. The bulls are louder, but neutral voices are growing.
Meta is not broken. The ad business is growing fast. But spending is real. Free cash flow is negative. Until it turns positive, negative headlines will keep coming.
 www.barchart.com
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
As Meta Stock Suffers Its Worst Month in Years, S&P Delivers a Brutal $39 Billion Cash Flow Warning Why Now Could Be the Right Time to Buy SoFi Stock EVGO Stock Alert: EVgo Receives Acquisition Proposal From LS Power Reddit Is Fighting Back Against AI. What That Means for RDDT Stock.