

Northbrook, Illinois-based CF Industries Holdings, Inc. (CF) manufactures and sells hydrogen and nitrogen products for energy, fertilizer, emissions abatement, and other industrial activities. Valued at $18.3 billion by market cap, the company provides clean energy to feed and fuel the world sustainably.
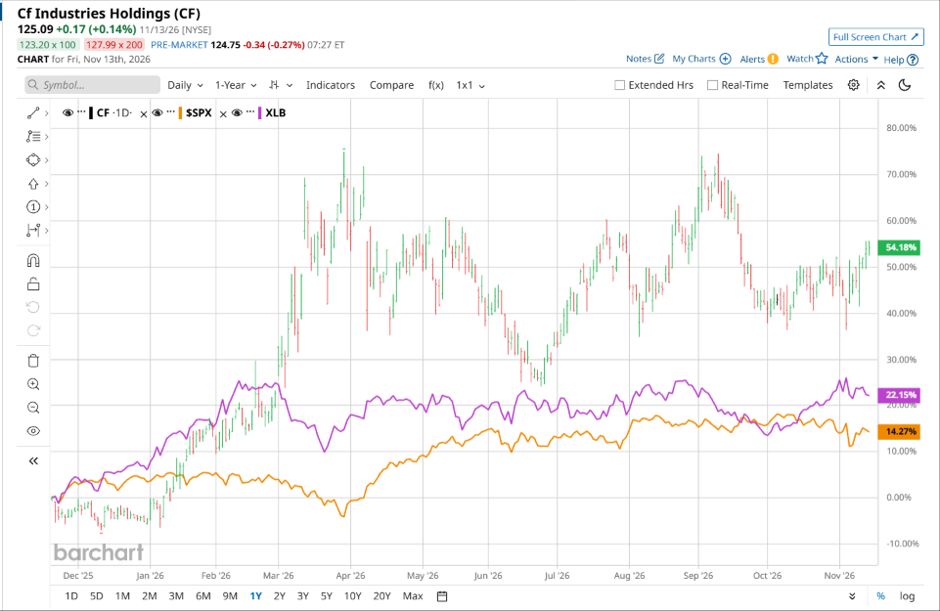
Shares of this leading global manufacturer of hydrogen and nitrogen products have outperformed the broader market over the past year. CF has gained 48.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12.2%. In 2026, CF’s stock rose 61.7%, surpassing the SPX’s 10.5% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Zooming in further, CF’s outperformance is also apparent compared to the State Street Materials Select Sector SPDR ETF (XLB). The exchange-traded fund has gained about 19.3% on a YTD basis. Moreover, CF’s returns on a YTD basis outshine the ETF’s 15.2% gains over the same time frame.
 www.barchart.com
CF’s outperformance reflects its dominant positioning amid tightening global nitrogen markets. Geopolitical disruptions in the Middle East and Black Sea alongside steep European ammonia capacity curtailments have constrained global supply, enabling CF to capitalize on its low-cost North American production network and run at a 97% ammonia utilization rate. This operational execution translated into approximately $3 billion in adjusted EBITDA over the first nine months of 2026, fueling robust free cash flow that management has aggressively deployed toward share repurchases and a 20% dividend hike, while simultaneously advancing long-term growth through its Blue Point low-carbon ammonia project.
On Nov. 4, CF shares closed down over 4% after reporting its Q3 results. Its EPS of $2.87 did not meet Wall Street expectations of $2.93. The company’s revenue was $1.9 billion, surpassing Wall Street forecasts of $1.8 billion.
For the current fiscal year, ending in December, analysts expect CF’s EPS to rise 45% to $13.59 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters while missing the forecast on two other occasions.
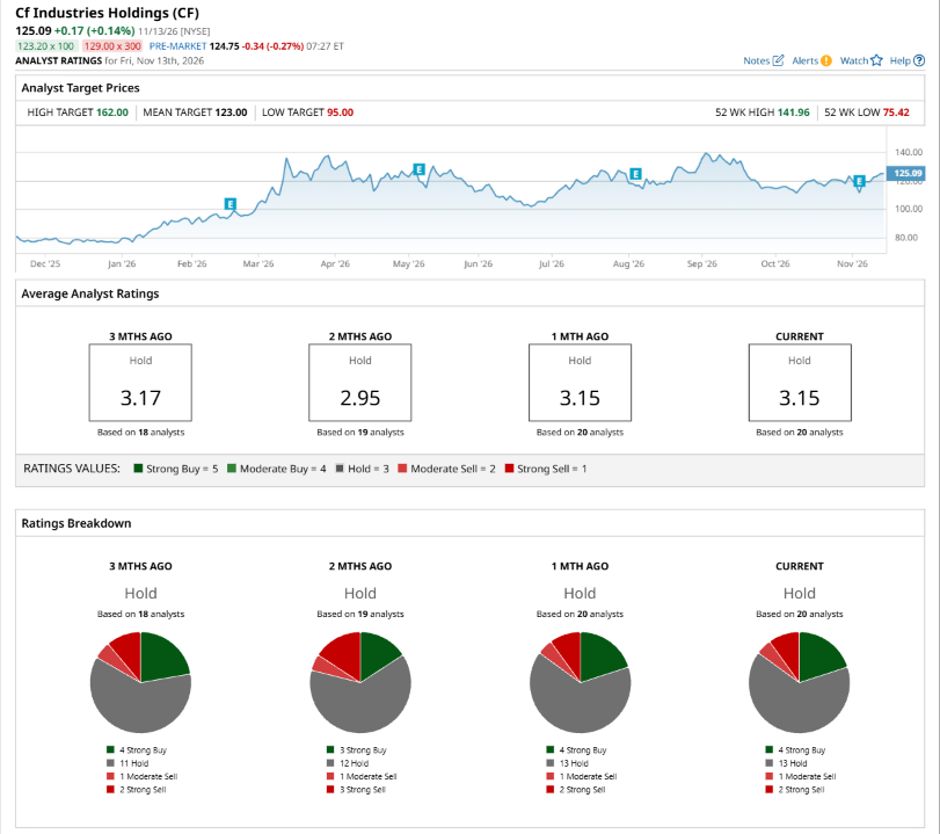
Among the 20 analysts covering CF stock, the consensus is a “Hold.” That’s based on four “Strong Buy” ratings, 13 “Holds,” one “Moderate Sell,” and two “Strong Sells.”
 www.barchart.com
This configuration is more bullish than two months ago, with three analysts suggesting a “Strong Buy,” and three recommending a “Strong Sell.”
On Nov. 12, JPMorgan Chase & Co. (JPM) analyst Jeffrey Zekauskas maintained a “Hold” rating on CF and set a price target of $115.
While CF currently trades above its mean price target of $123, the Street-high price target of $162 suggests an upside potential of 29.5%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Cisco Systems Had a Stellar Quarter, But CSCO Tumbled - Is It Too Cheap Here? Down 62% From All-Time Highs, Here’s How to Play CRWV Stock as CoreWeave Smashes Q3 Estimates Demand for the Anthropic IPO Far Outpaces Available Shares. Be Careful in an Early Scramble for Stock. Option Volatility and Earnings Report For Nov 16-20