

Global fintech firm Klarna Group plc (KLAR) is set to report its third-quarter results on Nov. 17, before the market opens. Ahead of that, the company’s stock gained 8.6% on Friday, Nov. 13 after it was announced that Chris Koegel was appointed chief financial officer, effective Jan. 1, 2027. Koegel joins Klarna from Robinhood Markets, Inc. (HOOD), where he serves as Vice President and Head of Corporate Finance and Investor Relations. Before the Q3 results, investors saw this as a positive step toward stronger financial leadership.
About Klarna Stock
Klarna Group is a global fintech company headquartered in London. It provides digital payments, shopping services, and flexible financing options that let consumers pay online, in stores, and through Apple Pay and Google Pay.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Klarna works with retailers in many countries, helping merchants increase sales and improve customer loyalty. Its services include buy-now-pay-later options, the Klarna Card, membership plans, and consumer banking products. Klarna uses AI-powered technology to make shopping and payments simpler while helping people manage their spending. The company has a market capitalization of $5.21 billion.
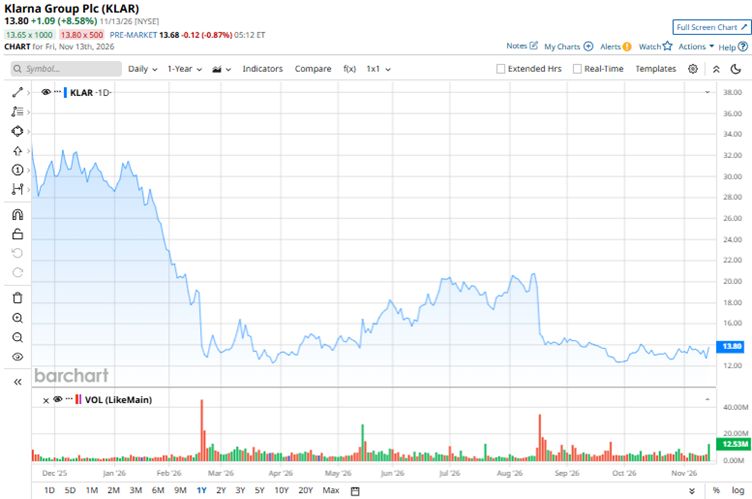
Klarna’s stock is down 60.2% over the past 52 weeks, mainly because investors worry about slower growth and weaker profits amid concerns about softer consumer spending in Europe. However, over the past six months, the stock has risen marginally. It reached a 52-week low of $12.06 on March 30, but is up 13% from that level.
 www.barchart.com
Klarna is currently cheaper than its peers. Its forward-adjusted price-to-sales ratio of 1.37x is lower than the industry average of 3.07x.
Klarna Beat Q2 Estimates but Cut Full-Year Outlook on Softer European Demand
Klarna reported solid second-quarter results. Its gross merchandise volume (GMV) increased by 18% year-over-year (YOY) to $36.65 billion. Revenue also grew by 27% YOY to $1.04 billion, surpassing Wall Street analysts’ $992.60 million estimate. Transaction margin dollars (TMD), which Klarna considers an important financial metric because it captures the transaction-level economics of how the business is growing, rose 42% from the prior-year period to $446 million. A trend also emerged: revenue grew faster than GMV, and TMD grew faster than revenue. Therefore, each dollar Klarna processed turned into more margin than a year ago.
Based on strong top-line performance, Klarna reported $0.01 EPS for the quarter, beating the $0.07 loss per share analysts expected. However, projecting weakness in the German retail sector, Klarna’s single biggest market, the company was forced to take a more measured view of its outlook. For fiscal 2026, Klarna lowered its full-year GMV forecast to $149 billion-$151 billion, or about 17% growth, from more than $155 billion before. It also cut expected revenue to $4.08 billion-$4.16 billion, down from over $4.34 billion, due to lower transaction volumes.
For the about-to-be-reported third quarter, the company expects GMV of $35 billion-$36 billion, revenue of $940 million-$980 million, and TMD of $340 million-$360 million. Wall Street analysts expect Klarna to report a loss per share of $0.16, indicating an improvement of 36% YOY. For fiscal 2026, analysts expect a $0.01 loss per share, reflecting a 98.7% YOY improvement.
Here’s What Analysts Think About Klarna’s Stock
Last month, TD Cowen analysts maintained a “Hold” rating on Klarna but cut the price target from $18 to $16, recognizing the challenges the company faces amid a competitive financial services sector. Earlier, Scotiabank initiated coverage of Klarna with a “Sector Perform” rating and a $16 price target. Scotiabank remains positive on Klarna’s business but cautious on its stock, citing leadership departures and UK credit rules that could complicate compliance, reduce approvals, and hurt checkout sales.
Following its Q2 results, UBS analysts downgraded Klarna from “Buy” to “Neutral” and lowered the price target from $23 to $16, citing a reduction in GMV guidance. UBS estimates that Klarna’s guidance cut represents about $6 billion in annualized revenue, reflecting a significant slowdown in expected international growth, especially in Germany.
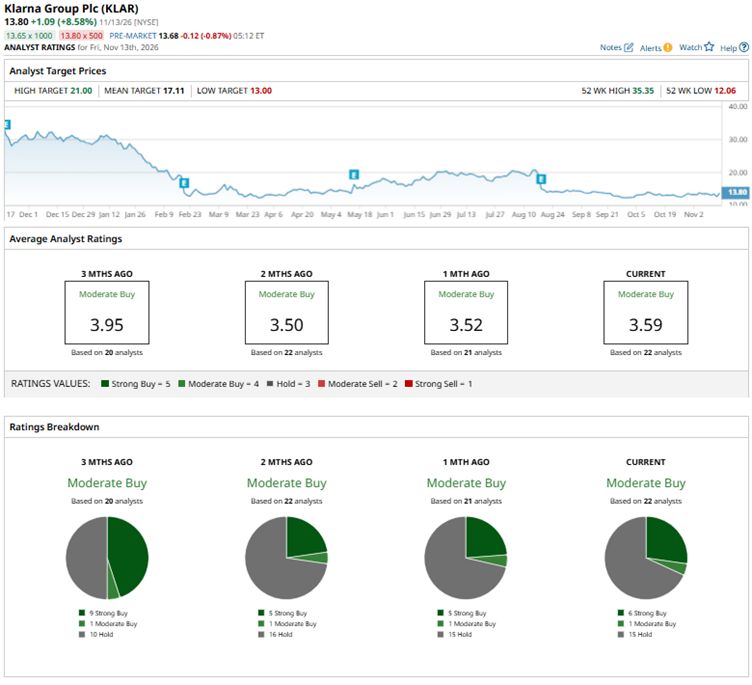
Klarna has become a popular name on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating overall. Of the 22 analysts rating the stock, six analysts have rated it a “Strong Buy,” one analyst suggests a “Moderate Buy,” while 15 analysts are playing it safe with a “Hold” rating. The consensus price target of $17.11 represents 24% upside from current levels. Moreover, the Street-high price target of $21 indicates a 52.2% upside.
 www.barchart.com
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Klarna Stock Fans, Mark Your Calendars for November 17 Dear Starbucks Stock Fans, Mark Your Calendars for November 17 Robert Pattinson Is the New 007. That’s Bad News for Skydance Stock and Good News for the Film Industry. Don’t Buy the Dip in Nvidia Without This Safety Net. How I’m Playing NVDA Stock After the Jensen Huang Fiasco