

Last month, I discussed shorting the $127 ConocoPhillips (COP) put expiring Nov. 13, as well as a put credit spread (buying the $120 put). Both plays worked out well, as COP closed at $142. The same play with the Dec. 18, 2026, COP $130 and $120 put strikes looks attractive.
On Monday, COP closed down a bit to $140.52. In effect, the stock has been in a trading range. In the last 3 months, it's been as high as $154.03 (Oct. 30), and bottomed at $125.27 (Sept. 22).
Can’t Get Enough Options?: Join the list for Barchart’s daily unusual options report, delivered free.
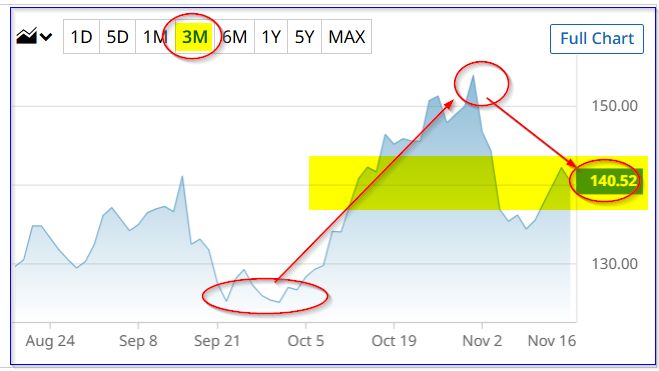 COP stock - last 3 months - Barchart - Nov. 16, 2026
I discussed this in an Oct. 12, 2026, Barchart article, “ConocoPhillips Stock Has Been in a Trading Range - Ideal for Short Put COP Plays.”
Could it hit another trough? Yes, especially if tensions with Iran in the Middle East ease and oil and gas prices keep falling.
But war could flare up again at any time, pushing energy prices up again.
So now, at least COP is in the middle of its trading range. That means it could be worth it to do another short put play or a put credit play. Let's see.
COP Short-Put Play
The Dec. 18, 2026, expiry period, one month from now, shows that the $130 put strike price has a 0.20 delta ratio and a midpoint premium of $1.63. Tha provides good income to a short-seller.
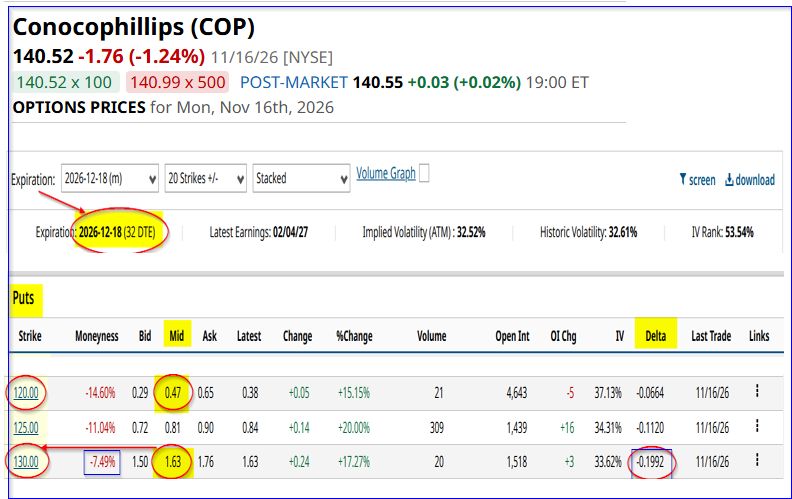 COP puts expiring Dec. 18, 2026 - Barchart - As of Nov. 16, 2026
For example, that means there is an 80% chance of success. An investor who enters an order to “Sell to Open” 1 put contract at $130 will make a one-month 1.254% yield.
In other words, after posting $13,000 in collateral, the $163 in income, if COP stock stays above $130, will have provided a 1.254% yield (i.e., $163/$13,000).
But even if COP drops 7.5% to $130 over the next months, and the account is assigned to buy 100 shares at $130, the net breakeven cost is $130-$1.63, or $128.37. That's 8.65% lower.
In other words, it provides an attractive buy-in point.
Keep in mind, as well, that last month the investor made a 1.88% yield, and the prior month, as I showed in my Oct. 12 article, a 1.22% yield. So, over the past 3 months, the effective income return has been 4.354%.
Annualized, that represents a 17.42% expected return (ER) just from shorting out-of-the-money (OTM) puts. (There is no guarantee these returns can be repeated each month. Moreover, assignment risk could result in an unrealized loss.)
Nevertheless, the bottom line is that this is an attractive way to play COP stock, as it stays within a range.
COP Put Credit Spread Play
As I discussed last month, not every investor has $13K in collateral to do a short-put play. So, one way around that is to do a put credit spread. Last month that meant buying the $120 put in addition to shorting the $127 put expiring Nov. 13.
This resulted in a 14% return: net credit of $86 with just a $700 collateral requirement. So, the at-risk dollar amount was $614, and the expected return was $86/$614, or 14%.
Since COP closed well above the $127 put strike, the one-month 14% return could have been made.
A new put credit spread expiring 12/18/26 can be done (as seen in the table above): short the $130 put for $163, but buy the $120 put for $47. Here is how that works out:
Net credit: $163 - $47 = $116 income
Collateral: $1,000 (i.e., ($130-$120) x 100):
At-Risk Amount: $1,000 - $116 = $884
Expected Return (ER): $116 / $884 -1= 13.12% over one month
Keep in mind that most investors who do put credit spreads tend to close them out early, say, after 50% of the ER is already made. That reduces theta and pin risk (stock ends up between the spread).
Summary and Conclusion
So, over the past two months, the realized return could be 7% +6.5%, or 13.5%. This is attractive to investors. If repeated, the annualized ER is 81%.
The bottom line is that doing a new short-put play or put credit spread play may be attractive.
However, one final point. It is always easy to do these plays when the stock is near or at a 3- or 6-month low.
Sometimes it pays to wait a few weeks to see if that is possible.
On the date of publication, Mark R. Hake, CFA did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Shorting ConocoPhillips Puts and Put Credit Spreads Are Attractive Income Plays Wells Fargo: Get Paid to Wait: or Buy at a Discount Don’t Buy the Dip in Nvidia Without This Safety Net. How I’m Playing NVDA Stock After the Jensen Huang Fiasco Unusual Call Option Activity in Coca-Cola - Is KO Stock Undervalued or Overvalued?