

Marvell Technology (MRVL) has decided that winning the AI infrastructure race takes more than designing faster chips. Its $115 billion agreement to acquire Lumentum (LITE) is a bid to control more of the connections that make enormous AI systems work. This move brings Broadcom (AVGO) into the picture and increases the risks for Marvell’s shareholders. Here’s how it could play out.
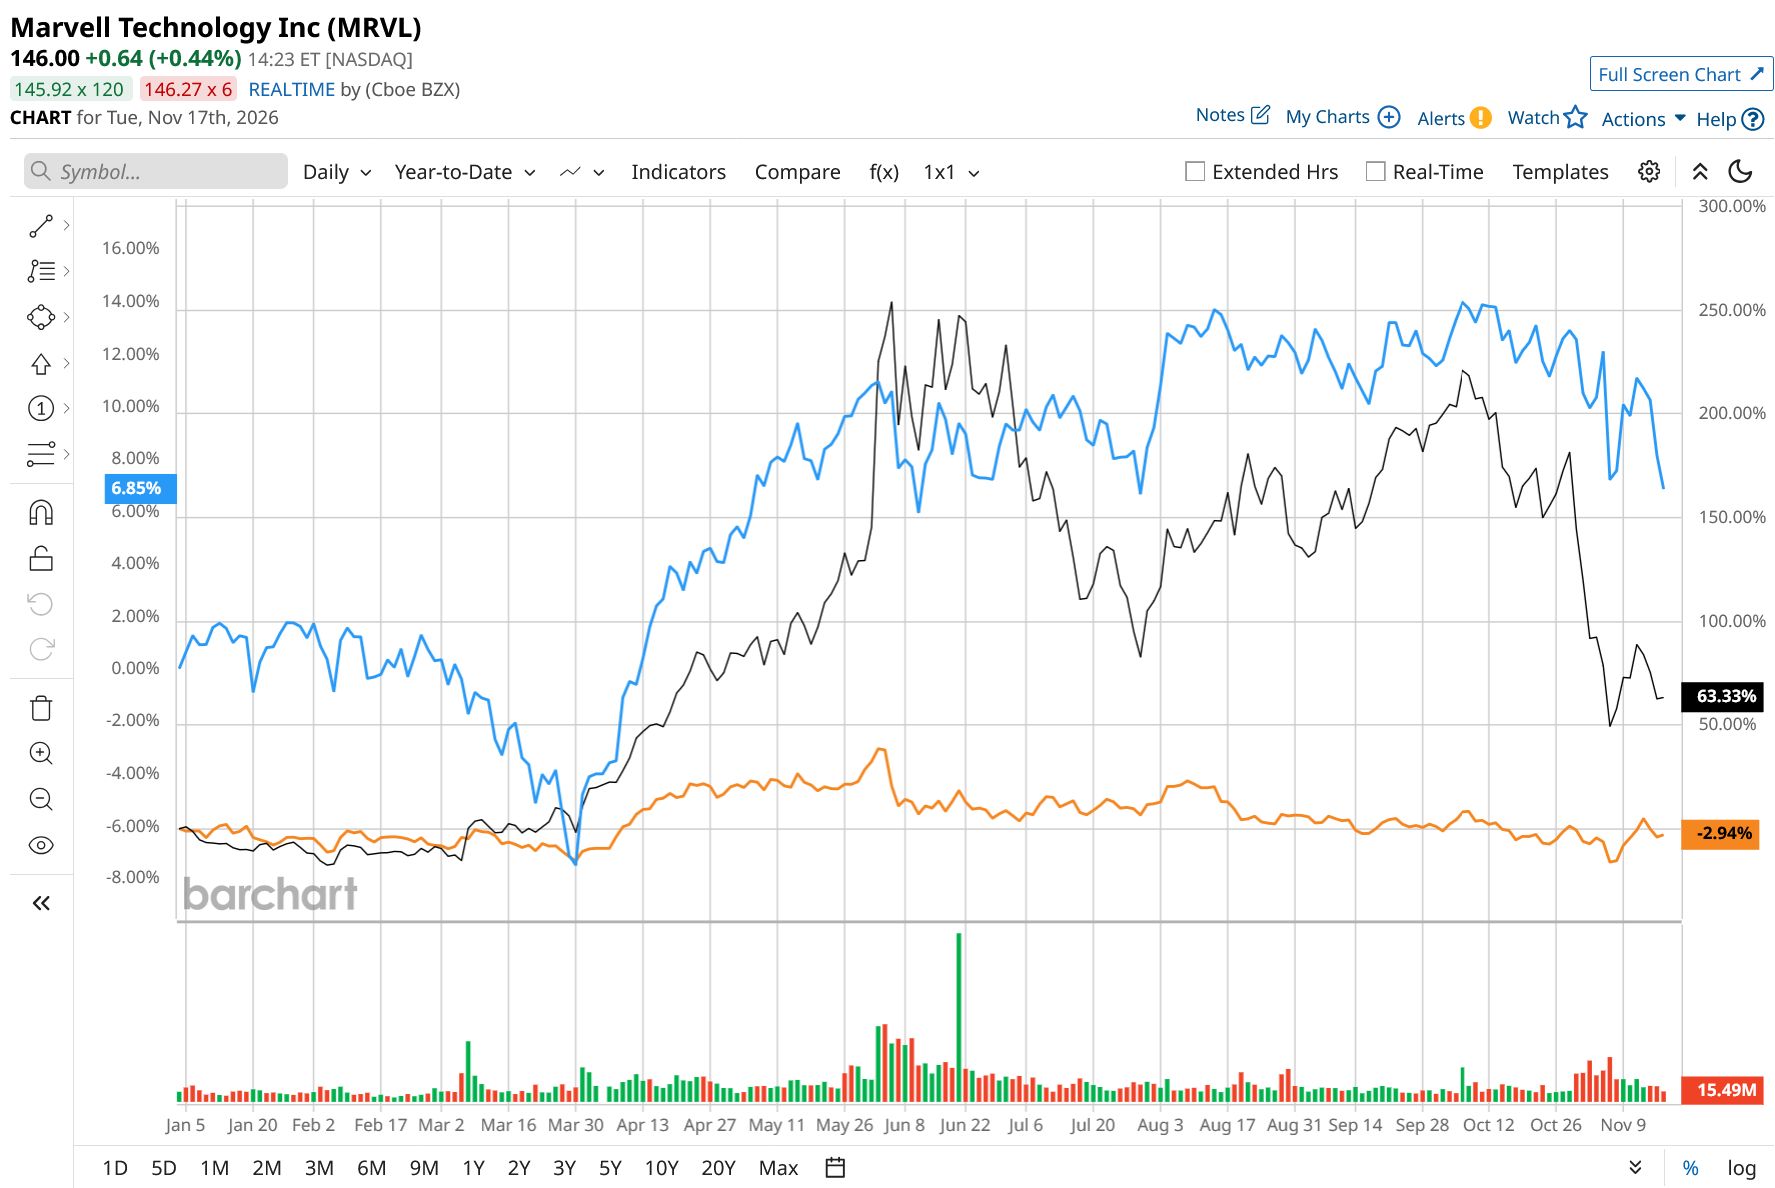
MRVL stock is up 71% so far this year, beating the S&P 500 Index ($SPX), whereas AVGO stock is down about 3%.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
Marvell Wants a Bigger Place in the AI Stack
Marvell’s $115 billion acquisition of Lumentum aims to unite two vital pillars of AI infrastructure into a single powerhouse. This all-stock deal merges Marvell’s custom AI accelerators, cutting-edge interconnects, networking switches, and semiconductor expertise with Lumentum’s high-performance lasers, advanced optical transceivers, and optical circuit switching. Lumentum additionally contributes its specialized compound semiconductor manufacturing, including indium phosphide technology, a key ingredient for next-generation optical components.
After the deal closes, current Marvell investors will likely own about two-thirds of the new company, while Lumentum investors own the rest. Because the deal uses a fixed share-exchange ratio, changes in Marvell's stock price before the deal closes will affect how much Lumentum shareholders receive. Both groups of shareholders face market swings during the long approval process. The risk impacts everyone.
Marvell expects this merger will create a broader connectivity portfolio, covering everything from links between data centers and servers to connections between processors within advanced AI systems. With this bold move, the company believes the combined business could tap into a $550 billion market opportunity, generating over $1 billion in annual cost synergies and boosting long-term revenue and margins. Marvell forecasts that the acquisition will begin adding to its adjusted EPS in the first year after completion. The companies are targeting a closing in early 2028, subject to regulatory clearance and shareholder approval.
So how does Broadcom fit into this? Broadcom stands out as a strong rival, powering hyperscalers’ vast data centers with its custom AI accelerators and networking silicon. Marvell operates in overlapping markets, including custom silicon, switching, and connectivity. The main idea is to move data, not just process it. AI accelerators need fast connections to communicate with each other, as well as with storage and networking gear. Copper is still useful, but as systems scale, distance, bandwidth, and power become bigger issues. Optical technology can send data farther and faster, and often does so more efficiently. Marvell already offers optical digital signal processors, interconnects, and switches. Lumentum adds advanced lasers, optical transceivers, switching technology, and specialized semiconductor manufacturing. According to Reuters, Marvell’s acquisition of Lumentum signals its intent to challenge Broadcom more aggressively for a share of AI investment.
This is Why Marvell Wants to Move Faster
Marvell’s fiscal 2027 second-quarter earnings show why Marvell wants to move faster. Revenue surged to $2.74 billion, a 37% year-over-year (YoY) leap and a 13% jump from the previous quarter. Data center sales soared to $2.17 billion, accounting for 79% of total revenue and up 46% from last year. The real powerhouse behind this momentum is the explosive demand for AI.
Looking ahead, Marvell projects Q3 revenue to hit $3.15 billion at the midpoint, denoting a 15% jump from last quarter and over 50% YoY growth. The company has also boosted its fiscal 2027 revenue target to about $12 billion, up from $11.5 billion, and raised its fiscal 2028 outlook to around $18 billion, up from $16.5 billion, aiming for roughly 50% growth.
Marvell's Q2 adjusted gross margin stood at 58.9%, while adjusted earnings per share climbed 40% YoY to $0.94. CFO Dan Durn said adjusted operating margin was expected to enter the company's 38% to 40% long-term target range as fiscal 2027 progressed.
Management pointed to surging demand across interconnect, switching, and custom silicon. Marvell reported strong demand for its 800-gigabit optical products, while its 1.6-terabit business is gaining momentum. The company expects its 51.2-terabit switching products to more than double this fiscal year. By fiscal 2028, management anticipates data center revenue to soar over 60%, with custom silicon revenue more than doubling. Marvell is also in talks with major customers about scale-up switches, each signifying a potential multibillion-dollar opportunity over their lifetimes.
Marvell ended the quarter with $4.96 billion in debt, but its net debt was low compared to its earnings at just 0.27 times EBITDA. Because Marvell will use its own shares, not cash, to buy Lumentum, current shareholders will own a smaller stake in the combined company. Still, Marvell will have to manage Lumentum's debt and other financial responsibilities while integrating the two businesses and keeping its own operations and growth on track.
How to Play MRVL Stock Now
Marvell has an attractive opportunity to become a bigger player in AI connectivity and challenge Broadcom, but the Lumentum deal raises the execution stakes. Marvell still has to show it can integrate this major acquisition, manage dilution, and turn its new technology into real, profitable growth.
MRVL offers substantial upside, but the acquisition raises the bar for successful integration and growth. Investors confident in Marvell’s ability could build exposure gradually around quarterly results and deal updates. More cautious investors might prefer to wait for clearer proof before investing.
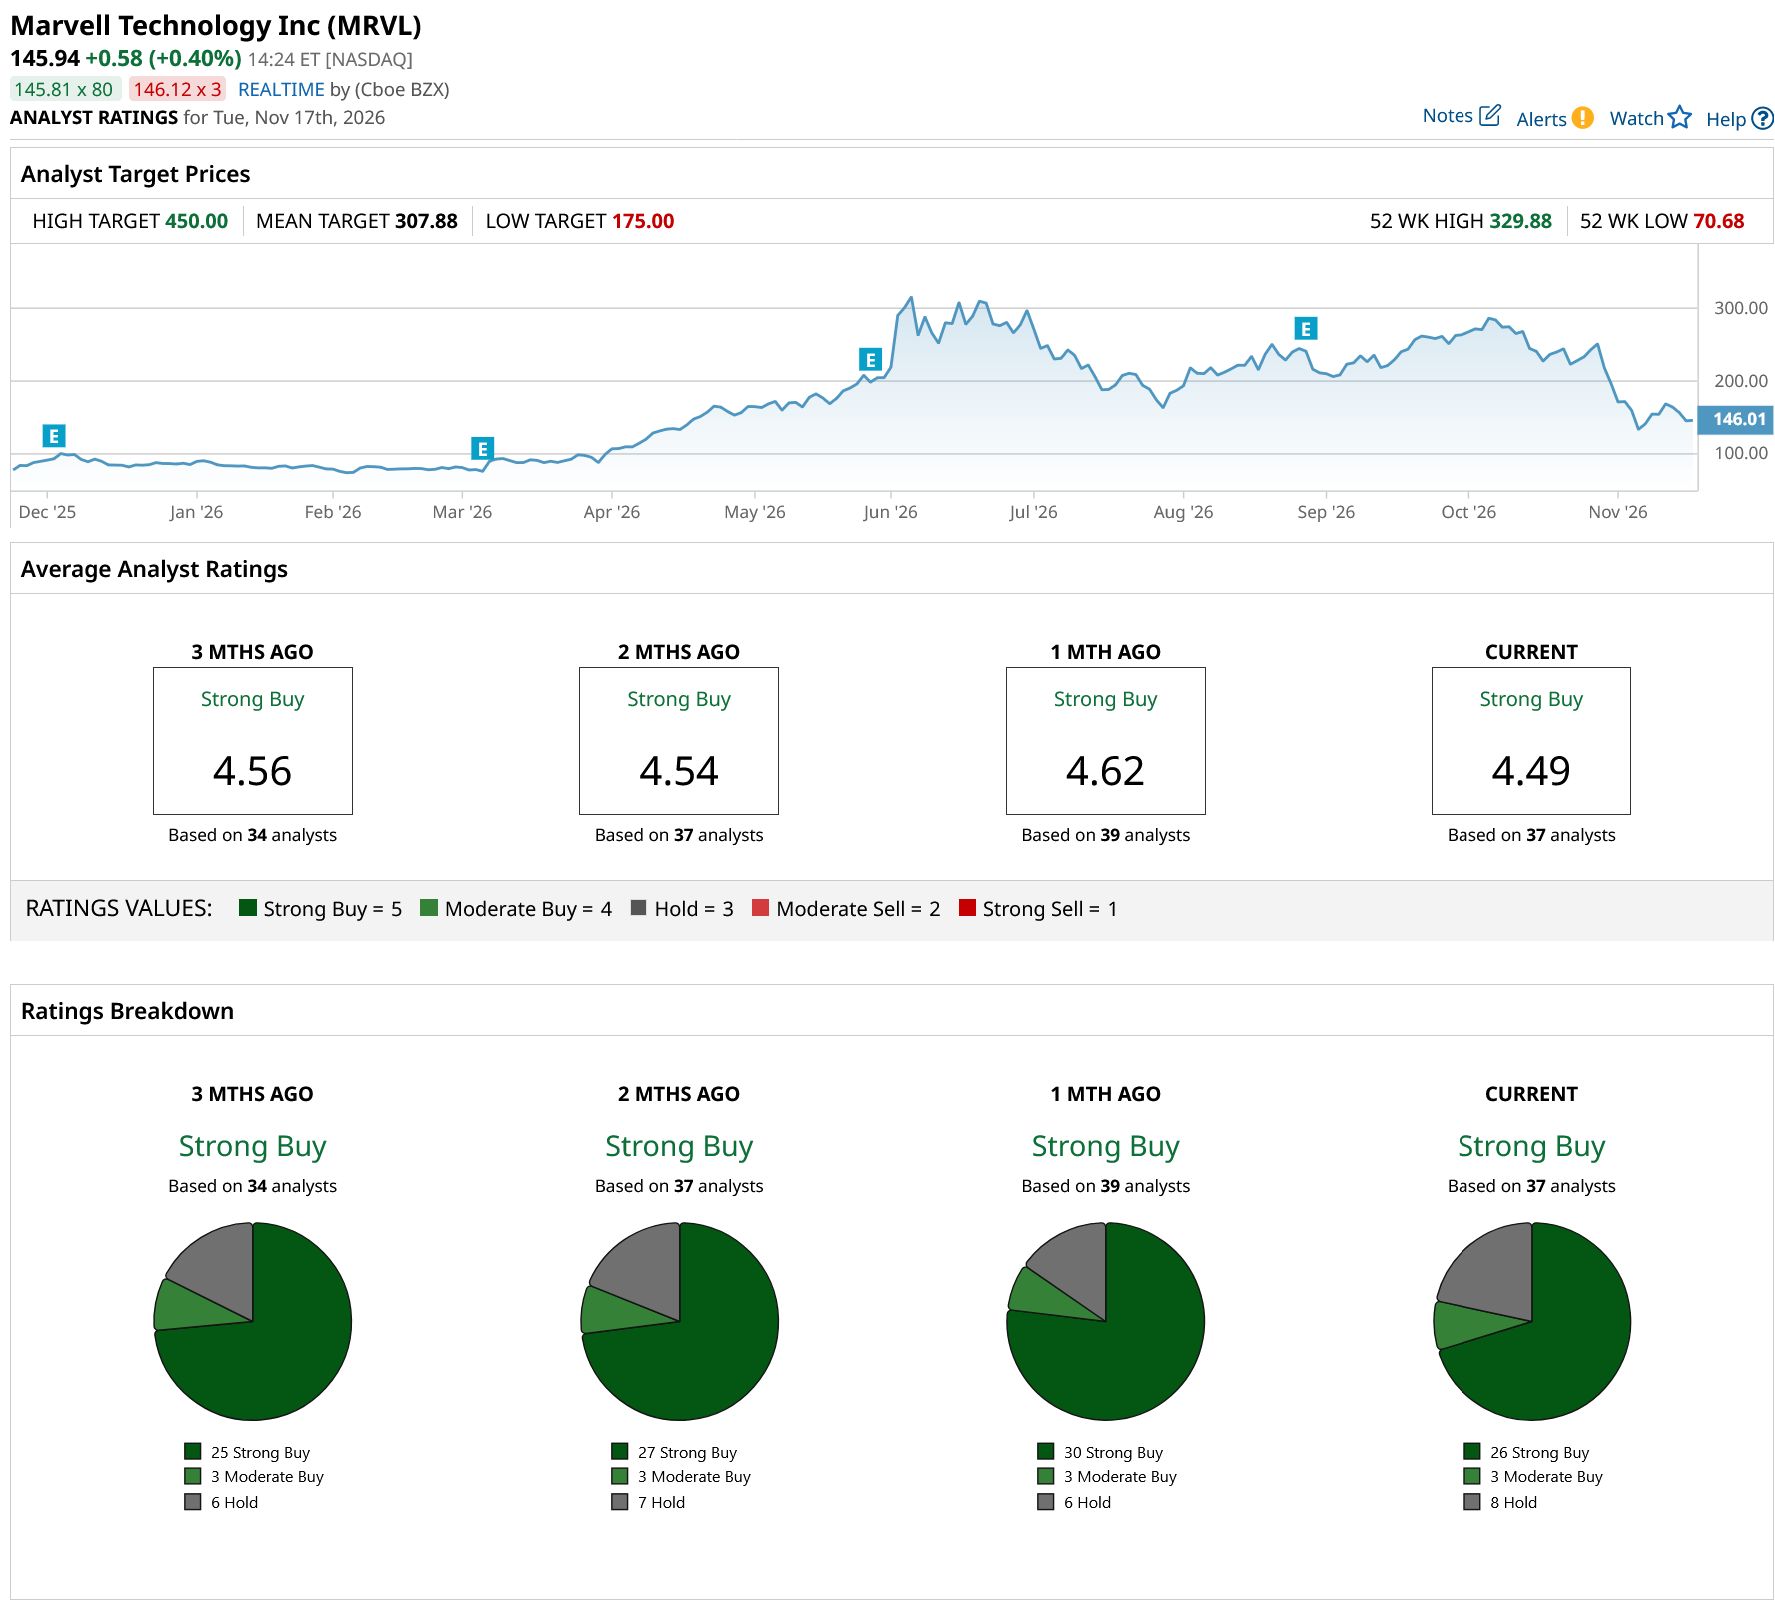
Overall, analysts continue to be strongly bullish about MRVL stock. Of the 37 analysts covering the stock, 26 rate it a “Strong Buy,” three a “Moderate Buy,” and eight a “Hold.” Marvell’s average price target of $307.88 indicates a possible upside of 111%. The most ambitious forecast of $450 hints at an exciting 208% upside from the current price.
 www.barchart.com
On the date of publication, Sushree Mohanty did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Ahead of Palo Alto Networks Earnings, Here's What Barchart Data Says Comes Next for PANW Stock Walmart vs. Target Stock: 1 Is Worth 14x the Other. Here’s Which Stock to Buy Before Earnings. How to Play OKLO Stock as Oklo Secures Key Fuel Supply for Its Ohio Plant Marvell Just Made a Massive Move Against Broadcom. How to Play MRVL Stock Now.