

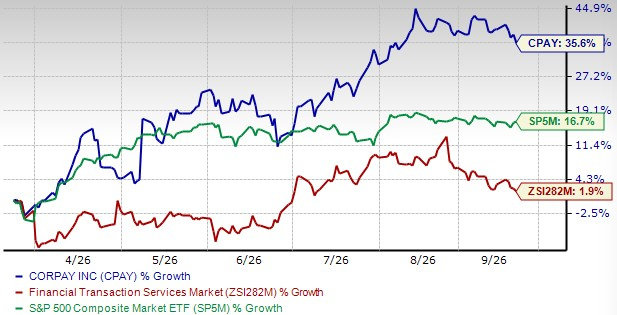
Corpay CPAY stock has escalated 35.6% over the past six months, outpacing the 1.9% uptick of the industry and the 16.7% return in the Zacks S&P 500 Composite.
6-Month Share Price Performance
The Zacks Consensus Estimate for CPAY’s 2026 revenues is $5.3 billion, implying 17.4% year-over-year growth. For 2026 EPS, the consensus mark is $27.4, up 28.2% year-over-year.
For 2027, the consensus mark for revenues is $5.7 billion, rising 8% year over year. Earnings per share are expected to increase 14.1% to $31.26.
Factors That Augur Well for CPAY’s Success
Solid Corporate Payments Momentum: Corpay’s Corporate Payments segment has been a persistent growth driver. During the second quarter of 2026, this segment delivered 16% year-over-year organic growth. The company sustained this growth following the first quarter of 2026. Corpay’s organic spend gained 43% to $95 billion, driven by strength across cross-border and payables.
Management anticipates this segment to sustain mid-teens-plus organic growth in the second half of 2026. This segment is fueled by robust customer activity, with bookings rising nearly 40% year over year. Notably, the company’s two biggest Corporate Payments deals, the Alpha buyout and the Avid investment, contributed 39 cents of cash EPS accretion in the quarter.
Cross-Border Expansion: Cross-border delivered strong sales and revenue performance during the second quarter of 2026, with Alpha integration being one of the prominent drivers. More than 80% of Alpha’s corporate volume had migrated to the company’s global technology platform by the second quarter of 2026. Corpay’s partnership with Mastercard secured 10 financial institutions, with 100 additional active in the pipeline.
Management is adding real-time private blockchain rails and investing to build out global banking and deposit offerings. This progress is a game-changer for middle market companies. This portfolio repositioning offers a $600-billion revenue total addressable market, giving the company the potential to expand 10 times, expecting $50 billion over time.
Impressive Cash Generation & Financial Flexibility: In the first half of 2026, Corpay held $18.9 billion in cash against a current debt of $3.8 billion, providing a significant cushion in handling short-term obligations. Management expected $1.8 billion in free cash flow in 2026 and $15 billion of available capital over its forecast period.
Corpay’s solid balance sheet remains healthy with leverage of 2.55 times and $1.6 billion of revolving-credit capacity at the end of the second quarter of 2026. The company refinanced its debt stack, extended maturities and reduced borrowing costs, bolstering its capacity to fund prudent M&A and shareholder returns.
Risks Faced by Corpay
CPAY Shoulders Vehicle Payments Growth Pressure: U.S. Vehicle Payments remain hindered as the company reallocates sales investment toward the faster-growing Corporate Payments business. In the second quarter of 2026, year-over-year organic growth was 8%, while U.S. growth reflected management’s decision to reallocate sales and investment toward Corporate Payments’ higher return opportunities. Declining investment or weaker sales execution is anticipated to make sustaining high-single-digit growth more difficult.
Limited Margin Expansion: The company continues to invest in sales and product development to sustain double-digit organic growth. In the second quarter of 2026, operating costs gained 9% year over year due to sales investment and higher credit losses.
Management anticipates margins in the second half of the year to be slightly below the preceding year level and does not expect substantial margin expansion, demonstrating a trade-off between investment and profitability.
CPAY’s Zacks Rank & Stocks to Consider
The company currently carries a Zacks Rank #3 (Hold).
Some better-ranked stocks in the broader Zacks Business Services sector are Evertec EVTC and Coherent Corp. COHR, each currently carrying a Zacks Rank #2 (Buy). You can seethe complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Evertec has a long-term earnings growth expectation of 10%. EVTC delivered a trailing four-quarter earnings surprise of 3.8%, on average.
Coherent Corp has a long-term earnings growth expectation of 52.5%. COHR delivered a trailing four-quarter earnings surprise of 6.2%, on average.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Corpay, Inc. (CPAY): Free Stock Analysis Report
Coherent Corp. (COHR): Free Stock Analysis Report
Evertec, Inc. (EVTC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).