

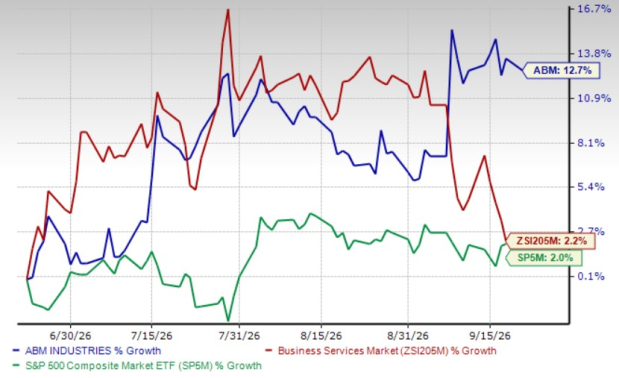
ABM ABM stock has gained 12.7% over the past three months, outperforming the industry’s 2.2% growth and the Zacks S&P 500 Composite's 2% return.
Three-Month Share Price Performance
Image Source: Zacks Investment Research
Let us delve deeper into the factors that have contributed to the company’s outperformance.
High-Growth Infrastructure Markets Expand Opportunities
ABM is gaining momentum across semiconductor, microgrid and data center markets, strengthening its long-term growth profile. Through the first nine months of fiscal 2026, semiconductor revenues reached about $300 million and grew 65% organically, while microgrid revenues of roughly $300 million increased 17% and data center revenues of about $175 million rose 8%.
Recently acquired WGNSTAR has expanded ABM’s semiconductor capabilities into specialized services inside fabrication facilities and has already generated several cross-selling wins. Growth prospects remain favorable, with a much larger data center pipeline than a year ago and a roughly $20 million Army Corps of Engineers microgrid project planned for 2027. These expanding, higher-growth infrastructure businesses should support ABM’s revenue diversification and longer-term earnings potential.
Cash Flow & Leverage Provide Financial Flexibility
ABM’s improving cash generation is strengthening its financial flexibility and supporting shareholder value creation. In the third quarter of fiscal 2026, operating cash flow reached $146.8 million and free cash flow totaled $128.4 million. Through nine months, operating cash flow increased to $275 million from $101 million, while free cash flow rose to $199.6 million from $42.4 million, reflecting improved working-capital management and greater stability in resource planning.
The stronger cash profile is helping the company reduce leverage. Total debt declined to $1.8 billion at the end of the third quarter of fiscal 2026, while leverage improved to 2.9X from 3.2X in the prior quarter. The company ended the period with $605.8 million of available liquidity, including $110.5 million of cash and added a $300 million accounts receivable financing facility. Management expects deleveraging by fiscal year-end. Sustained cash conversion enables the company to reduce debt, fund growth investments and support shareholder returns through dividends and other capital-allocation initiatives.
Raised Outlook Promises Greater Capital Returns
ABM raised its adjusted earnings outlook to $3.95-$4.10 per share from the earlier expectation of $3.85-$4.15, increasing the midpoint. Organic revenue growth is still expected toward the high end of 3-4%, with total revenue growth toward the high end of 4-5%. Segment operating margin is projected to be between 7.7% and 7.8% compared with the prior range of 7.8-8%. The company lifted its full-year operating cash flow expectation to about $300 million and free cash flow to about $210 million, up $25 million from the prior free cash flow outlook. The higher free cash flow outlook promises higher shareholder returns while supporting ongoing business needs. The raised earnings midpoint also improves visibility into full-year performance.
ABM’s Zacks Rank & Stocks to Consider
ABM currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
A couple of better-ranked stocks in the broader Business Services sector are Bright Horizons Family Solutions Inc. BFAM and TrueBlue, Inc. TBI.
Bright Horizons Family Solutions carries a Zacks Rank #2 (Buy) at present. It has a long-term earnings growth expectation of 13.9%.
BFAM delivered a trailing four-quarter earnings surprise of 7.6%, on average.
TrueBlue carries a Zacks Rank #2 at present. It has a long-term earnings growth expectation of 14%.
TBI beat earnings estimates in three of the last four reported quarters and missed once, with an average earnings surprise of 22.4%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ABM Industries Incorporated (ABM): Free Stock Analysis Report
TrueBlue, Inc. (TBI): Free Stock Analysis Report
Bright Horizons Family Solutions Inc. (BFAM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).