

iRhythm Holdings IRTC is well-positioned for solid growth over the next few quarters, courtesy of its strong second-quarter 2026 results and structural market expansion. The company’s investments in AI, large-scale ECG data and clinical validation strengthen its competitive moat, while its push into predictive healthcare opens new long-term opportunities. However, reimbursement and regulatory pressures may pose challenges to sustained growth.
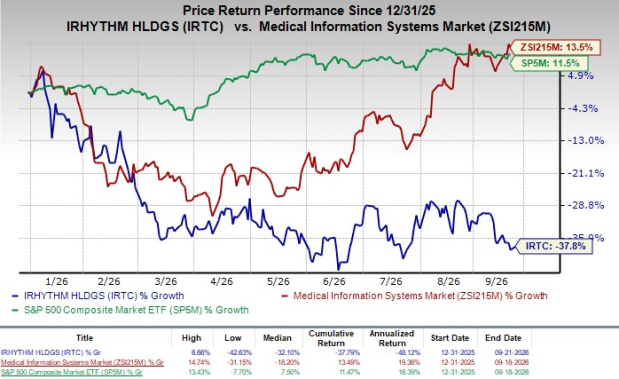
Shares of this Zacks Rank #3 (Hold) company have lost 37.8% so far this year against the industry’s 13.5% growth. However, the S&P 500 Index has increased 11.5% in the same timeframe.
iRhythm, a leader in ambulatory cardiac monitoring operating a device-enabled digital diagnostics platform that integrates wearable biosensors (Zio), FDA-cleared AI algorithms and enterprise clinical workflows delivered through EHR systems, has a market capitalization of $3.6 billion. The company’s earnings surpassed estimates in all the trailing four quarters, delivering an average surprise of 1842.7%.
Image Source: Zacks Investment Research
Positive Factors Driving IRTC Stock
Structural Market Expansion Through Primary Care & Population Health: iRhythm is moving arrhythmia detection upstream from specialists into primary care, value-based care and population health, expanding the settings where long-duration monitoring can be prescribed.
In the second quarter of 2026, innovative channels were the company’s fastest-growing channel, and management said that new partners continued to join across value-based care, primary care and population health. Workflow integration is also deepening. Approximately 60% of second-quarter 2026 volume came from EHR-integrated accounts, up from roughly 53% in the first quarter, and nearly 80 of the top 100 customers were integrated. The company also signed two commercial agreements through its Luum partnership for predictive identification workflows.
AI, Data and Clinical Evidence Create a Durable Competitive Moat: iRhythm's extensive data foundation, built on more than 3 billion hours of curated ECG data and over 12 million patient reports, continues to strengthen its push into predictive cardiac care as the industry shifts toward earlier disease detection. In the second quarter of 2026, the company expanded its collaboration with Desert Oasis Healthcare and secured two commercial agreements through Luum to integrate predictive workflows with cardiac monitoring, while early pilot programs demonstrated more than 85% accuracy in identifying patients with clinically significant arrhythmias before diagnosis.
Meanwhile, the company's productivity initiatives gained momentum following FDA clearance of its third-generation algorithm, which management expects to launch in the first half of 2027. The new algorithm is projected to cut technician review time by up to 50% and generate approximately $100 million in cumulative cost savings over the next five years.
Strong Q2 Results: iRhythm delivered a strong second quarter, delivering solid earnings and revenue growth. The quarter reflected broad-based commercial momentum across cardiology, primary care, innovative channels and international markets. Innovative channels were the fastest-growing area, supported by value-based care, primary care and population-health partnerships.
Approximately 60% of volumes now come from EHR-integrated accounts, while nearly 80 of iRhythm’s top 100 customers are integrated, helping streamline workflows and expand patient access. On the innovation front, iRhythm secured FDA clearance for its third-generation algorithm, which management expects to reduce clinical technician review time by as much as 50% and generate approximately $100 million in cumulative cost savings over five years.
Headwind That May Affect IRTC Stock
Reimbursement and Regulatory Pressures: Despite strong clinical validation, iRhythm continues to face reimbursement-related challenges in international markets. In Japan, Zio is currently reimbursed at rates comparable to traditional Holter monitors, which management considers inadequate and contingent on demonstrating superior clinical outcomes to support future pricing improvements. Similar issues persist in Europe, where reimbursement frameworks are highly fragmented and require extensive negotiations.
In the United States, both Medicare and commercial insurers are focused on cost-effectiveness, which could hinder adoption if budget constraints tighten. The uneven pace of value-based care adoption introduces further uncertainty, as shifts in reimbursement policies may influence testing volumes and pricing.
Estimate Trend
iRhythm is witnessing a stable estimate revision trend for 2026. In the past 30 days, the Zacks Consensus Estimate for earnings has remained stable at 60 cents per share.
The Zacks Consensus Estimate for third-quarter 2026 revenues and earnings per share is pegged at $222.3 million and 2 cents, respectively.
Stocks to Consider
Some better-ranked stocks from the broader medical space are Globus Medical GMED, Veracyte VCYT and West Pharmaceutical WST.
Globus Medical, currently carrying a Zacks Rank #2 (Buy), reported a second-quarter 2026 adjusted earnings per share (EPS) of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Veracyte, currently flaunting a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted EPS of 54 cents, which surpassed the Zacks Consensus Estimate by 25.6%. Revenues of $150.3 million beat the Zacks Consensus Estimate by 4.1%.
VCYT has an estimated earnings growth rate of 8.4% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 41.8%.
West Pharmaceutical, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $2.37, which beat the Zacks Consensus Estimate by 13.9%. Revenues of $872.3 million surpassed the Zacks Consensus Estimate by 4.2%.
WST has an estimated long-term earnings growth rate of 16%. WST’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 17.4%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
iRhythm Holdings, Inc. (IRTC): Free Stock Analysis Report
West Pharmaceutical Services, Inc. (WST): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Veracyte, Inc. (VCYT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).