

G-III Apparel Group, Ltd. GIII views Donna Karan as one of its most powerful growth opportunities, supported by solid consumer demand, healthy full-price selling and aspirational positioning. Management sees significant room to expand the brand across categories, channels and geographies, with product newness, lifestyle extensions and digital-first marketing helping broaden its reach and strengthen consumer engagement.
That momentum was evident in the second quarter of fiscal 2027, when Donna Karan sales increased more than 45% year over year. Digital performance also remained strong, supported by growth in traffic, conversion and average unit retail. The dress business was a standout, while Donna Karan Weekend, launched last November, continued to perform well.
Category expansion is adding another growth lever. Handbags delivered double-digit growth during the quarter, while footwear also performed well. Footwear distribution is expanding this fall through additional doors at Nordstrom, Macy’s and Dillard’s, extending Donna Karan’s presence across major retail partners and supporting a more diversified business mix.
Marketing initiatives are designed to broaden awareness. Kendall Jenner is the face of Donna Karan’s Fall 2026 global campaign, which management believes can introduce the brand to new audiences worldwide. Donna Karan will also participate in Macy’s celebration of American fashion through a limited-edition capsule reimagining iconic pieces from the brand’s legacy.
Management continues to see meaningful long-term growth potential for Donna Karan. At the company level, G-III raised fiscal 2027 adjusted earnings per share (EPS) guidance to $2.20-$2.30 and continues to expect its go-forward portfolio to grow at a high-single-digit rate, excluding Marc Jacobs from the outlook. These trends provide a supportive backdrop for Donna Karan as G-III shifts toward a higher-margin owned-brand mix.
GIII’s Price Performance, Valuation & Estimates
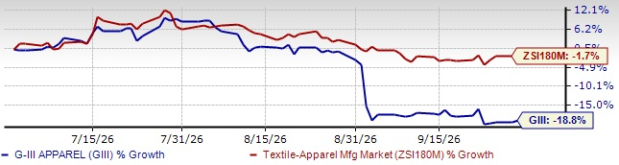
Shares of G-III have lost 18.8% over the past three months compared with the industry’s 1.7% decline.
Image Source: Zacks Investment Research
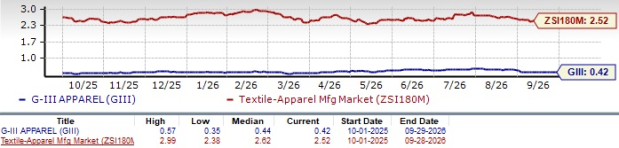
From a valuation standpoint, GIII trades at a forward price-to-sales ratio of 0.42, below the industry’s average of 2.52. It has a Value Score of A.
Image Source: Zacks Investment Research
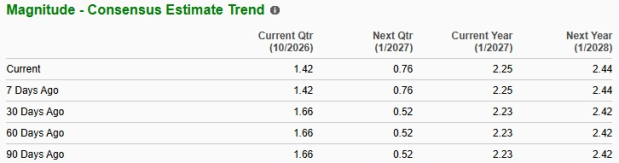
The Zacks Consensus Estimate for G-III’s fiscal 2027 earnings implies a year-over-year decline of 13.8%, whereas the estimate for fiscal 2028 indicates a decline of 8.4%. Earnings estimates for fiscal 2027 and 2028 have been revised upward by 2 cents each over the past 30 days.
Image Source: Zacks Investment Research
GIII currently carries a Zacks Rank #3 (Hold).
Key Picks
Genesco Inc. GCO is a Nashville-based specialty retailer and branded company. It sells footwear and accessories through retail stores. The company flaunts a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Genesco’s current fiscal-year earnings indicates 62.1% growth from the year-ago actuals. GCO delivered a trailing four-quarter average earnings surprise of 11.2%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. Designer Brands currently carries a Zacks Rank #2 (Buy).
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company carries a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales suggests growth of 14% and 9.5%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
G-III Apparel Group, LTD. (GIII): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
Genesco Inc. (GCO): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).