

Celestica, Inc. CLS shares have gained 25.7% year to date compared with the Electronics - Manufacturing Services industry’s growth of 39.6%. The stock has outperformed the Zacks Computer & Technology sector and the S&P 500 during the same time frame.
Image Source: Zacks Investment Research
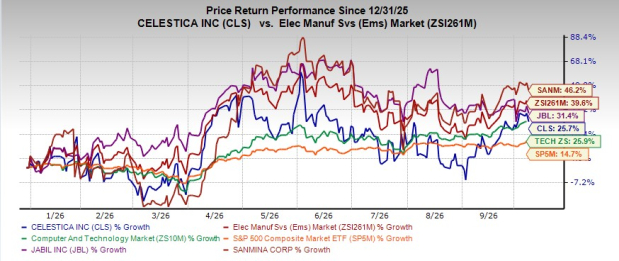
The company has underperformed its peers like Jabil, Inc. JBL and Sanmina Corporation SANM. Shares of Jabil have jumped 31.4%, while shares of Sanmina have risen 46.2%.
Key Growth Drivers for CLS
Celestica is benefiting from the rapid expansion of AI infrastructure and hyperscaler spending. Demand for higher-speed networking is supporting strong growth in its 800G products. The company is set to begin mass-production programs for 1.6T networking platforms. Its enterprise business is also benefiting from the ramp-up of AI/ML compute programs. Beyond existing networking programs, Celestica is expanding into custom AI infrastructure.
The company is set to manufacture custom rack systems for OpenAI. The company is working with OpenAI and Broadcom on multigenerational custom accelerator platforms. Celestica is also positioned to benefit from Advanced Micro Devices’ growing AI infrastructure initiatives. Its involvement in AMD’s Helios scale-up platform represents a multibillion-dollar opportunity.
The Connectivity & Cloud Solutions segment outlook remains strong. It has generated $3.81 billion of second-quarter revenues, up 84% year over year and accounting for 81% of total company revenue. Management expects CCS revenues to grow approximately 85% in 2026, supported by continued 800G adoption, upcoming 1.6T ramps and strong AI-compute demand.
Celestica’s focus on product diversification and increasing its presence in high-value markets is positive. Its strong research and development foundations allow it to produce high-volume electronic products and highly complex technology infrastructure products for a wide range of industries. The company continues to enhance its manufacturing, engineering, design, quality and supply-chain capabilities while developing trusted relationships with leading customers.
Key Challenges
Customer concentration remains one of Celestica's biggest vulnerabilities. The company's top 10 customers represented about 79% of 2025 revenues. Separately, in the second quarter of 2026, three customers each represented at least 10% of total revenues, accounting for 32%, 17% and 14%, respectively. A slowdown, program delay or loss of a major customer could therefore have a meaningful impact on revenue and profitability.
Celestica operates in a crowded electronics manufacturing services market and faces major competitors such as Foxconn, Jabil, Flex and Sanmina. Maintaining its competitive position requires continued investment in engineering, product development and manufacturing capabilities, which can put pressure on margins.
Despite the current AI-led growth, parts of Celestica's business remain sensitive to economic cycles. Customers in industrial, communications and enterprise markets can reduce capital spending during periods of economic weakness, potentially lowering factory utilization. This can put pressure on margins.
Estimate Revision Trend
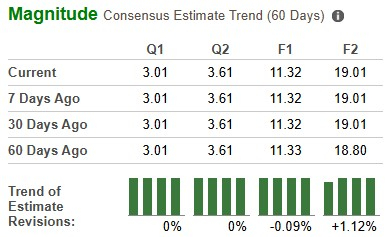
Earnings estimates for Celestica for 2026 have decreased, but 2027 estimates have increased over the past 60 days.
Image Source: Zacks Investment Research
Key Valuation Metric of CLS
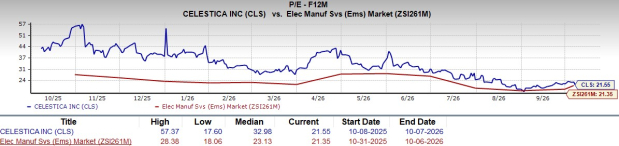
From a valuation standpoint, CLS is currently trading at a premium compared to the industry. Going by the price/earnings ratio, the company’s shares currently trade at 21.55 forward 12-month earnings, higher than 21.35 for the industry.
Image Source: Zacks Investment Research
End Note
Celestica's growth outlook is being driven primarily by AI infrastructure, hyperscaler spending and 800G/1.6T networking demand. The company’s strong focus on product diversification is a positive factor. However, high customer concentration, intense competition and cyclical exposure remain key risks. Hence, with a Zacks Rank #3 (Hold), Celestica appears to be on a middle-of-the-road track, suggesting that investors should exercise caution while trading the stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Celestica, Inc. (CLS): Free Stock Analysis Report
Jabil, Inc. (JBL): Free Stock Analysis Report
Sanmina Corporation (SANM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).