

Consumer financial services company, Synchrony Financial SYF, is set to report third-quarter 2026 results on Oct. 20, before the opening bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at $2.48 per share on revenues of $4.84 billion.
The third-quarter earnings estimate has witnessed three upward revisions and no downward movements over the past 60 days. However, the bottom-line projection indicates a year-over-year decrease of 13.3%. But the Zacks Consensus Estimate for quarterly revenues implies year-over-year growth of 2.6%.
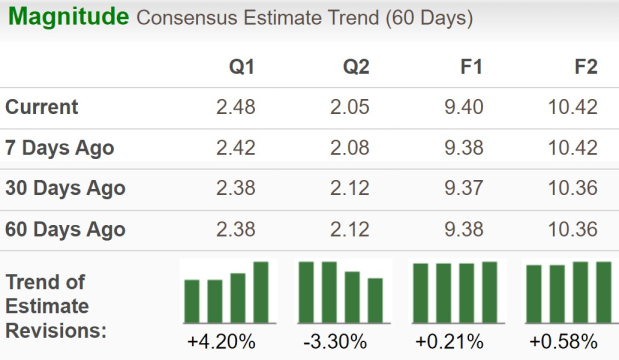
For full-year 2026, the Zacks Consensus Estimate for Synchrony Financial’s revenues is pegged at $19.07 billion, implying an increase of 3.3% year over year. However, the consensus mark for the current year EPS is pegged at $9.40, signaling a decline of around 0.2% on a year-over-year basis.
SYF’s earnings beat the consensus estimate in three of the past four quarters and met once, with the average surprise being 15.5%.
Synchrony Financial Price and EPS Surprise
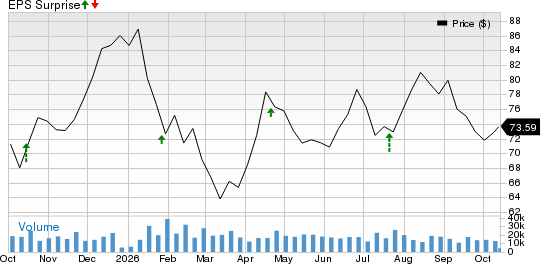
Synchrony Financial price-eps-surprise | Synchrony Financial Quote
Q3 Earnings Whispers for SYF
Our proven model predicts a likely earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That is precisely the case here.
Synchrony Financial has an Earnings ESP of +5.87% and carries a Zacks Rank #3 at present. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
What’s Shaping SYF’s Q3 Results?
Synchrony Financial is expected to have seen advantages in the third quarter from increased interest-earning assets and higher purchase volumes. Our model predicts interest and fees on loans of $5.6 billion for the quarter, up 1.7% from a year ago. Higher figures from Health & Wellness and Digital are likely to anchor the results.
The consensus mark for total purchase volumes indicates 7% year-over-year growth. The Zacks Consensus Estimate indicates that the total average active accounts are likely to increase 0.7% in the third quarter. SYF is expected to witness a 2.4% increase in average interest-earning assets.
The consensus mark for the net charge-offs ratio is pegged at 5.01, down from 5.16 a year ago. The above-mentioned factors are likely to have benefited the company in the third quarter, positioning it for an earnings beat.
However, Synchrony Financial is expected to have incurred increased information processing and employee costs in the third quarter, partially offsetting the positives. Also, RSA is expected to have increased nearly 10% year over year in the third quarter.
The Zacks Consensus Estimate for net interest margin is pegged at 15.50%, down from 15.62% achieved a year ago, decreasing its profitability.
Other Stocks That Warrant a Look
Here are some other companies worth considering from the broader Finance space, as our model shows that these, too, have the right combination of elements to beat on earnings this time around:
Chime Financial, Inc. CHYM has an Earnings ESP of +4.19% and a Zacks Rank of 1 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Chime Financial’s bottom line for the to-be-reported quarter is pegged at 9 cents, which indicates 160% year-over-year growth. The consensus estimate for CHYM’s revenues is pegged at $705.2 million, a 29.7% increase from a year ago.
Virtu Financial, Inc. VIRT has an Earnings ESP of +1.88% and a Zacks Rank of 1 at present.
The Zacks Consensus Estimate for Virtu Financial’s bottom line for the to-be-reported quarter is pegged at $1.49, growth of 41.9% from a year ago. The consensus estimate for VIRT’s revenues is pegged at $604.79 million, a 29.5% year-over-year jump.
Credicorp Ltd. BAP has an Earnings ESP of +4.71% and a Zacks Rank #3 at present.
The Zacks Consensus Estimate for Credicorp’s bottom line for the to-be-reported quarter is pegged at $7.51, which indicates 21.7% year-over-year growth. The consensus estimate for BAP’s revenues is pegged at $1.84 billion, an 11.7% increase from a year ago.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Synchrony Financial (SYF): Free Stock Analysis Report
Credicorp Ltd. (BAP): Free Stock Analysis Report
Virtu Financial, Inc. (VIRT): Free Stock Analysis Report
Chime Financial, Inc. (CHYM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).