

Nutrien Ltd. NTR is benefiting from favorable demand for crop nutrients, ongoing cost-reduction and productivity initiatives and higher fertilizer prices. However, elevated input costs and constrained nitrogen volumes following facility shutdowns remain headwinds that could weigh on margins.
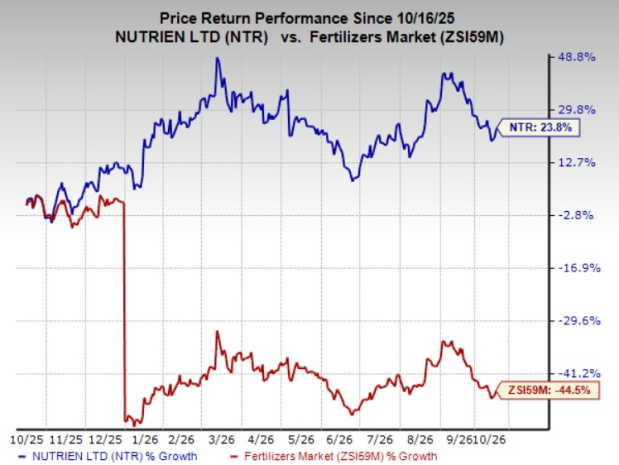
The NTR stock has gained 23.8% over the past year, compared with the Zacks Fertilizers industry’s 44.5% decline.
Image Source: Zacks Investment Research
Let’s find out why NTR stock is worth retaining at the moment.
NTR Gains on Healthy Demand, Higher Prices & Cost Cuts
Nutrien continues to benefit from favorable crop nutrient fundamentals, particularly in potash. Management expects global potash shipments of 74-77 million tons in 2026, with demand supported by favorable affordability. First-half 2026 potash sales volumes reached a record 7.45 million tons, driven by low inventories and offshore demand, prompting the company to raise full-year sales volume guidance to 14.2-14.8 million tons.
Nitrogen fundamentals also remain supportive, with the global market expected to stay tight in the second half of 2026 due to trade disruptions, production outages, elevated energy prices and strong import demand from India and Brazil.
Cost and operational efficiency initiatives are also expected to aid the company’s performance. Nutrien continues to improve the cost position of its upstream assets while focusing spending on productivity and reliability. Potash controllable cash cost of product manufactured remained below $60 per ton in the first half of 2026, alongside record production and continued mine automation. Nitrogen also benefited from lower overall natural gas costs and reliability initiatives at its North American facilities.
Fertilizer pricing remained favorable through the first half of 2026 after the recovery that began in 2025. Potash average net selling price increased 13% year over year to $266 per ton in the first half, while nitrogen average net selling price rose 14% to $416 per ton. These gains helped Potash's adjusted EBITDA increase 15% to $1.24 billion, and Nitrogen adjusted EBITDA rise 4% to $1.12 billion despite lower nitrogen volumes.
Management also noted that global urea prices strengthened in the third quarter of 2026 after a seasonal decline late in the second quarter, while potash markets remained constructive on favorable affordability and stable supply. Phosphate benchmarks were also higher, although sulfur costs offset the pricing benefit.
Nutrien Faces Sulfur Costs and Nitrogen Volume Constraints
Nutrien remains exposed to volatility in sulfur and natural gas, with elevated sulfur costs posing the biggest challenge. Constrained sulfur availability has reduced global phosphate operating rates and pressured phosphate economics, causing phosphate adjusted EBITDA to fall 48% year over year to $80 million in the first half of 2026 and 75% to $23 million in the second quarter, despite higher benchmarks and sales volumes. Management expects tight sulfur supply and elevated costs to limit phosphate margin recovery.
Nitrogen volumes also remain constrained following the shutdown of the Trinidad facility in October 2025 and New Madrid at year-end 2025. Second-quarter volumes fell 25% and first-half volumes declined 16%, although 2026 guidance remains at 9.2-9.7 million tons, supported by reliability improvements, debottlenecking and higher ammonia operating rates expected in the fourth quarter.
Nutrien Ltd. Price and Consensus
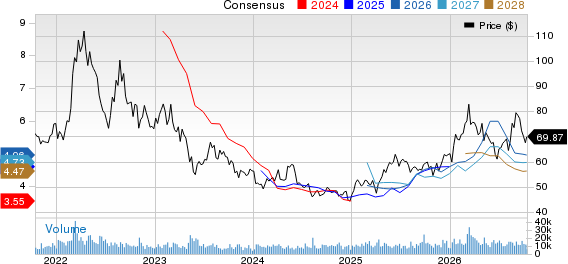
Nutrien Ltd. price-consensus-chart | Nutrien Ltd. Quote
NTR’s Zacks Rank & Key Picks
NTR currently carries a Zacks Rank #3 (Hold).
Better-ranked stocks in the Basic Materials space are Reliance, Inc. RS, Air Products and Chemicals, Inc. APD and Axalta Coating Systems Ltd. AXTA.
RS sports a Zacks Rank #1 (Strong Buy) while APD and AXTA carry a Zacks Rank #2 (Buy) each. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for RS’ 2026 earnings is pegged at $23.70 per share, indicating a 66.2% year-over-year increase. The consensus estimate for RS’s current-year earnings has been revised 3.7% higher over the past 60 days.
The Zacks Consensus Estimate for APD’s current fiscal-year earnings is pinned at $13.46 per share, suggesting an 11.9% year-over-year growth. The consensus estimate for APD’s current fiscal-year earnings has been revised 0.2% higher over the past 60 days.
The Zacks Consensus Estimate for AXTA’s 2026 earnings is pegged at $2.63 per share, indicating a rise of 5.6% year over year. Its earnings beat the Zacks Consensus Estimate in three of the trailing four quarters and missed once, with an average surprise of 6.5%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Nutrien Ltd. (NTR): Free Stock Analysis Report
Air Products and Chemicals, Inc. (APD): Free Stock Analysis Report
Reliance, Inc. (RS): Free Stock Analysis Report
Axalta Coating Systems Ltd. (AXTA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).