

West Pharmaceutical Services, Inc. WST is well positioned for growth, backed by strong demand for HVPs, expanding biologics exposure and regulatory-driven Annex 1 conversions. However, tariff impacts and weak West Vantage results, which were hurt by a cyber incident, remain concerning.
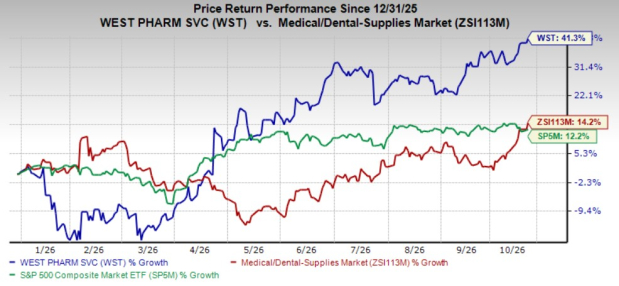
Shares of this Zacks Rank #2 (Buy) company have gained 33.1% year to date compared with the industry's 3.7% growth. The S&P 500 Index has risen 10% in the same time frame.
West Pharmaceutical, with a market capitalization of $27.02 billion, is a leading global manufacturer that designs and produces technologically advanced, high-quality, integrated containment and delivery systems for injectable drugs and healthcare products. Its earnings are anticipated to improve 16% over the next five years. The company delivered a trailing four-quarter average earnings surprise of 17.4%.
Image Source: Zacks Investment Research
Positive Factors Driving WST’s Prospects
Strong Biologics Exposure Supports Higher-Value Growth: West Pharma’s biologics franchise remains an important growth driver, as newer biologic medicines increasingly require sophisticated primary-containment solutions. Management noted that approximately 75% of new drug approvals in 2025 were large molecules, while the company continues to achieve win rates above 90% for these new molecules.
Products such as NovaPure and FluroTec are well positioned to capitalize on this trend, given their advanced containment capabilities and higher average selling prices (ASPs) and margins. Continued biologic launches, geographic expansion and additional indications could support growth through new customer wins and increased adoption of existing products.
Annex 1 Upgrades Create a Multi-Year Growth Opportunity: West Pharma is benefiting from increasing customer demand for higher-value containment solutions as pharmaceutical manufacturers address Annex 1 sterility and contamination-control requirements. Management reported nearly 800 active projects, up 50% year over year, indicating that the opportunity remains in its early stages.
Annex 1 and related upgrades are expected to contribute approximately 200 basis points to revenue growth in 2026, with further upside possible. By offering pharmaceutical washing and Envision inspection alongside existing components, West Pharma can improve ASPs and margins without requiring a proportionate increase in component volumes. Additionally, its Standard Products portfolio provides a pipeline for future high-value product (HVP) conversions as customers seek more advanced containment, inspection and finishing capabilities.
Delivery Devices Show Broad-Based Growth Momentum: West Pharma’s HVP Delivery Devices business delivered 29% organic growth in the second quarter, supported by strength across its portfolio. While SmartDose 3.5 benefited from customer orders ahead of the July 1 transaction, management indicated that other offerings, including SelfDose and Crystal Zenith, also performed well.
SelfDose continues to expand across customers and drug molecules, while Crystal Zenith addresses high-value biologics applications, including cell and gene therapies. Management expects the core delivery-device portfolio to maintain growth momentum in the third and fourth quarters. This suggests that the segment’s improvement extends beyond SmartDose-related order timing, providing West Pharma with additional opportunities to participate in the development of complex injectable therapies.
Key Challenges Facing WST
West Vantage Remains a Near-Term Drag on Growth: West Vantage remains the weakest-performing major segment, with second-quarter organic revenue growth of only 0.8% versus 15.5% growth for the Proprietary Products segment. Management attributed the shortfall partly to the cyber incident, estimating a mid-single-digit impact on segment growth and pushing some revenues into the second half.
The pressure is likely to persist in the third quarter because the quarter represents the first period following the exit of a CGM contract. Management expects West Vantage revenues to reach a trough in the third quarter before improving in the fourth quarter as drug-handling operations increase. This creates near-term volatility and makes the company increasingly dependent on Proprietary Products to sustain consolidated growth.
Commodity Inflation Could Pressure Margin Expansion: West Pharma is facing higher costs from oil and commodity prices, creating a potential headwind for the company’s margin trajectory. Management said it is working to offset inflation through pricing and other measures, with pricing contributing 4 percentage points to the second-quarter revenue growth, above its historical 2-3% range.
However, greater reliance on pricing has the potential to hurt customer acceptance and the company’s ability to continue capturing the value of its products. While management maintained its margin outlook and expects more than 200 basis points of operating-margin expansion in 2026, persistent input-cost inflation could limit the pace of improvement if pricing does not fully offset higher production costs.
West Pharmaceutical Services, Inc. Price
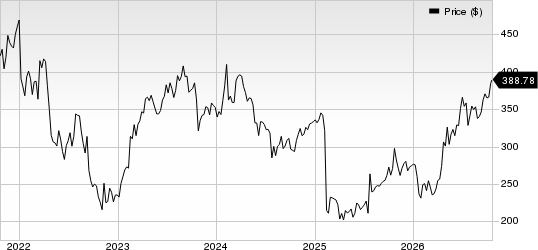
West Pharmaceutical Services, Inc. price | West Pharmaceutical Services, Inc. Quote
Estimate Trend
WST has been witnessing a stable estimate revision for 2026. In the past 60 days, the Zacks Consensus Estimate for earnings has remained stable at $8.93 per share, implying a gain of 22.5% from the prior-year reported level. The consensus mark for revenues is pegged at $3.37 billion, indicating a 9.7% increase from the 2025 reported level.
Other Key Picks
Some other top-ranked stocks from the broader medical space are Glaukos GKOS, Edward Lifesciences EW and Globus Medical GMED, each carrying a Zacks Rank of 2 at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Glaukos reported second-quarter 2026 earnings per share of 14 cents, which beat the Zacks Consensus Estimate by 50.00%. Revenues of $186 million surpassed the Zacks Consensus Estimate by 24.1%.
Glaukos has an estimated earnings growth rate of 268.8% for 2027. GKOS’ earnings surpassed estimates in three of the trailing four quarters and missed once, the average surprise being 25.87%.
Edward Lifesciences reported second-quarter 2026 adjusted EPS of 78 cents, which beat the Zacks Consensus Estimate by 6.85%. Revenues of $1.74 billion surpassed the Zacks Consensus Estimate by 2.45%.
Edward Lifesciences has an estimated long-term earnings growth rate of 12.7%. EW’s earnings surpassed estimates in three of the trailing four quarters and missed once, the average surprise being 4.49%.
Globus Medical reported a second-quarter fiscal 2026 adjusted EPS of $1.34, which beat the Zacks Consensus Estimate by 19.6%. Revenues of $790 million missed the Zacks Consensus Estimate by 0.35%.
Globus Medical has an estimated long-term earnings growth rate of 12.4%. GMED’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 27.88%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
West Pharmaceutical Services, Inc. (WST): Free Stock Analysis Report
Edwards Lifesciences Corporation (EW): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Glaukos Corporation (GKOS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).