

Abbott Laboratories ABT used its third-quarter 2026 earnings call to outline a major portfolio restructuring, announcing plans to separate its Nutrition business into an independent publicly traded company.
Management also addressed reduced revenue growth expectations, competitive pressures in diabetes care and upcoming product launches. The discussion emphasized long-term portfolio positioning alongside near-term execution challenges.
ABT Outlines Nutrition Separation Strategy
Chairman and CEO Robert Ford said the planned separation reflects increasingly different investment requirements, customer bases and growth profiles across Abbott's businesses. Nutrition has become more influenced by consumer preferences, wellness trends and retail execution.
The proposed company generates approximately $8.5 billion in annual sales and includes brands such as Similac, Ensure and PediaSure. Daniel Salvadori will lead the independent business.
CFO Philip Boudreau expects the transaction to be completed by the end of 2027, subject to approvals. Excluding Nutrition's current financial profile, Abbott expects sales growth to accelerate by 50-100 basis points and operating margin to increase approximately 100 basis points.
Abbott Revises Revenue Growth Expectations
Abbott now projects approximately 6% comparable sales growth for 2026. Adjusted earnings guidance was narrowed to $5.50-$5.55 per share, while fourth-quarter adjusted EPS is projected at $1.62-$1.67.
ABT’s quarterly adjusted EPS of $1.42 missed the Zacks Consensus Estimate of $1.43. Third-quarter revenues came in at $13.01 billion, exceeding the Zacks Consensus Estimate of $12.97 billion.
Abbott Laboratories Price, Consensus and EPS Surprise
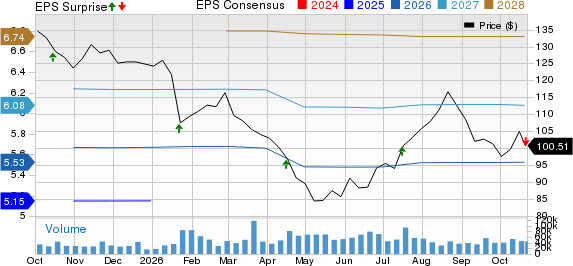
Abbott Laboratories price-consensus-eps-surprise-chart | Abbott Laboratories Quote
During questioning from Wells Fargo, Ford attributed the revised revenue outlook primarily to electrophysiology and diabetes care. He described the pressures as temporary rather than permanent changes in underlying growth potential.
ABT Sees Electrophysiology Launch Momentum
Electrophysiology delivered 15.5% comparable growth, supported by adoption of the Volt pulsed field ablation catheter. Ford highlighted accelerating U.S. demand following its full market release in August.
However, weaker left atrial appendage closure demand has offset some ablation momentum. Ford expects approximately 20% electrophysiology growth in the fourth quarter compared with an earlier expectation near 25%.
Abbott anticipates additional momentum from TactiFlex Duo and Volt's planned Japanese launch. Ford also expects the newer Amulet 360 device to help address existing market challenges.
Abbott Faces Diabetes Pricing and Coverage Pressures
Ford acknowledged that continuous glucose monitoring growth faces greater international pricing competition and slower penetration among patients with type 2 diabetes without broader reimbursement coverage.
Management expects diabetes growth in the low-to-mid-single-digit range over the next several quarters. Abbott plans selective international pricing adjustments while pursuing longer-term customer contracts and protecting market share.
During Citigroup's questioning, Ford declined to forecast when Medicare reimbursement might expand to non-insulin-using type 2 patients. He emphasized that such an expansion is not currently factored into expectations. Libre Duo's planned December launch and improved U.S. formulary coverage offer additional growth opportunities.
ABT Details Cancer Diagnostics Opportunities
Cancer Diagnostics posted 13.8% comparable sales growth, supported by Cologuard and precision oncology activities.
Responding to Jefferies, Ford explained that a July cybersecurity incident disrupted customer connectivity and temporarily reduced growth by approximately one percentage point. He reported recovery after affected systems resumed operations.
Ford also highlighted the recently introduced SimpleScreen blood-based colorectal cancer test. While acknowledging its broader screening potential, he maintained that stool-based testing offers stronger early-detection performance. Management continues advancing personalized cancer diagnostics and integration efforts following the Exact Sciences acquisition.
Abbott Maintains Investment and Capital Flexibility
Ford said research and development spending will exceed $3 billion in 2026, with further investment planned for 2027. Priorities include leadless pacing, structural heart technologies, intravascular lithotripsy and additional biosensor applications.
During Citigroup's questions, Ford emphasized that the Nutrition separation would not restrict Abbott's acquisition strategy. Near-term transactions will primarily involve smaller complementary acquisitions.
Boudreau reported an adjusted gross margin of 57.2%, up 140 basis points year over year. Management continues pursuing operational efficiencies alongside innovation investment.
ABT Emphasizes Execution Entering 2027
Ford expects sales growth to accelerate in 2027 but indicated that initial guidance will take a more conservative approach. Formal projections will follow in January.
Management's overall message combined confidence in the product pipeline with caution surrounding pricing, reimbursement and launch timing. The Nutrition separation remains central to Abbott's longer-term strategic direction.
Abbott's Zacks Rank and Style Scores
Abbott currently carries a Zacks Rank #2 (Buy), indicating favorable near-term earnings estimate revision characteristics. Its Value, Growth and VGM Scores are C, with a Momentum Score of D. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
These scores indicate moderate value and growth characteristics but weaker price momentum. The combination offers a mixed assessment despite the favorable Zacks Rank. The company's ranking may change as analysts revise earnings estimates following the third-quarter results.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Abbott Laboratories (ABT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).