

Lockheed Martin Corporation LMT emphasized accelerating missile production, multiyear defense contracts and improved revenue visibility during its third-quarter 2026 earnings call. Management raised its annual outlook as demand strengthened across its portfolio.
Executives also discussed F-35 production stability, investments in autonomous systems and protections built into long-term contracts. Analyst questions centered on profitability, cash requirements and growth beyond 2027.
LMT Raises 2026 Outlook on Broad-Based Growth
Chief financial officer Evan Scott raised Lockheed Martin's 2026 sales guidance to $80-$82 billion from the previous $79.75-$81.75 billion range. The revised midpoint represents approximately 8% annual growth.
Business segment operating profit is now projected at $8.575-$8.675 billion. Management also increased free cash flow guidance to $7.8-$8 billion from $7-$7.2 billion.
Quarterly earnings of $7.97 per share surpassed the consensus estimate of $7.49. Third-quarter revenues increased to $20.71 billion, exceeding the Zacks Consensus Estimate of $20.43 billion. Scott attributed the stronger outlook primarily to higher missile production volumes and improved program execution.
Lockheed Martin Corporation Price, Consensus and EPS Surprise
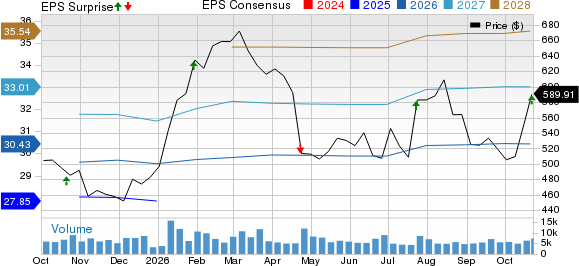
Lockheed Martin Corporation price-consensus-eps-surprise-chart | Lockheed Martin Corporation Quote
Lockheed's Missile Expansion Drives Backlog Growth
Chairman, president and CEO James Taiclet highlighted accelerating production across the Missiles and Fire Control (“MFC”) business. Segment revenues and operating profit both increased 24% year over year.
Lockheed's backlog reached a record $292 billion, supported by a seven-year PAC-3 agreement valued at up to $58.6 billion. The company's quarterly book-to-bill ratio reached 4.
Scott expects MFC revenues to grow at a mid-teens compound annual rate over the next five years. Management is investing more than $8 billion through 2030 to expand production infrastructure, strengthen suppliers and increase manufacturing capacity.
LMT Details Contract Protections and Margin Potential
During the Q&A, a Goldman Sachs analyst questioned the financial risks associated with accelerated missile production and evolving contract structures.
Scott explained that customer agreements include cash-flow-neutrality provisions during production ramp-ups. However, final profit terms and delivery schedules remain under negotiation.
Taiclet emphasized that Lockheed intends to preserve or improve historical financial returns. Contract provisions include inflation-linked pricing adjustments, opportunities to retain efficiency-driven profits and mechanisms to recover investments if contracted production volumes decline.
Lockheed Addresses F-35 Timing and Profitability
Aeronautics revenues increased 13% year over year, supported by higher F-35 production and sustainment activity. However, unfavorable adjustments on F-16 and C-130 programs weighed on profitability.
Management shifted its assumption for certain F-35 contract awards into 2027, lowering Aeronautics' annual outlook. Scott clarified that signing Lot 20 during 2026 would provide upside beyond current guidance.
Responding to a Jefferies analyst, Scott said F-35 production remains margin-accretive. Taiclet explained that the proposed 10-year procurement framework could improve supplier efficiency, sustainment economics and modernization investments.
LMT Accelerates Autonomous Systems Development
Taiclet highlighted Vectis, Lockheed's autonomous aircraft initiative, as evidence of faster internal development. The company plans to build five aircraft using its own investment, with flight demonstrations scheduled for 2027.
During questioning from BofA Securities, Taiclet described Vectis as part of a broader strategy combining upgraded F-22 fighters, improved F-35 capabilities and collaborative combat aircraft.
Management also emphasized digital engineering, artificial intelligence and cross-segment technology integration. These efforts aim to shorten development cycles while positioning Lockheed for future defense programs.
Lockheed Sees Growth Extending Into 2027
Responding to a Wolfe Research analyst, Scott indicated that all four business segments should generate revenue growth in 2027, supporting high-single-digit companywide growth.
Cash flow faces an anticipated pension contribution exceeding $1 billion next year. Management is evaluating whether to prefund that obligation during 2026.
Scott also expects continued tax benefits, although smaller than those realized this year. The planned Ultra Maritime acquisition remains on track for a fourth-quarter closing.
LMT Maintains Focus on Execution and Capacity
Management's overall message centered on converting contracted demand into sustained production growth while maintaining financial discipline.
Taiclet emphasized manufacturing expansion, supplier readiness and faster technology deployment. Near-term priorities remain contract execution, production scaling and preserving cash generation through the investment cycle.
What LMT's Zacks Rank and Style Scores Indicate
Lockheed currently carries a Zacks Rank #3 (Hold), indicating a neutral near-term earnings-revision outlook. Its Growth Score of A and Value Score of B reflect favorable growth and valuation characteristics, while its Momentum Score of F indicates weaker price momentum. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The company's VGM Score of B reflects a favorable combination of value, growth and momentum characteristics. However, the neutral Zacks Rank tempers these favorable style indicators. The Zacks Rank can change as analysts revise their earnings estimates following the third-quarter results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Lockheed Martin Corporation (LMT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).